Charitable Remainder Trust Explained
Navigating the complexities of estate planning can feel overwhelming, especially when you have a strong desire to support charitable causes while also ensuring your own financial security. Many folks wrestle with the idea of giving away significant assets now versus holding onto them for retirement, all while dreading the tax implications that seem to lurk around every corner. This guide is here to shed light on Charitable Remainder Trusts (CRTs), a powerful estate planning tool that allows you to address these very concerns, offering a unique blend of philanthropy, income generation, and substantial tax benefits.
Understanding the Charitable Remainder Trust Basics
The world of trusts can feel like a labyrinth, full of jargon and intricate rules. But at its heart, a Charitable Remainder Trust, or CRT, is a beautifully structured way to give to charity while still taking care of yourself and your loved ones financially. It's a testament to the idea that you don't have to choose between leaving a legacy and maintaining your comfort.
What Exactly Is a Charitable Remainder Trust?
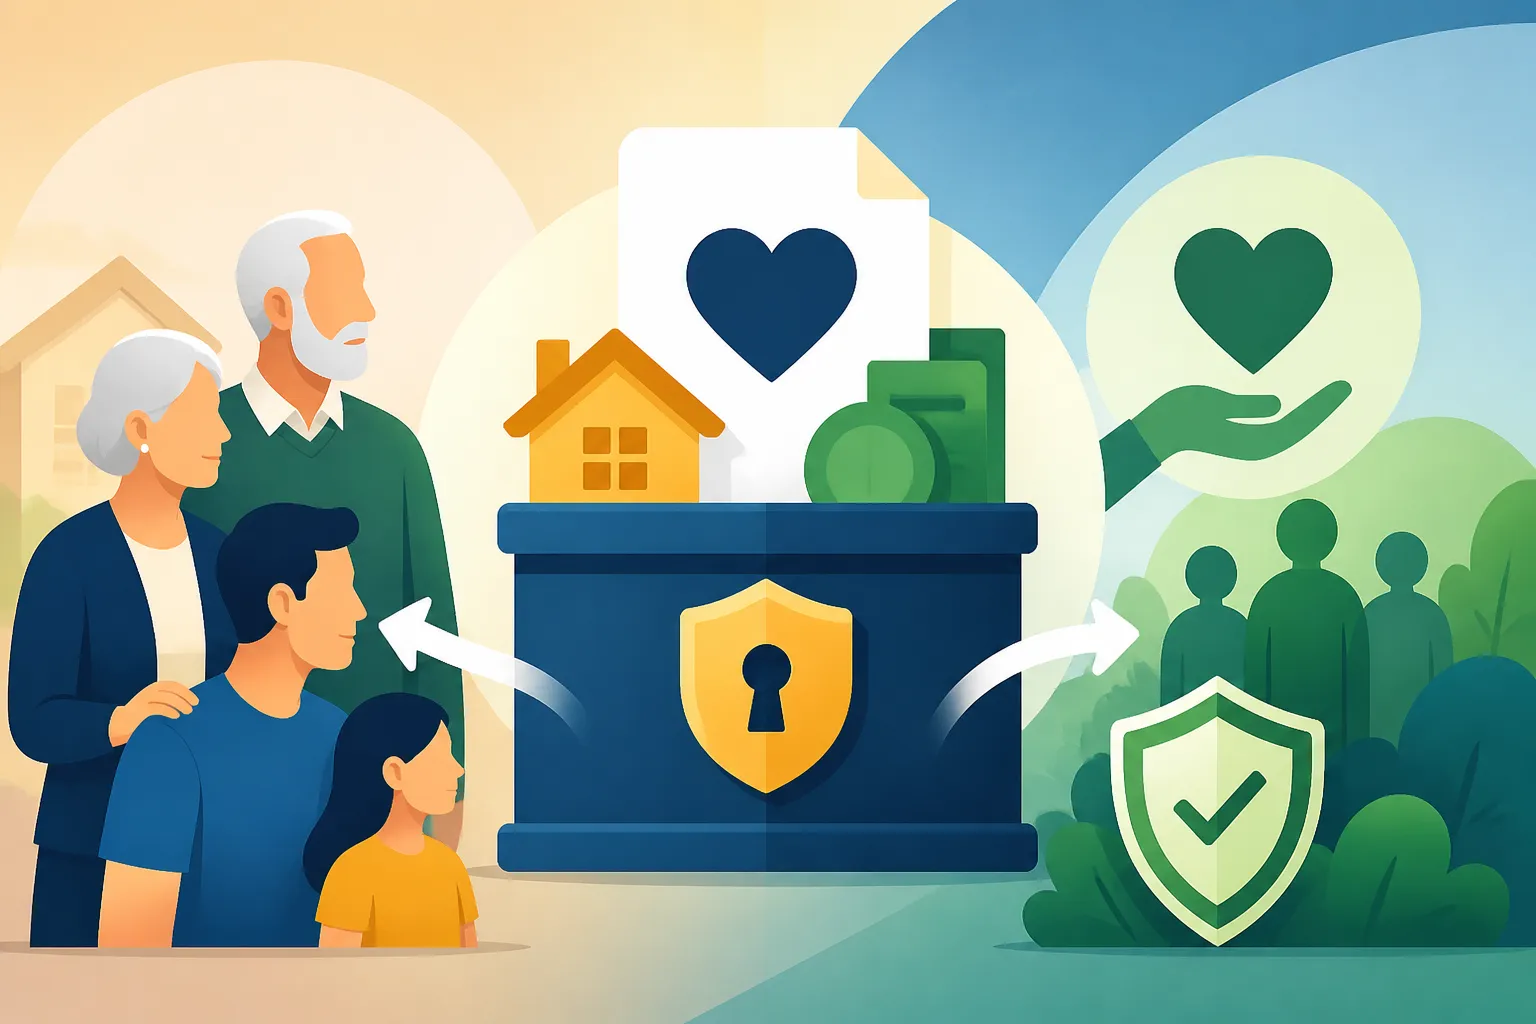
Think of a Charitable Remainder Trust as a special type of irrevocable trust where you, the grantor, transfer assets into it. The twist? This trust has two distinct beneficiaries. First, there's a non-charitable beneficiary (often yourself, your spouse, or other loved ones) who receives income payments for a specified term, which can be for life or a set number of years (up to 20). Second, there's a charitable organization that eventually receives the "remainder" of the trust assets after the income period ends. It's a forward-thinking plan that secures an income stream today and provides a substantial gift to your chosen charity tomorrow. The IRS officially recognizes and regulates these trusts under specific tax codes, making them a legitimate and widely used strategy in sophisticated estate planning.
Many people find the concept appealing because it allows them to make a significant charitable donation without depleting their current income or assets entirely. For instance, imagine you own a valuable piece of appreciated real estate that you're considering selling. If you sell it outright, you'd face a hefty capital gains tax bill. However, by placing it into a CRT first, you can potentially bypass that immediate tax hit, which we'll dive into more deeply later. This structure provides a beautiful synergy, benefiting both you and the causes you care about.
How Does a Charitable Remainder Trust Work?
The process of establishing and operating a CRT follows a clear path, though it involves several steps that require careful planning. It begins when you, as the grantor, decide to transfer assets into the trust. These assets can be highly appreciated stocks, real estate, or even business interests. Once the assets are transferred, the trust then sells them, ideally without incurring immediate capital gains tax because the trust itself is a tax-exempt entity. This is one of the most compelling features for individuals holding highly appreciated assets.
After the assets are sold, the proceeds are invested by the trustee. From this invested pool, regular income payments are made to the non-charitable beneficiary (or beneficiaries) for the duration of the trust term. This could be monthly, quarterly, or annually, depending on the trust's specific terms. Once this income period concludes—either upon the death of the income beneficiaries or at the end of the set term—the remaining assets are distributed to the designated charitable organization. This final distribution fulfills the charitable intent that is central to the CRT's purpose. Understanding How State Estate Tax Works often involves considering how trusts like these can impact the overall size of an estate.
Key Players in a Charitable Remainder Trust
Successfully setting up and managing a Charitable Remainder Trust requires several key roles, each with distinct responsibilities. Understanding who does what can demystify the process considerably.
The first and most crucial player is the Grantor (sometimes called the Donor or Settlor). This is you, the individual or couple creating the trust and contributing the assets. You are the one driving the philanthropic and financial goals of the CRT. Your intentions and the assets you choose to fund the trust with will largely dictate its structure and function. For example, if you're a high-net-worth individual with a significant portfolio of long-held stocks, you'd be the grantor deciding to transfer those shares into the CRT.
Next, we have the Trustee. This is the individual or entity responsible for managing the trust's assets, making investment decisions, calculating and distributing income payments, and ensuring the trust complies with all IRS regulations. The trustee's role is critical, requiring financial acumen and a deep understanding of trust administration. You can name yourself as trustee, but it's often advisable to appoint an independent third party, such as a bank, trust company, or a professional fiduciary, especially given the complexity involved. While some basic estate planning documents can be prepared with services like LegalZoom, the intricate nature of a CRT often demands a dedicated professional trustee or attorney to ensure compliance and optimal management.
Then there's the Non-Charitable Beneficiary, also known as the income beneficiary. This is the person or people (which can include the grantor) who receive the regular income payments from the trust for the specified term. This income stream is a core component of the CRT's benefit to you and your family, providing financial support during your lifetime or for a fixed period. For example, you might set up a CRT to provide income for yourself and your spouse during retirement, or even for an adult child for a defined number of years.
Finally, the Charitable Beneficiary is the qualified charity or charities that will ultimately receive the remainder of the trust's assets once the income payment period concludes. This could be your alma mater, a local hospital, an environmental organization, or any other IRS-approved public charity. This is where your philanthropic intent comes to fruition, leaving a lasting legacy. Choosing the right charitable beneficiary is a deeply personal decision, reflecting the causes that matter most to you.
The Two Main Types of Charitable Remainder Trusts
While the overarching goal of all CRTs is similar—providing income now and a charitable gift later—they come in two primary flavors, each with distinct characteristics that might make one a better fit for your financial situation and income needs. It's not a one-size-fits-all solution, and understanding the differences is key to making an informed choice.
Charitable Remainder Annuity Trust CRAT Explained
The Charitable Remainder Annuity Trust, or CRAT, is designed for those who value predictability above all else. With a CRAT, the non-charitable beneficiary receives a fixed annuity amount each year. This payment is determined when the trust is first established and remains constant for the entire term of the trust. This means that regardless of how the trust's investments perform, your annual payment won't change. It's like having a steady, reliable paycheck.
A significant characteristic of a CRAT is that no additional contributions can be made to the trust after its initial funding. Once you've transferred your assets, that's it. This can be a pro for some, simplifying future administration, but a con for others who might wish to add more assets over time. The fixed payment also means that if the trust''s investments perform exceptionally well, the excess growth beyond what's needed for the annuity payments accrues to the charitable remainder. Conversely, if investments perform poorly, the trustee must still pay the fixed annuity, potentially eroding the principal more quickly. The fixed nature of the payment ensures a guaranteed income, offering peace of mind, but it does mean you won't benefit directly from significant market upside within the trust itself. Many people find this setup ideal if they have a clear idea of their future income needs and want to secure that amount, regardless of market volatility.
Charitable Remainder Unitrust CRUT Explained
In contrast to the CRAT's fixed payments, the Charitable Remainder Unitrust, or CRUT, offers a more dynamic approach to income distribution. With a CRUT, the non-charitable beneficiary receives a fixed percentage of the trust's fair market value, revalued annually. This means your income payments will fluctuate year-to-year based on the performance and valuation of the trust's assets. If the trust's investments grow, your payments will likely increase; if they decline, your payments will decrease. This aligns your income more closely with the trust's performance, which can be an attractive feature for those who want to participate in potential asset appreciation.
Another key difference is that CRUTs can accept additional contributions after their initial funding. This flexibility allows you to add assets to the trust over time, potentially increasing your future income stream and the eventual charitable gift. There are also several variations of CRUTs that cater to different needs:
- Net Income Charitable Remainder Unitrust (NICRUT): This type pays out the lesser of the fixed percentage or the actual net income of the trust. This can be beneficial if the trust holds assets that don't generate much income initially, like undeveloped land, but are expected to grow significantly.
- Net Income with Makeup Charitable Remainder Unitrust (NIMCRUT): Similar to a NICRUT, but it includes a "makeup" provision. If the trust's income in earlier years was less than the stated percentage, it can make up those shortfalls in later years when income exceeds the percentage. This is often used for assets that will eventually be sold for a large gain, deferring income until that point.
- FLIP Charitable Remainder Unitrust (FLIP CRUT): This type begins as a NICRUT or NIMCRUT but "flips" to a standard CRUT (paying the fixed percentage regardless of income) upon the occurrence of a specific event, such as the sale of an unmarketable asset like real estate. This allows the trust to start with low income and then provide full unitrust payments after the asset is liquidated.
Choosing between a CRAT and a CRUT depends heavily on your personal financial goals, your risk tolerance, and the nature of the assets you plan to contribute. Both offer powerful benefits, but their mechanics are quite different, impacting your future income directly. When you're thinking about Will vs Trust: Which Do You Need?, remember that sophisticated tools like CRTs are specifically designed for very particular circumstances.
Significant Benefits of Establishing a Charitable Remainder Trust
It's easy to get caught up in the technical details of trusts, but let's be real: people establish CRTs because they offer tangible, compelling benefits. These aren't just obscure legal instruments; they are strategic financial tools that can profoundly impact your personal wealth, your family's future, and the causes you care deeply about.
Income Stream for Life or a Set Term
One of the most immediate and attractive benefits of a Charitable Remainder Trust is the ability to create a consistent income stream for yourself or designated beneficiaries for a considerable period. Imagine transitioning into retirement with the comfort of knowing a portion of your living expenses is covered by predictable payments from a trust you've established. This can be a huge relief, especially if you're worried about market volatility impacting your other investments.
Whether you opt for the fixed annuity of a CRAT or the fluctuating unitrust payments of a CRUT, this income stream can supplement your retirement savings, cover healthcare costs, or simply provide financial stability. For instance, if you're a couple nearing retirement age, you could establish a CRT that pays income for the rest of both your lives. This structure ensures that even as you make a significant commitment to charity, your immediate financial needs and desires for stability are not just met but actively supported by the trust itself. It’s a powerful way to turn what might otherwise be a one-time donation into a lifetime of financial support, making the act of giving incredibly sustainable for you.
Immediate Income Tax Deductions
Let's talk taxes, because that's where CRTs really shine for many people. When you contribute assets to a Charitable Remainder Trust, you become eligible for an immediate federal income tax deduction. This isn't a small perk; it can be a substantial deduction, especially if you're funding the trust with valuable assets. The amount of your deduction is based on the present value of the future charitable gift—the "remainder interest"—which is calculated using IRS actuarial tables, the trust's payout rate, and the term of the trust.
For example, if you transfer $1 million in appreciated stock to a CRT and the calculated remainder interest for charity is $400,000, you could potentially claim an income tax deduction for that $400,000 in the year of the contribution. This deduction can offset a significant portion of your taxable income, potentially reducing your tax bill for the current year. If the deduction is larger than what you can use in one year, you can typically carry forward the unused portion for up to five additional years. This immediate tax savings provides a direct financial incentive, allowing you to effectively lower your current tax burden while simultaneously setting up a future charitable gift. It’s a win-win that many find incredibly appealing.
Avoiding Capital Gains Tax on Appreciated Assets
Perhaps one of the most compelling tax advantages of a Charitable Remainder Trust is its ability to help you bypass immediate capital gains tax when selling highly appreciated assets. Imagine you've held a stock or a piece of real estate for decades, and its value has soared. If you were to sell that asset outright, you'd owe capital gains tax on the difference between your original purchase price (cost basis) and the sale price. This tax can be a substantial bite out of your profits, deterring many from selling, even if it's financially prudent.
However, when you transfer these appreciated assets to a CRT, the trust (which is a tax-exempt entity) can then sell those assets without immediately incurring capital gains tax. This means the entire sale proceeds can be reinvested within the trust, allowing for a much larger principal to generate income for you. You don't pay capital gains tax on the sale itself; instead, the payments you receive from the trust are taxed as ordinary income as you receive them. This allows you to convert a highly appreciated, low-basis asset into a diversified income stream, deferring and spreading out the tax liability over many years. This strategy is incredibly powerful for unlocking the value of assets like long-held family businesses or growth stocks without the immediate tax hit. It's a prime example of how trusts can How to Avoid Estate Tax With Trusts by restructuring asset ownership.
Estate Tax Reduction
Beyond the income tax and capital gains benefits, CRTs also play a crucial role in reducing the size of your taxable estate, which can lead to significant estate tax savings for your heirs. When you transfer assets irrevocably to a Charitable Remainder Trust, those assets are removed from your gross estate. This means they are no longer subject to federal estate tax (and potentially state estate tax, depending on where you live and the size of your estate) upon your passing.
For individuals with substantial wealth, facing the prospect of a Federal Estate Tax Exemption 2026 ($15 Million) can be daunting, and planning to reduce the size of the estate is paramount. By removing assets from your estate through a CRT, you effectively shrink the portion of your wealth that could be subject to estate taxes. This not only preserves more of your wealth for your non-charitable beneficiaries (through the income stream) but also ensures a larger portion goes to your chosen charity, rather than to taxes. The double benefit of providing for your lifetime income and reducing your estate's tax burden makes CRTs an attractive option for comprehensive estate planning. For families concerned about their What Is the Gross Estate? definition, a CRT can be a strategic way to manage it.
Potential Drawbacks and Considerations
While Charitable Remainder Trusts offer impressive advantages, it's crucial to approach them with a clear understanding of their limitations and potential downsides. Like any sophisticated financial instrument, they aren't without their complexities and trade-offs. What works perfectly for one person might be entirely unsuitable for another.
Irrevocability and Loss of Control
One of the most significant aspects of a Charitable Remainder Trust, and one that gives many people pause, is its irrevocable nature. Once you transfer assets into a CRT, they are no longer truly yours. You cannot take them back, change the charitable beneficiary (except in limited circumstances if the trust document permits), or alter the terms of the income payments. This loss of direct control can be a tough pill to swallow for those accustomed to managing their own investments freely.
This irrevocability means you need to be absolutely certain about your decision before funding the trust. It's a long-term commitment, locking in your philanthropic intent and your income structure for the duration of the trust term. While this commitment is what allows for the significant tax benefits, it also demands careful consideration of your future financial needs and personal goals. If there's any chance you might need to access the principal of the assets you're considering for the CRT, then this structure might not be the right fit. It underscores why working with experienced estate planning attorneys is so vital, far beyond what general platforms like LegalZoom might offer for simpler documents. They can help you thoroughly evaluate whether giving up control over these specific assets aligns with your broader financial picture.
Complexity and Costs of Administration
Let's not sugarcoat it: Charitable Remainder Trusts are complex legal and financial instruments. They aren't simple "set it and forget it" solutions. Establishing and maintaining a CRT involves a significant amount of legal work, accounting, and ongoing administration. This complexity translates directly into costs, both upfront and recurring.
Initially, you'll need a skilled estate planning attorney to draft the trust document, ensuring it complies with all IRS regulations and accurately reflects your intentions. This isn't a DIY project. Legal fees for drafting a CRT can be substantial, reflecting the specialized knowledge required. Beyond the setup, there are ongoing administrative costs. The trustee, whether an individual or a corporate entity, needs to manage investments, calculate and distribute payments, and file annual tax returns for the trust (Form 5227, Split-Interest Trust Information Return). Professional trustees, like major financial institutions, will charge fees for their services, often a percentage of the trust's assets. There will also be accounting fees for preparing the trust's annual tax filings. These recurring costs can eat into the trust's principal, so you need to ensure the potential benefits outweigh these administrative expenses. Typically, CRTs are most cost-effective for estates valued at several hundred thousand dollars or more. Considering these ongoing costs is an essential part of an Estate Planning Checklist.
Income Tax on Distributions
While a CRT helps you avoid immediate capital gains tax on the sale of appreciated assets within the trust, it's crucial to remember that the income payments you receive from the trust are not tax-free. These distributions are subject to income tax, generally as ordinary income, in the hands of the non-charitable beneficiary. The IRS uses a specific four-tier system to characterize the income distributed from a CRT:
- Ordinary Income: This is the first tier and typically comes from interest, dividends, or rental income earned by the trust.
- Capital Gains: If the ordinary income isn't enough to cover the payout, the next tier is capital gains realized by the trust. This is often where the initial tax-free sale of appreciated assets comes into play, as the capital gains are passed through to you over time.
- Tax-Exempt Income: If both ordinary income and capital gains are insufficient, tax-exempt income (like from municipal bonds) would be distributed.
- Return of Principal: Finally, if all other tiers are exhausted, the distribution would be considered a tax-free return of principal.
This ordering rule means that you typically pay income tax on the distributions at your ordinary income tax rates or capital gains rates until all of those tiers are exhausted. So, while the initial sale within the trust is tax-exempt, the tax liability is essentially deferred and spread out over the period you receive payments. It’s not about avoiding taxes entirely on the gain, but rather strategically managing when and how those taxes are paid. This careful management of tax liability is a critical consideration in effective Estate Planning for High Net Worth Families.
Who Benefits Most from a Charitable Remainder Trust?
Charitable Remainder Trusts are powerful tools, but they're not for everyone. They truly shine for a specific demographic and financial situation. Understanding who stands to gain the most can help you determine if a CRT aligns with your personal and financial goals.
High-Net-Worth Individuals with Appreciated Assets
The individuals who typically benefit most from CRTs are high-net-worth individuals who possess substantial appreciated assets. We're talking about folks who have held onto a successful stock portfolio, a valuable piece of undeveloped land, or perhaps a thriving family business for many years. These assets have grown significantly in value since their acquisition, meaning if they were sold outright, they would trigger a hefty capital gains tax bill.
For example, consider a retired entrepreneur in San Francisco who owns a diversified portfolio of tech stocks purchased decades ago for a fraction of their current multi-million-dollar value. If they sold these stocks to generate retirement income, they'd immediately lose a large chunk to capital gains taxes. By transferring these stocks into a CRT, the trust can sell them tax-free, reinvest the full proceeds, and then provide an income stream. This allows the entrepreneur to unlock the full value of their investments without the immediate tax drag, effectively increasing the principal that generates their income. This strategy is particularly effective when considering how to handle assets that are part of your What Is the Gross Estate? calculation.
Philanthropically Minded Individuals
At the core of a Charitable Remainder Trust is, as the name suggests, a charitable intent. These trusts are explicitly designed for individuals who have a genuine desire to support one or more qualified charitable organizations. While the personal financial benefits are significant, the fundamental purpose is to leave a legacy and contribute to causes you believe in.
If you envision a portion of your wealth going to your alma mater, a medical research foundation, your local church, or an animal rescue organization, a CRT offers a structured way to achieve that. It's not just about giving; it's about strategic giving that maximizes the impact of your donation while simultaneously providing personal financial advantages. You get to feel good about making a future difference, knowing your chosen charity will eventually receive a substantial gift, helping them continue their important work. This aligns perfectly with the goal of How to Avoid Estate Tax Legally while also fulfilling philanthropic desires.
Those Seeking Current Income Tax Breaks and Future Estate Tax Savings
The "sweet spot" for a CRT often lies with individuals who are looking for a dual benefit: immediate income tax deductions and future estate tax savings. If you're currently in a high income tax bracket, the upfront charitable deduction from funding a CRT can provide a much-needed offset, significantly reducing your taxable income for the year you make the contribution (and potentially for several years after).
Simultaneously, by removing assets from your estate and dedicating the remainder interest to charity, you effectively reduce the size of your taxable estate. This is particularly valuable for individuals whose estates are at risk of exceeding the federal estate tax exemption, which is $15,000,000 per individual for 2026. By strategically using a CRT, you can minimize the portion of your wealth that might otherwise be subjected to high federal or state estate taxes, preserving more value for your heirs (through the income stream) and for your chosen charity. It's a comprehensive approach to wealth management that leverages tax codes to achieve both personal financial security and philanthropic goals.
Navigating the Setup Process and Choosing a Trustee
Establishing a Charitable Remainder Trust isn't something you can do overnight, nor is it a simple form you fill out. It's a complex legal and financial undertaking that requires careful thought and professional guidance. The choices you make during the setup process, particularly regarding legal counsel and the trustee, will significantly impact the trust's effectiveness and your peace of mind.
The Role of Legal and Financial Professionals
When it comes to setting up a CRT, you absolutely need a team of seasoned professionals on your side. This isn't the type of document you'd typically find on a basic online legal platform; while services like LegalZoom can be helpful for simple wills or business formations, a Charitable Remainder Trust demands specialized expertise. An experienced estate planning attorney is paramount. They will draft the trust document, ensuring it complies with all federal and state laws, meets the specific IRS requirements for CRTs, and accurately reflects your unique financial situation and philanthropic goals. They'll help you navigate the nuances between a CRAT and a CRUT, explain payout rates, and clarify the term options.
Beyond legal counsel, a knowledgeable financial advisor is equally important. This professional will help you identify the best assets to fund your CRT, analyze the potential income streams, project the tax deductions, and model the long-term financial impact on your overall wealth plan. They can also assist in managing the assets within the trust once it's funded, working closely with the trustee. Together, this team ensures that your CRT is not only legally sound but also financially optimized to achieve your objectives. These specialists often have a deep understanding of Types of Trusts Explained (ILIT, GRAT, QTIP & More) and can advise on the best fit for your situation.
Selecting the Right Trustee
The trustee of your Charitable Remainder Trust holds a significant amount of responsibility. This individual or entity is tasked with managing the trust's assets, making investment decisions, calculating and distributing income payments, handling all necessary tax filings, and generally ensuring the trust operates according to its terms and IRS regulations. Choosing the right trustee is a critical decision that shouldn't be taken lightly.
You have a few options:
- Individual Trustee: You can name yourself, a family member, or a trusted friend as trustee. The benefit here is often familiarity and a lack of professional fees (if they volunteer their time). However, this option comes with a considerable burden. The individual trustee must have a strong understanding of investment management, tax law (including the complex rules for CRTs), and fiduciary duties. Mistakes can be costly.
- Corporate Trustee: This typically involves appointing a bank, a trust company, or the trust department of a major financial institution. Corporate trustees bring professional expertise, impartiality, and continuity. They have established systems for investment management, accounting, and tax compliance. While they charge fees, these fees often provide immense value, reducing the administrative burden and ensuring proper adherence to all regulations. For complex trusts like CRTs, a corporate trustee is often recommended due to the specialized knowledge required. This professional management can significantly simplify the process compared to trying to manage everything yourself, especially if you used a more generalized tool like LegalZoom for initial estate planning.
Regardless of who you choose, ensure they are capable, trustworthy, and understand the specific responsibilities associated with a Charitable Remainder Trust. You might also consider naming a successor trustee in case the initial trustee becomes unable or unwilling to serve.
Funding Your Charitable Remainder Trust
Once your Charitable Remainder Trust document is legally drafted and signed, the next step is to fund it. This involves formally transferring assets from your name (as the grantor) into the name of the trust. This isn't just a symbolic gesture; it's a legal process that ensures the assets are owned by the trust, not by you personally.
Common assets used to fund CRTs include:
- Highly Appreciated Securities: Stocks, mutual funds, or other marketable securities that have seen significant growth are often ideal because of the capital gains tax avoidance benefit.
- Real Estate: Investment properties, vacation homes, or undeveloped land can also be excellent candidates, especially if they are difficult to sell or would incur substantial capital gains tax upon sale.
- Closely Held Business Interests: Shares in a privately owned company can also be contributed, though this often adds another layer of complexity regarding valuation and eventual sale.
The transfer process for each asset type will vary. For securities, it often involves working with your brokerage firm to retitle the accounts. For real estate, it requires drafting and recording new deeds that name the trust as the owner. Your estate planning attorney and financial advisor will guide you through each step to ensure the assets are properly transferred and titled, avoiding any potential snags or unintended tax consequences. Proper funding is crucial for the trust to begin generating income and fulfilling its charitable mission. Thinking about How to Avoid Probate often leads to discussions of how trusts manage assets outside of the probate court system.
Comparison of CRAT vs. CRUT
To help you visualize the differences between the two main types of Charitable Remainder Trusts, here's a table summarizing their key characteristics:
| Feature | Charitable Remainder Annuity Trust (CRAT) | Charitable Remainder Unitrust (CRUT) |
|---|---|---|
| Income Payment | Fixed dollar amount (annuity) | Fixed percentage of annually revalued trust assets |
| Payment Fluctuation | No, payment is constant | Yes, payment fluctuates with asset value |
| Additional Contributions | Not permitted after initial funding | Permitted |
| Beneficiary Risk/Reward | More predictable income, less upside participation | Income potential tied to asset growth, more volatility |
| Investment Performance | Excess growth accrues to charity; poor performance erodes principal faster | Growth benefits income beneficiary; declines reduce payments |
| Common Use Cases | Grantors needing stable, predictable income | Grantors desiring growth potential, future contributions |
| Complexity | Generally simpler administration once set up | More complex administration (annual revaluation) |
This table should provide a clear overview to help you and your advisors discuss which option best suits your specific financial and philanthropic goals. Whether you prioritize stability or growth, there's a CRT structure designed to meet that need.
Disclaimer
Please remember that the information provided in this guide is for general informational purposes only and should not be construed as legal, financial, or tax advice. Estate planning, especially involving complex instruments like Charitable Remainder Trusts, is highly individualized. The tax laws and regulations are subject to change and can be incredibly complex. We strongly recommend consulting with a qualified estate planning attorney, financial advisor, and tax professional to discuss your specific situation and ensure that any strategies you implement are appropriate for your personal circumstances and objectives.