Estate Tax Exemption by State: Full Chart 2026
Navigating the complexities of estate taxes can feel like a labyrinth, especially when you consider that rules and exemptions don't just vary at the federal level, but significantly from state to state. It’s easy to feel overwhelmed trying to figure out if your estate, or a loved one's, will be subject to a state estate tax and how much that might be. This guide aims to clear up that confusion by providing a comprehensive overview of state estate tax exemptions, helping you understand where things stand and what to keep in mind for your estate planning.
Understanding State Estate Taxes and Exemptions
When we talk about estate tax, it’s often the federal estate tax that first comes to mind. However, a significant layer of complexity is added by individual states, some of which impose their own estate taxes. These state-level taxes can catch families off guard, particularly if they haven't adequately planned for them. Knowing the difference and how exemptions work is absolutely critical for anyone looking to protect their legacy.
What is a State Estate Tax Anyway?
A state estate tax is a tax levied by a state on the total value of a deceased person's assets, often referred to as their "gross estate," before those assets are distributed to their heirs. Think of it as a final tax bill for the privilege of passing wealth down after you're gone. It's not paid by the beneficiaries directly from their inheritance, but rather by the estate itself. The estate's executor or personal representative is responsible for filing the necessary returns and ensuring the tax is paid before assets can be fully distributed to the designated heirs. This means that funds intended for beneficiaries might be significantly reduced if the estate falls above the exemption threshold in a taxing state.
The types of assets included in a gross estate for state tax purposes can be quite broad, mirroring what's typically included for federal estate tax calculations. This can encompass everything from real estate, bank accounts, stocks, bonds, and business interests to valuable personal property like artwork or jewelry. Even assets that pass outside of a will, such as certain trusts or life insurance policies where the estate is the beneficiary, can be included in this calculation. Understanding What Is the Gross Estate? is foundational to knowing if your estate will be subject to this tax.
The Importance of the Exemption Amount
The exemption amount is arguably the most crucial figure in estate tax planning, both federally and at the state level. It represents the total value of an estate that can pass to heirs completely free of estate tax. Only the portion of an estate's value that exceeds this exemption amount is subject to taxation. For example, if a state has a $5 million exemption and an estate is valued at $6 million, only $1 million would potentially be taxed. The higher the exemption, the more wealth can be passed on without incurring this specific tax.
The disparity between federal and state exemptions can be quite stark. In 2026, the federal estate tax exemption is $15,000,000 per individual. This means very few estates nationwide will owe federal estate tax. However, many states that impose an estate tax have much lower exemption thresholds, sometimes as low as $1 million. This creates a situation where an estate might be exempt from federal tax but heavily taxed at the state level. For instance, an estate in Oregon valued at $2 million would be far below the federal threshold, but still well above Oregon’s current $1 million exemption, potentially leading to a significant state tax bill. This is why it’s so vital to know not just if your state has an estate tax, but what its specific exemption is. You can also explore State Estate Tax Exemptions & Rates Compared 2026 for a broader perspective.
A Deep Dive into State Estate Tax Exemptions
It's common for people to assume that if they don't have a multi-million dollar estate, they don't need to worry about estate taxes at all. While that's often true for the federal estate tax, it's a dangerous assumption to make when it comes to state-level taxes. The exemptions can be significantly lower, bringing many more "average" estates into the taxable bracket.
States That Impose an Estate Tax
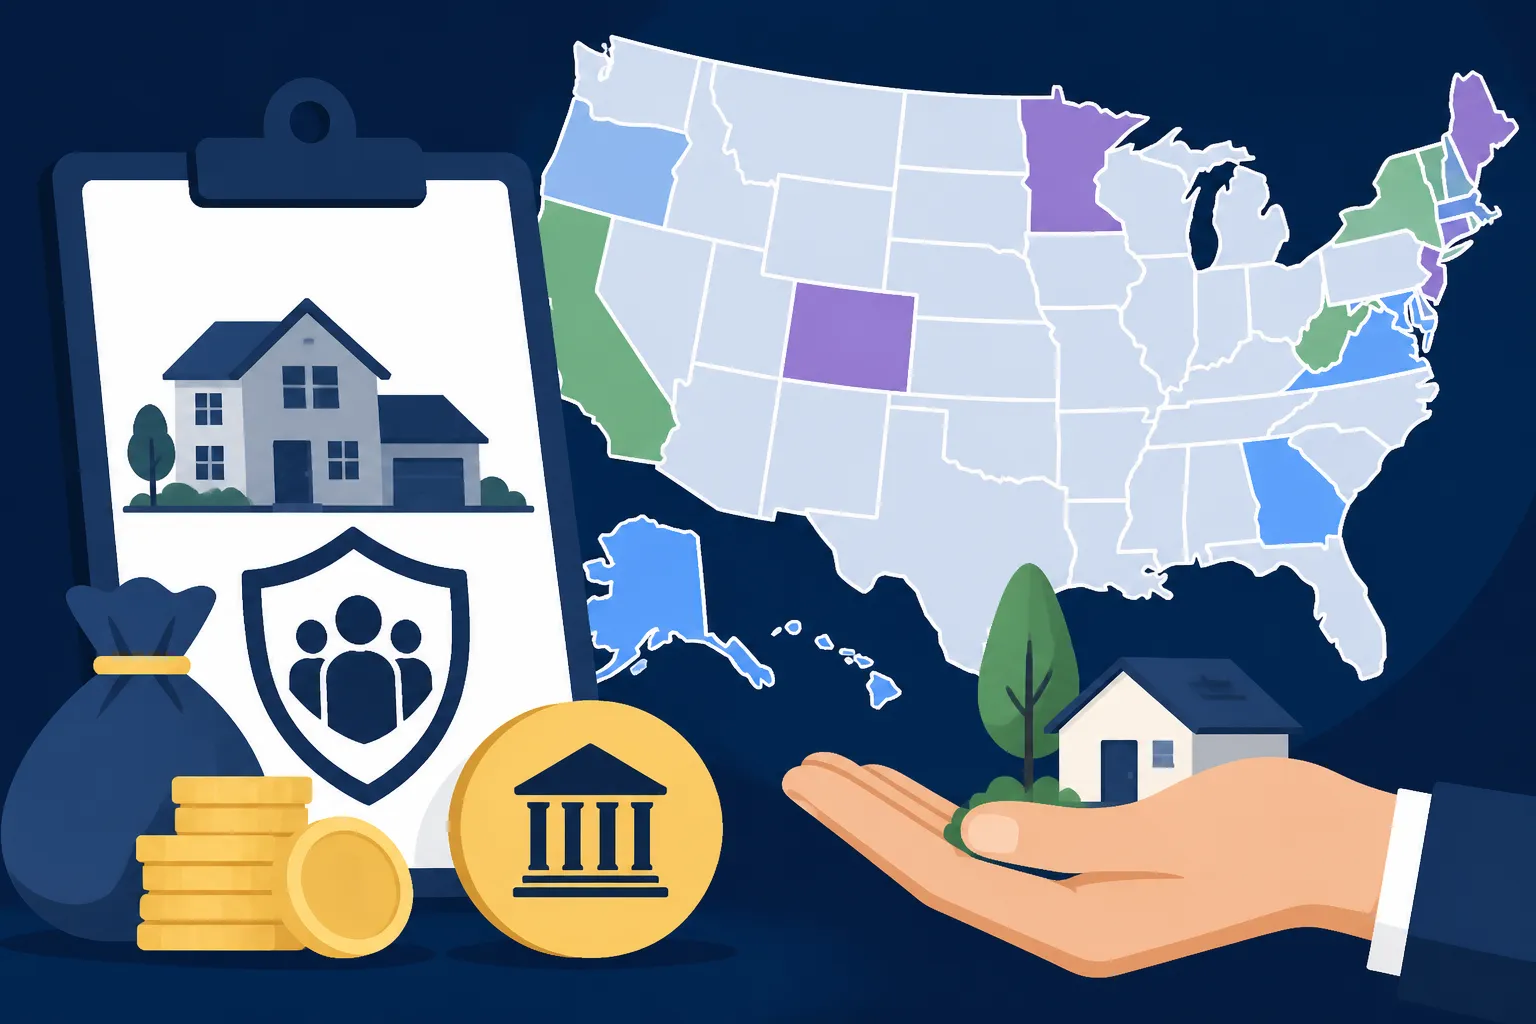
Currently, there are a handful of states that impose their own estate tax, in addition to the potential federal estate tax. These states are not uniform in their approach; each has its own exemption amount and rate structure. It’s not just about wealthy coastal states either; a mix of regions are represented. For individuals and families who live in or own property in these states, understanding the local rules is paramount.
As of late 2024, looking ahead to 2026, the states that are currently expected to have an estate tax include:
- Connecticut
- District of Columbia
- Hawaii
- Illinois
- Maine
- Maryland (which also has an inheritance tax, a rare combination)
- Massachusetts
- Minnesota
- New York
- Oregon
- Rhode Island
- Vermont
- Washington
It's crucial to remember that legislative changes can occur, and states might adjust their exemptions or even repeal their estate taxes, as Iowa recently did with its inheritance tax. However, for now, these are the jurisdictions where you'll need to pay close attention. Many other states have chosen to forego a state estate tax altogether. You can find a complete list of Which States Have an Estate Tax in 2026? for a clear overview.
Detailed Look at Key State Exemptions
The actual exemption amount is the number you need to know. It directly impacts whether your estate will owe state estate tax. While the federal exemption is indexed for inflation, some state exemptions are static, while others adjust annually. For 2026, here's a look at some of the key state estate tax exemptions:
- Connecticut: For 2026, Connecticut's estate tax exemption is expected to align with the federal exemption, which means it will likely be around $15 million. This is a significant change over the years, making it one of the most generous state exemptions.
- District of Columbia: The District of Columbia's estate tax exemption is $4,988,400 for decedents dying in 2026, continuing its trend of relatively high exemptions compared to many other taxing states.
- Hawaii: Hawaii's estate tax exemption is anticipated to be around $5.49 million for 2026, also reflecting a higher threshold that impacts fewer estates.
- Illinois: Illinois currently maintains an estate tax exemption of $4 million, and this is expected to hold for 2026. This means estates valued at more than $4 million will be subject to Illinois estate tax.
- Maine: Maine’s estate tax exemption is typically indexed for inflation and is $7,160,000 for 2026 deaths.
- Maryland: Maryland has an estate tax exemption that is currently set at $5 million and is expected to remain at this level for 2026. It's noteworthy because Maryland is also the only state that levies both an estate tax and an inheritance tax.
- Massachusetts: The Bay State's estate tax exemption is set at $2 million. This is a crucial number for many families in Massachusetts, as estates over this amount face a state estate tax, even if they're far below the federal threshold.
- Minnesota: Minnesota's estate tax exemption is fixed at $3 million, a figure that has been in place for several years and is expected to continue into 2026.
- New York: The New York estate tax exemption is a bit unique. For 2026, it is projected to be around $6.94 million and is indexed for inflation. However, New York also has what is known as the "New York Estate Tax Cliff Explained," which means if your estate exceeds the exemption by more than 5%, the entire estate (not just the excess) can become taxable. This "cliff" can be a devastating surprise for unwary families.
- Oregon: Oregon has one of the lowest estate tax exemptions at $1 million. This means a substantial number of estates, even those that might not be considered "wealthy" by federal standards, can be subject to Oregon’s estate tax.
- Rhode Island: Rhode Island's estate tax exemption is typically adjusted for inflation and is expected to be around $1,838,056 for 2026.
- Vermont: Vermont’s estate tax exemption is set at a flat $5 million.
- Washington: The Washington state estate tax exemption for 2026 is $3,076,000 for deaths between January 1 and June 30, and $3,000,000 for deaths on or after July 1.
Here’s a helpful table summarizing the anticipated state estate tax exemptions for 2026. Keep in mind these are projections, and legislative bodies can always make changes.
| State/Jurisdiction | Projected 2026 Estate Tax Exemption | Notes |
|---|---|---|
| Connecticut | $15,000,000 (matches federal) | Aligns with federal exemption. |
| District of Columbia | ~$4.9 Million | Subject to inflation adjustments. |
| Hawaii | ~$5.49 Million | Subject to inflation adjustments. |
| Illinois | $4 Million | Fixed exemption. |
| Maine | ~$6.8 Million | Subject to inflation adjustments. |
| Maryland | $5 Million | Also imposes an inheritance tax. |
| Massachusetts | $2 Million | Fixed exemption. |
| Minnesota | $3 Million | Fixed exemption. |
| New York | ~$6.94 Million | Subject to inflation adjustments, includes "estate tax cliff." |
| Oregon | $1 Million | Lowest exemption among taxing states. |
| Rhode Island | ~$1.80 Million | Subject to inflation adjustments. |
| Vermont | $5 Million | Fixed exemption. |
| Washington | ~$2.19 Million | Subject to inflation adjustments. |
These figures are projections for 2026 based on current law and expected inflation adjustments. Always verify the most current information with a qualified professional or official state tax resources.
This table makes it starkly clear why some individuals with relatively modest assets in states like Oregon or Massachusetts could find their estates facing a significant tax burden, while someone in Connecticut with a larger estate might not. It highlights the importance of understanding How State Estate Tax Works for your specific location.
Navigating Your Estate Plan with State Exemptions in Mind
Understanding the numbers is one thing, but knowing how they apply to your unique situation and what you can do about it is where smart planning comes into play. Many people get caught up in the federal tax conversation and overlook these state-specific hurdles, leading to unforeseen consequences for their heirs.
Identifying Your Domicile and Its Impact
One of the trickiest aspects of state estate tax is determining which state's rules apply to your estate. This largely comes down to your "domicile" at the time of your death. Your domicile isn't just where you own property, but where you consider your true, fixed, and permanent home, the place to which you intend to return whenever you are absent. For individuals who live in one state but own vacation homes or other significant assets in another, or those who frequently move, establishing clear domicile can be complex. For example, a "snowbird" who spends winters in Florida (a state with no estate tax) and summers in New York could inadvertently be deemed a New York resident if their primary ties (voter registration, driver's license, banking, doctors) are still there.
If your estate includes property in multiple states, especially if some of those states have an estate tax and others don't, it becomes even more critical to clarify your domicile. Generally, the estate tax of your state of domicile will apply to your entire estate, including out-of-state property. However, some states might also impose an estate tax on real property located within their borders, regardless of the deceased's domicile. This could lead to complex situations requiring careful navigation, and sometimes even multiple state estate tax filings. This is why it's so important to understand Estate Tax for Residents vs Nonresidents and ensure your legal and financial paperwork clearly supports your intended domicile.
Strategies to Potentially Reduce Your Taxable Estate
Even if you reside in a state with an estate tax and your estate is likely to exceed the exemption, there are legitimate and effective strategies to potentially reduce your taxable estate and minimize the tax burden on your heirs. These strategies often require careful planning and execution, usually with the help of an experienced estate planning attorney and financial advisor.
One common approach involves strategic gifting during your lifetime. By utilizing the annual gift tax exclusion (projected to be $19,000 per recipient in 2026), you can transfer significant wealth out of your estate tax-free over time. For example, a couple could gift $38,000 per year to each child and grandchild without impacting their lifetime exemption or incurring gift tax. Another powerful tool is establishing various types of trusts. An irrevocable trust, for instance, can remove assets from your taxable estate, effectively shielding them from estate taxes upon your death. While it means giving up some control over those assets, it can lead to substantial tax savings for your beneficiaries. If you're looking into ways to mitigate potential taxes, you might find valuable insights in articles such as How to Reduce or Avoid State Estate Tax or Does a Trust Avoid State Estate Tax?. Utilizing tools like those offered by SmartAsset can also help you find qualified financial advisors who specialize in estate planning in your area, connecting you with professionals who can guide you through these complex decisions.
The Ever-Changing Landscape of Estate Tax Laws
Estate tax laws, at both the federal and state levels, are not set in stone. They are subject to legislative changes, economic conditions, and even inflation adjustments, which can make long-term planning a moving target. Keeping an eye on these potential shifts is an ongoing part of responsible estate planning.
Why Exemptions Change and What to Watch For
State estate tax exemptions can change for several reasons. Economic conditions often play a role; states might increase exemptions during times of prosperity or, conversely, lower them or adjust rates to generate more revenue during tighter fiscal periods. Political ideologies also influence these laws, with different administrations pushing for higher or lower taxes on inherited wealth. Furthermore, many state exemptions, like the federal one, are "indexed for inflation." This means the exemption amount is automatically adjusted annually to account for rising costs of living, preventing more estates from being caught in the tax net simply due to inflation.
It's crucial for individuals to stay informed about potential changes in their state's estate tax laws. For example, some states have considered repealing their estate taxes entirely, while others have debated lowering their exemptions or increasing rates. These legislative discussions can directly impact your estate plan. Keeping up-to-date with current events and regularly reviewing your estate plan with a professional can help you adapt to these evolving circumstances. You can learn more about how these adjustments work by reading about How Estate Tax Exemptions Are Indexed for Inflation and Which States Are Repealing or Changing Estate Tax?.
Seeking Professional Guidance for Your Specific Situation
Given the intricate nature of state estate taxes, the varying exemptions, and the potential for legislative changes, it's virtually impossible for most individuals to navigate this landscape effectively without professional assistance. Trying to self-diagnose your estate tax exposure or implement complex planning strategies can lead to costly mistakes and unintended consequences.
A qualified estate planning attorney can help you understand your state's specific laws, determine your true domicile, and draft the necessary legal documents, such as wills, trusts, and powers of attorney, to align with your goals. A financial advisor, especially one with expertise in wealth management and tax planning, can help you evaluate your assets, project potential tax liabilities, and suggest strategies for wealth transfer. For higher net worth individuals, integrating the advice of both an attorney and a financial advisor is indispensable. Resources like SmartAsset can be incredibly useful in finding certified professionals in your area who specialize in estate planning, ensuring you get tailored advice that considers both federal and state-specific tax implications. Ultimately, investing in expert guidance now can save your heirs significant time, stress, and money down the line, ensuring your legacy is preserved as you intend. For comprehensive insights, consider looking into Estate Tax Planning for High Net Worth Families.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.