Generation-Skipping Transfer (GST) Tax Explained
Navigating the intricate world of estate planning can feel like deciphering a secret code, and few aspects are as complex and potentially costly as the generation-skipping transfer (GST) tax. For families looking to pass down wealth across multiple generations, this often-misunderstood tax can significantly reduce what their loved ones ultimately receive. This comprehensive guide will break down the GST tax, explain how it works, and explore strategies to help you plan effectively.
What Exactly Is the Generation-Skipping Transfer GST Tax?
Let's be real: the world of federal taxes can be a labyrinth, and the Generation-Skipping Transfer (GST) tax is one of its most bewildering corridors. At its core, the GST tax is an additional layer of tax designed to prevent wealthy families from sidestepping federal estate and gift taxes by transferring assets directly to grandchildren or other "skip persons," thereby skipping a generation of taxation. It’s an extra hurdle for those trying to leave a legacy, ensuring that the government gets its share at each generational transfer.
Defining a Generation-Skipping Transfer
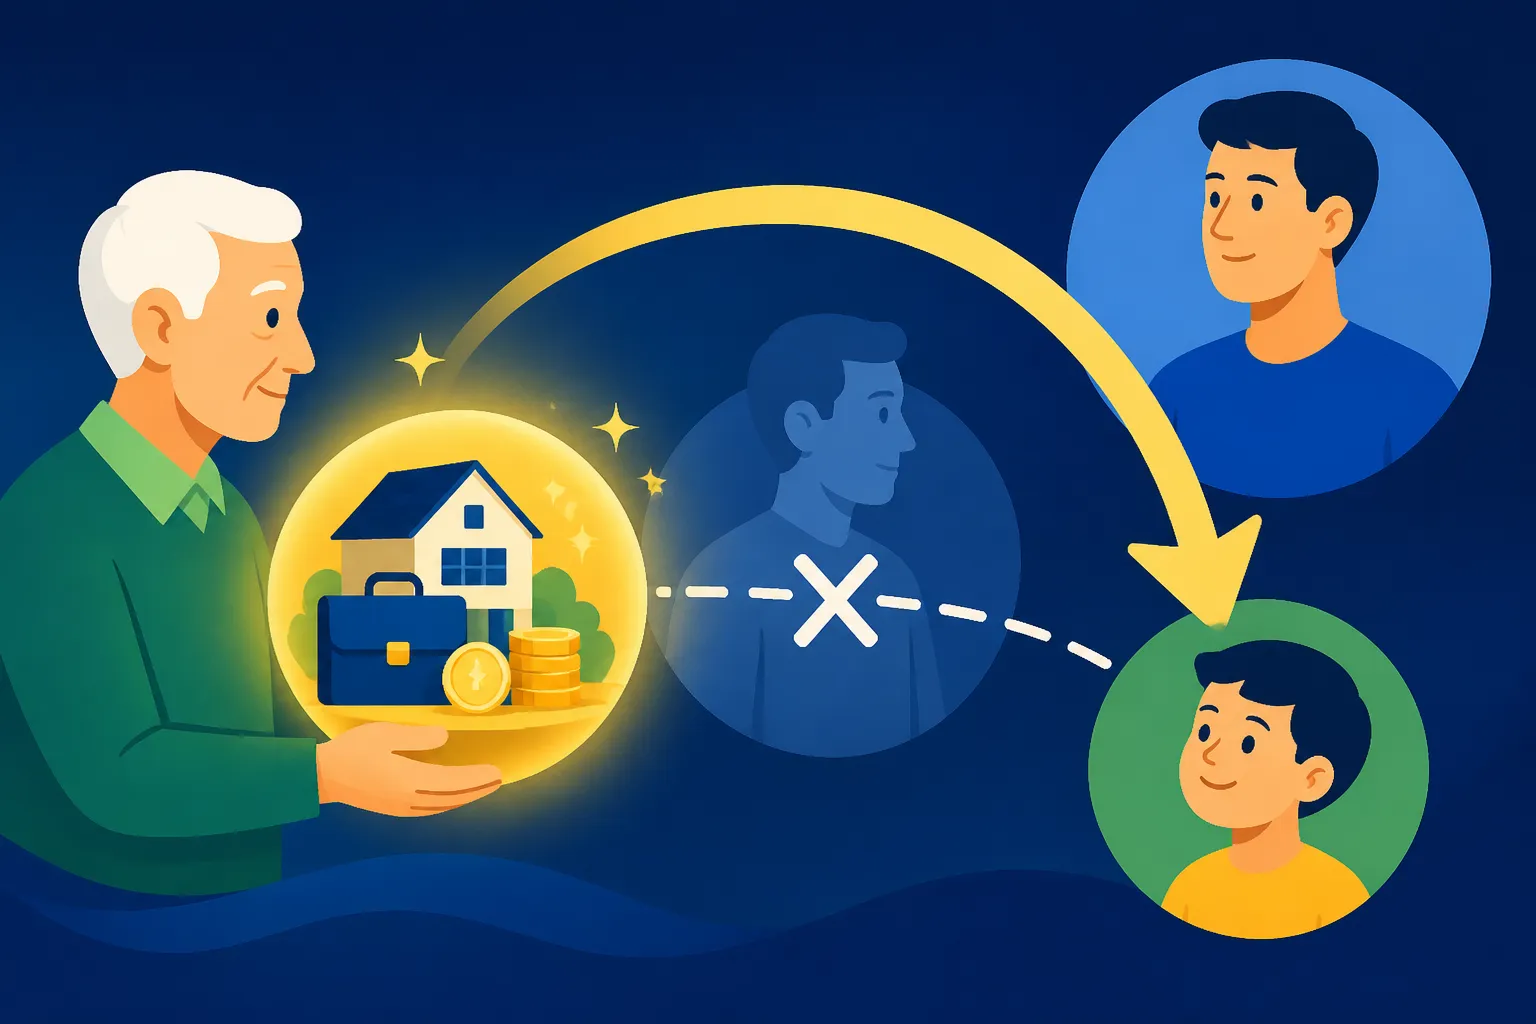
A generation-skipping transfer, in the eyes of the IRS, is any transfer of property (money, assets, etc.) to a "skip person." So, who exactly qualifies as a skip person? Generally, it's someone at least two generations younger than the transferor. This isn't just about blood relatives, either. If you transfer assets to a grandchild, a great-niece, or even an unrelated individual who is 37.5 years younger than you, they are considered a skip person. The "37.5 years younger" rule is a specific threshold the IRS uses to delineate generations for non-relatives, making sure that age, not just family ties, determines a skip person's status.
Consider a grandparent who wants to set up a trust for their beloved grandchild, or a generous aunt who wishes to leave a substantial inheritance to a niece or nephew who happens to be more than 37.5 years her junior. In both these scenarios, the beneficiary would typically be classified as a skip person, triggering the potential application of the GST tax. Understanding this definition is the first critical step because it dictates whether your planned transfer will even fall under the purview of this tax. Without this foundational knowledge, you might inadvertently expose your estate to a significant and avoidable tax liability.
The Purpose Behind the GST Tax
You might be thinking, "Why another tax? Don't we already have estate and gift taxes?" And you'd be right to ask! The GST tax didn't just appear out of nowhere; it was enacted to close a loophole in wealth transfer planning. Before its introduction, savvy estate planners could bypass an entire generation of estate tax by structuring gifts or bequests directly to grandchildren, rather than to their children. This effectively allowed the family to avoid one round of estate taxation. The government saw this as a significant erosion of the tax base.
So, the GST tax was implemented to level the playing field, ensuring that wealth transferred across generations faces a similar tax burden, regardless of whether it goes directly to a grandchild or passes through a child first. It acts as a backstop, complementing the federal estate tax and gift tax by imposing an additional tax at the highest federal estate tax rate on transfers that "skip" a generation. This "tax-on-a-tax" concept is precisely what makes the GST tax so potent and why careful planning is absolutely essential for anyone with significant assets hoping to benefit future generations. Without the GST tax, a family could theoretically keep wealth out of the taxable estates of successive generations for an extended period, significantly reducing the overall tax revenue to the government.
How Does the GST Tax Interact with Federal Estate and Gift Taxes?
The GST tax doesn't operate in a vacuum; it's intricately woven into the fabric of federal wealth transfer taxes. Many people assume if they've accounted for gift or estate taxes, they're in the clear. However, that's often not the case with generation-skipping transfers, which can incur multiple layers of taxation. This overlapping nature is precisely what makes it such a complex area of estate planning and a source of considerable frustration for families trying to understand their obligations.
Understanding the Unified Credit
Before we dive deeper into the GST tax's unique characteristics, it's crucial to grasp the concept of the unified credit. The federal tax system offers a single, generous exemption amount, often referred to as the "unified credit" or the Lifetime Gift & Estate Tax Exemption (Unified Credit), that applies to both gifts made during your lifetime and transfers made at your death. For 2026, this exemption is $15 million per individual, and it is scheduled to be adjusted for inflation starting in 2027. This means you can transfer assets up to this amount, whether through gifts or your estate, without incurring federal gift or estate tax.
However, here's where it gets tricky: while the unified credit shields you from gift and estate taxes up to a certain point, the GST tax operates with its own separate exemption. Although the amount is the same as the federal estate tax exemption, it's applied differently. This means that even if a transfer is fully exempt from gift tax or estate tax due to the unified credit, it could still potentially be subject to GST tax if it's considered a generation-skipping transfer and the specific GST exemption hasn't been properly allocated. It’s a subtle but critical distinction that often catches people off guard. For a deeper understanding of this general exemption, you might want to look into the Federal Estate Tax Exemption 2026 ($15 Million).
The "Tax-on-a-Tax" Impact
This brings us to the most daunting aspect of the GST tax: its potential to create a "tax-on-a-tax" scenario. Imagine you're a grandparent, and you decide to make a substantial gift directly to your grandchild. This gift could, theoretically, be subject to three different taxes: the federal gift tax, and if it's a generation-skipping transfer and your GST exemption isn't sufficient, then the GST tax. If the transfer also occurs at death through your will or trust, it could be subject to federal estate tax and GST tax. It's like paying tolls on the same highway multiple times!
Let's visualize this with a hypothetical example. Suppose you decide to gift $20 million directly to your grandchild in 2024. Your Annual Gift Tax Exclusion 2026 ($19,000) (for 2024, it's actually $18,000, for 2026 it's projected $19,000) will cover a small portion, but the remainder will consume part of your lifetime gift tax exemption. If you've already used up your gift tax exemption, then gift tax would apply. Crucially, because this is a direct gift to a skip person, it's also a generation-skipping transfer. If your GST exemption doesn't cover the full amount of the gift, the excess will be subject to the GST tax, currently at a flat 40%. This means a significant chunk of your intended legacy could be diverted to taxes, dramatically reducing the net amount your grandchild receives. This simultaneous application of taxes highlights why proactive and expert planning is paramount to minimize the burden on your heirs.
The Generation-Skipping Transfer Tax Exemption
Just like with the federal estate and gift taxes, there's an exemption amount for the Generation-Skipping Transfer tax that allows you to transfer a certain amount of wealth to skip persons without incurring the GST tax. This exemption is a critical tool in high-net-worth estate planning, and understanding how to effectively use it is key to preserving your family's legacy. However, just having the exemption isn't enough; knowing how to properly allocate it is where the real strategy comes into play.
Current Exemption Amounts and Indexing for Inflation
For 2024, the federal GST tax exemption is $13.61 million per individual. It's important to note that this exemption amount is linked directly to the federal estate and gift tax exemption. This means that as the estate tax exemption increases each year due to inflation adjustments, so too does the GST tax exemption. For instance, projections for 2026 anticipate the exemption to be even higher, potentially around $15 million, before a significant legislative change is expected. This annual adjustment is a double-edged sword: it offers a bit more flexibility each year, but it also means you need to stay current with the figures to ensure your planning is accurate.
This exemption is incredibly powerful because it allows individuals to transfer substantial wealth to beneficiaries who are two or more generations below them without triggering the additional 40% GST tax. Without this exemption, nearly any transfer to a grandchild or younger descendant could be subject to this onerous tax, drastically reducing the effective inheritance. This makes the GST exemption a cornerstone of multi-generational wealth transfer strategies, allowing families to plan for the long-term financial security of their lineage while minimizing tax leakage. It's a significant figure, and maximizing its use is a primary goal for many families engaged in sophisticated estate planning.
How the Exemption Is Allocated
Simply having an exemption isn't enough; you must also understand how it's allocated. The GST exemption can be allocated in a few ways. For outright direct skips (like a cash gift directly to a grandchild), the exemption is often automatically allocated, meaning you don't typically need to do anything specific. However, for more complex transfers, especially those involving trusts, manual allocation might be necessary and highly beneficial. You can make an elective allocation of your GST exemption to property transferred into a trust that benefits skip persons, even if it's not a direct skip initially. This is crucial for "dynasty trusts" or "generation-skipping trusts," which are designed to benefit multiple generations.
The decision of how and when to allocate your GST exemption can have massive implications. If you don't allocate it correctly or in a timely manner, you could miss out on its benefits, leaving assets exposed to the 40% GST tax down the line. For example, if you establish a trust for your grandchildren and fail to allocate your GST exemption to it, any distributions from that trust to your grandchildren could be subject to the GST tax, even if the initial transfer to the trust was not. This is why working with an experienced estate planning attorney or financial advisor is so important; they can help ensure your exemption is strategically allocated to achieve your long-term wealth transfer goals. They can also help clarify when you might need to file Form 709: The Gift Tax Return Explained for certain allocations.
The Generation-Skipping Transfer Tax Rate
When dealing with the GST tax, it's not just about if you'll pay it, but how much. Unlike income tax brackets or even state-level inheritance taxes that might have varying rates based on relationship, the federal GST tax is remarkably straightforward in its rate structure—though no less impactful. Understanding this rate and how it's applied is crucial for accurately forecasting the tax burden on generation-skskipping transfers.
Understanding the Flat Rate
Here's the kicker: the federal GST tax rate is a flat 40%. Yes, you read that right—forty percent. This isn't a progressive rate that increases with the amount transferred; it's a fixed rate applied to any portion of a generation-skipping transfer that exceeds your available GST exemption. This flat rate is currently equal to the highest federal estate tax rate, reinforcing its purpose as a backstop against multi-generational tax avoidance. This means that once a transfer falls outside the exemption, it's hit hard.
To put this into perspective, consider a scenario where, after utilizing all available exemptions, you have an additional $1 million subject to GST tax. That's $400,000 directly to the government, reducing the intended inheritance by a substantial margin. This high, flat rate makes comprehensive planning absolutely indispensable for anyone contemplating significant transfers to skip persons. The predictability of the rate, while steep, at least allows for precise calculations and strategic allocation of exemptions to minimize its impact. It underscores why simply being aware of the GST tax isn't enough; proactive measures to avoid or mitigate it are essential.
Calculating the Inclusion Ratio
The flat 40% rate is applied using something called the "inclusion ratio." This ratio determines what percentage of a trust or transfer is subject to the GST tax. Essentially, if you allocate enough of your GST exemption to a transfer, you can reduce its inclusion ratio to zero, meaning that transfer (and any future distributions from a trust, if applicable) will be entirely exempt from GST tax. If you don't allocate enough, the inclusion ratio will be greater than zero, and that percentage of the transfer will be subject to the 40% GST tax.
Here’s a simplified way to think about it: the inclusion ratio is calculated as 1 minus the "applicable fraction." The applicable fraction's numerator is the amount of GST exemption allocated to the transfer, and the denominator is the value of the property transferred (minus any death taxes and charitable deductions). So, if you allocate $1 million of your GST exemption to a $1 million transfer, your applicable fraction is 1 ($1M/$1M), and your inclusion ratio is 0 (1-1). This means none of that transfer is subject to GST tax. If you only allocate $500,000 to that $1 million transfer, your applicable fraction is 0.5 ($500k/$1M), and your inclusion ratio is 0.5 (1-0.5). In this case, 50% of any distributions from that trust or transfer would be subject to the 40% GST tax. This complex calculation highlights the absolute necessity of precise exemption allocation to achieve a zero inclusion ratio for protected assets. Financial advisors often use sophisticated software to model these calculations, demonstrating the value of professional guidance in navigating these intricate rules.
Types of Generation-Skipping Transfers
The GST tax isn't just one blanket rule; it applies to different types of transfers, each with its own nuances regarding when the tax is triggered and who is responsible for paying it. Understanding these distinctions is crucial for identifying potential GST tax liabilities in your estate plan. It's not always as simple as a direct gift; transfers can take various forms, and the IRS has rules for each.
Direct Skips
A "direct skip" is perhaps the most straightforward type of generation-skipping transfer. This occurs when an interest in property is transferred directly to a skip person, and the transfer itself is subject to either gift tax or estate tax. Think of it as skipping the middle generation entirely. A common example would be a grandparent making an outright gift of cash or stock to a grandchild, or leaving a specific bequest to a grandchild in their will. In these scenarios, the transfer goes straight from the transferor to the skip person.
The significant characteristic of a direct skip is that the GST tax is generally imposed at the time of the transfer. If it's a lifetime gift, the donor (the person making the gift) is usually responsible for paying both the gift tax and the GST tax. If it's a bequest at death, the estate is typically responsible for both the estate tax and the GST tax. While the Annual Gift Tax Exclusion 2026 ($19,000) can shield small outright gifts to skip persons from both gift tax and GST tax, larger direct skips quickly consume the GST exemption. It's crucial to distinguish these immediate transfers from more complex trust arrangements, as the timing and responsibility for the tax differ significantly.
Taxable Terminations
Things get a bit more convoluted when trusts are involved, leading to "taxable terminations." A taxable termination occurs when an interest in property held in a trust terminates, and immediately after that termination, all interests in the trust are held by skip persons. This often happens when a non-skip person beneficiary's interest in a trust ends, and the assets then pass to a skip person. A classic example is a trust established by a grandparent for their child, with the provision that upon the child's death, the remaining trust assets will pass to the grandchild.
In this scenario, when the child dies, their interest in the trust terminates. If the grandchild then becomes the sole beneficiary or the trust terminates and distributes to the grandchild, this is a taxable termination. The GST tax is imposed at the time of the termination, and generally, the trustee of the trust is responsible for paying the tax from the trust assets. This can significantly reduce the amount that ultimately flows to the grandchildren. Such arrangements are common in multi-generational planning and require careful upfront allocation of the GST exemption to prevent substantial future tax liabilities.
Taxable Distributions
The third type of generation-skipping transfer is a "taxable distribution." This refers to any distribution of income or principal from a trust to a skip person, as long as it's not a direct skip or a taxable termination. Unlike direct skips, which are usually one-time events, taxable distributions can occur regularly over time, making them a continuous concern for trusts that benefit skip persons.
Imagine a trust set up for both your child and your grandchild, where the trustee has the discretion to distribute income to either. If the trustee decides to make a distribution of income or principal directly to the grandchild, that distribution would be a taxable distribution. The key difference here is who pays the tax: for taxable distributions, the skip person (the recipient of the distribution) is generally responsible for paying the GST tax. This means the beneficiary receives a net amount after the tax has been levied, which can come as an unwelcome surprise if they haven't been properly informed or planned for it. This emphasizes the need for trustees and beneficiaries to be well-versed in the trust's tax implications and for comprehensive planning when setting up such flexible trusts.
Strategies to Mitigate or Avoid the GST Tax
The good news is that while the GST tax can be daunting, there are well-established strategies to mitigate or even avoid its impact. This isn't about dodging your responsibilities, but rather about smart, legal planning that leverages the tools and exemptions provided by the tax code. Proactive planning is paramount, especially given the significant rate at which the GST tax is applied.
Maximizing the GST Exemption
The most direct and powerful strategy to combat the GST tax is to fully utilize your GST exemption. As we discussed, this exemption (currently $13.61 million per individual in 2024, likely higher for 2026) allows you to transfer a substantial amount of wealth to skip persons without incurring the tax. For married couples, this means a combined exemption of over $27 million, offering immense potential for multi-generational wealth transfer. However, merely having the exemption isn't enough; it must be allocated effectively.
For transfers into trusts that benefit skip persons, especially those designed to last for multiple generations (often called "dynasty trusts"), ensuring proper and timely allocation of your GST exemption is absolutely critical. Failing to allocate the exemption can lead to every dollar distributed from that trust to a skip person being subject to the 40% GST tax, potentially decades down the line. Estate planners often advise allocating the exemption to the value of the assets when they are transferred into the trust, which locks in the exemption amount and allows any future appreciation of those assets to also be GST-exempt. This strategy, when executed correctly, can create a powerful shield for your family's future wealth. If you're looking for Estate Tax Planning for High Net Worth Families, understanding this exemption is foundational.
Using Trusts for Multi-Generational Planning
Trusts are perhaps the most versatile tools in the estate planning arsenal for dealing with the GST tax. Specifically, a "generation-skipping trust" or "dynasty trust" can be structured to hold assets for the benefit of multiple generations while leveraging the GST exemption. By allocating your GST exemption to these trusts upon funding, you can create a pool of assets that grows free of GST tax for the entire duration of the trust, which in some states can be for hundreds of years. This allows wealth to pass from generation to generation without incurring estate tax at each level, and without the GST tax if properly managed.
For example, an Irrevocable Life Insurance Trust (ILIT) can be structured as a generation-skipping trust. The death benefit from a life insurance policy, if structured correctly within an ILIT, can pass to grandchildren or other skip persons completely free of estate tax, and if the GST exemption is allocated to the contributions to the trust, it can also be free of GST tax. This requires careful drafting and ongoing administration, but the long-term tax savings can be immense. It's vital to seek expert advice from estate attorneys and financial planners who specialize in these areas. Many financial professionals, often collaborating with resources like SmartAsset, can help you understand these complex structures and how they fit into your overall financial picture. Understanding Types of Trusts Explained (ILIT, GRAT, QTIP & More) is an excellent starting point for exploring these options.
Leveraging Annual Gift Tax Exclusions
While the main GST exemption handles large transfers, don't overlook the power of the Annual Gift Tax Exclusion 2026 ($19,000). For 2024, this amount is $18,000, allowing you to gift up to that amount per person, per year, without needing to file a gift tax return or consume any of your lifetime gift tax exemption. When making outright direct skips to skip persons (like a cash gift directly to a grandchild), the annual exclusion can also apply to shield these gifts from the GST tax.
This means you could, for example, give each grandchild $18,000 this year and it would be free of both gift tax and GST tax, without touching your larger lifetime exemptions. For a family with multiple grandchildren, this can add up to significant tax-free wealth transfer over time. However, a word of caution: when gifting to a trust that benefits skip persons, the annual exclusion only applies for GST tax purposes under very specific conditions (e.g., if the trust principal would be included in the skip person's estate if they die before the trust terminates, and all distributions during their life can only go to them). For most trusts, especially dynasty trusts, gifts will consume the GST exemption even if they fall within the annual gift tax exclusion. Always consult with an estate planning professional to ensure you're maximizing this strategy correctly for your specific trust structures.
The Future of the GST Tax and Planning Considerations
The landscape of estate tax law is rarely static, and the Generation-Skipping Transfer tax is no exception. With significant legislative changes on the horizon, understanding future implications is just as important as knowing current rules. This forward-looking perspective is crucial for crafting an estate plan that remains resilient against anticipated shifts in tax policy.
The 2026 Sunset and Its Implications
The "sunset" that was scheduled for January 1, 2026 did not take place. For 2026, the GST tax exemption and the federal estate and gift tax basic exclusion amount are each $15 million per individual, and the amount is scheduled to be adjusted for inflation starting in 2027.
Because the $15 million exemption is now set by law and no longer faces a scheduled cut, there is no sunset deadline driving large lifetime gifts or the funding of generation-skipping trusts. Families can still review their strategies with an advisor, but without that deadline. You can learn more about this by reading OBBBA & the End of the 2026 Estate Tax Sunset.
Importance of Professional Guidance
Let's be honest, navigating the intricacies of the GST tax, its exemptions, allocation rules, and the looming legislative changes is not a DIY project. The potential for costly errors is simply too high. This is precisely why seeking professional guidance from experienced estate planning attorneys, certified public accountants (CPAs), and financial advisors is not just recommended, but essential. These professionals possess the in-depth knowledge and experience to understand the nuances of your unique financial situation and tailor a strategy that aligns with your specific goals.
A qualified estate planning attorney can help you draft the necessary trust documents, ensure proper GST exemption allocation, and advise on the most tax-efficient ways to transfer wealth across generations. A CPA can provide critical insights into the tax implications of various planning strategies, including complex calculations involving the inclusion ratio. Financial advisors, like those partnering with services such as SmartAsset, can help integrate your GST tax planning into your broader financial plan, ensuring liquidity and asset management are also considered. Their collective expertise can help you avoid pitfalls, maximize your exemptions, and ultimately ensure that your legacy is preserved as you intend, rather than being diminished by unforeseen tax burdens. This collaborative approach can save your heirs millions in potential taxes and provide invaluable peace of mind.
Comparing Generation-Skipping Transfer Types
To help clarify the differences between the various types of generation-skipping transfers, here's a handy table outlining their key characteristics:
| Feature | Direct Skip | Taxable Termination | Taxable Distribution |
|---|---|---|---|
| Definition | Transfer directly to a skip person; subject to gift or estate tax. | Interest in a trust ends; all interests in trust then held by skip persons. | Distribution of income/principal from a trust to a skip person (not a direct skip or taxable termination). |
| Example | Grandparent gifts cash directly to grandchild. | Trust pays income to child for life, then principal goes to grandchild. | Trustee distributes income from a trust to a grandchild. |
| When Taxed | At the time of the transfer. | At the time the non-skip person's interest terminates. | At the time of the distribution. |
| Who Pays Tax | Transferor (donor for gifts, estate for bequests). | Trustee (from trust assets). | Skip Person (recipient of the distribution). |
| Annual Excl. | Applies to outright gifts to skip persons. | Generally does not apply. | Generally does not apply. |
| GST Exemption | Consumes GST exemption if not covered by annual exclusion. | Consumes GST exemption if not covered by prior allocation. | Consumes GST exemption if not covered by prior allocation. |
Disclaimer
Please note that this article provides general information and is not intended as legal, tax, or financial advice. Estate tax laws, including those pertaining to the Generation-Skipping Transfer tax, are complex and subject to change. You should consult with a qualified estate planning attorney, financial advisor, or tax professional to discuss your specific situation and make informed decisions.