How to Avoid the New York Estate Tax Cliff
Most people assume that if they are slightly over a tax limit, they only pay tax on the extra amount. In New York, that assumption can cost your family hundreds of thousands of dollars. The New York estate tax cliff is a unique, punishing calculation that wipes out your entire exemption if your estate is even 5.1% over the limit. This guide breaks down exactly how to avoid this financial trap through strategic gifting, trusts, and residency planning.
Understanding the New York Estate Tax Cliff Logic
New York is one of the few states that doesn’t just tax the "excess" over an exemption. Instead, it utilizes a "cliff" mechanism. Most states work like a staircase: you climb a step, and you pay a little more. New York’s system is more like a trapdoor. If you are under the threshold, you pay zero. If you are just a few dollars over the threshold, the floor drops out, and you are taxed on the very first dollar of your estate. It is one of the most aggressive state-level tax policies in the country, and for families caught in the middle, it feels less like a tax and more like a penalty for being successful.
How the 105 Percent Rule Works
The magic number in New York estate planning is 105%. As of 2026, the New York estate tax exemption is expected to be indexed for inflation, but let’s look at the mechanics that stay the same regardless of the specific dollar amount. If your total taxable estate is 100% or less of the exemption, you owe nothing. If your estate falls between 100% and 105% of the exemption, the state gradually phases out the credit. However, the moment your estate hits 105.01% of the exemption, the exemption vanishes entirely.
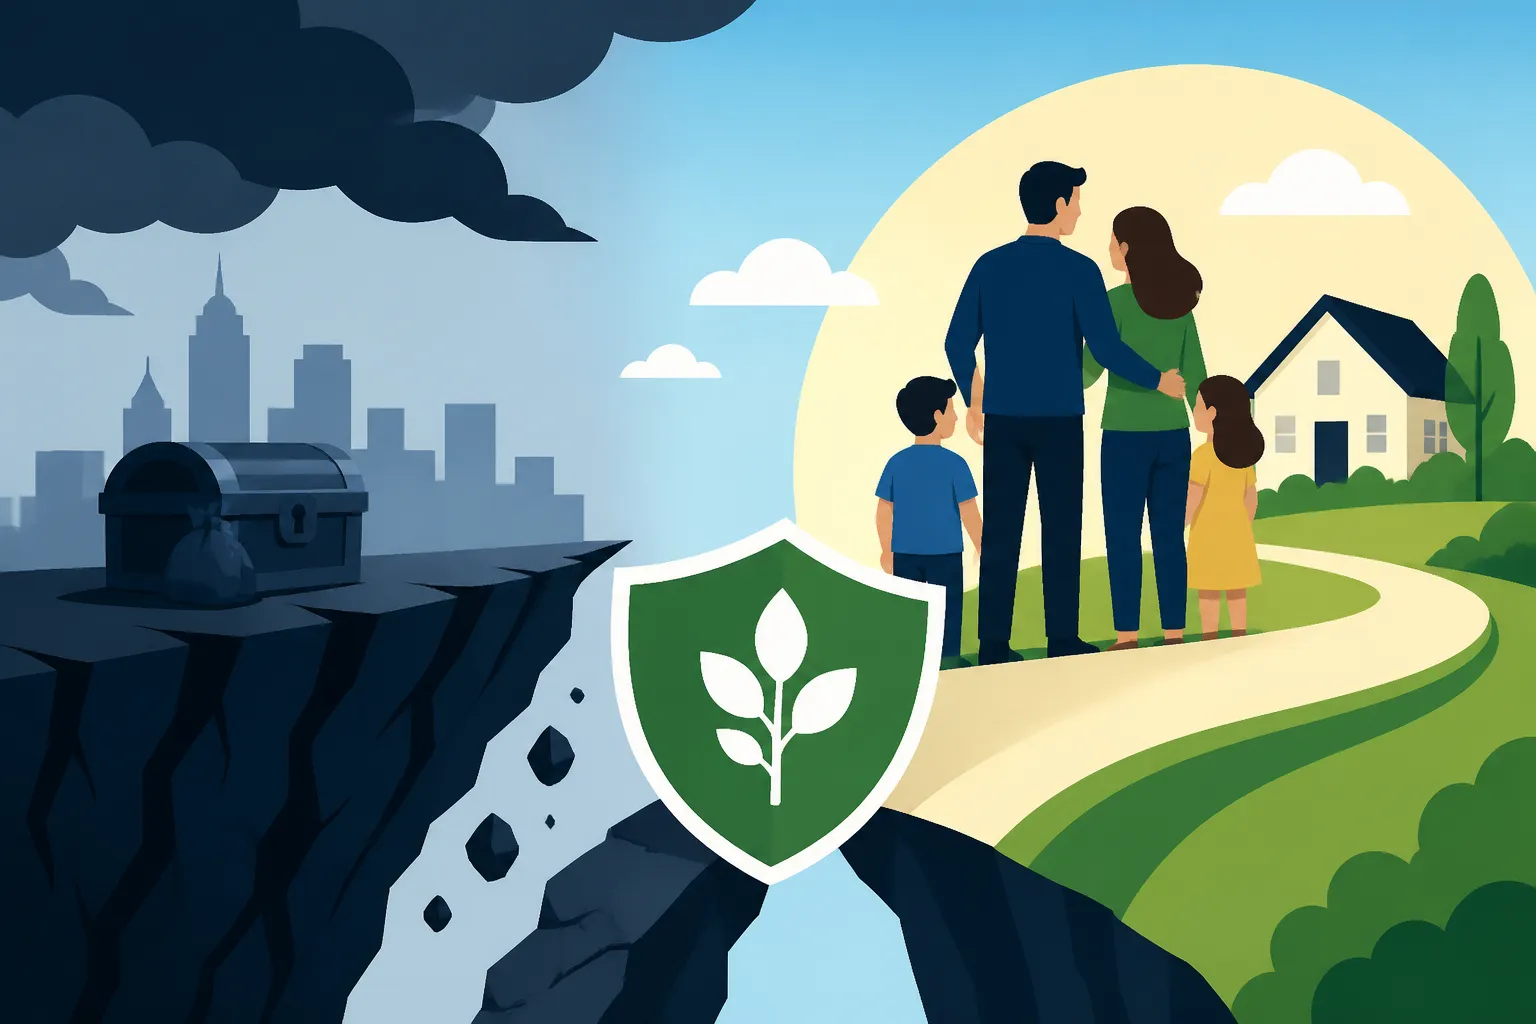
Imagine you are standing at the edge of a literal cliff. If the exemption is $7 million, and your estate is $7.35 million (which is 105% of $7 million), you are safe on the plateau. But if your estate is $7.4 million, you fall off. Instead of being taxed on the $400,000 that exceeded the limit, New York taxes you on the full $7.4 million. This is why The Estate Tax Cliff Explained (New York & More) is such a vital topic for anyone living in the Empire State. The difference in tax liability between an estate at $7 million and one at $7.5 million isn't just a few thousand dollars—it can be upwards of $500,000.
The Math Behind the Disaster
To see how brutal this is, let’s look at a realistic scenario. Suppose a retired couple in Westchester has a home worth $2 million, a retirement portfolio of $4 million, and life insurance policies totaling $1.5 million. Their total estate is $7.5 million. If the New York exemption is $7 million, they are roughly 7% over the limit. Because they exceeded the 105% threshold, New York will calculate the tax on the entire $7.5 million using graduated rates that start at 3.06% and climb to 16%.
Without careful planning, this family might pay over $700,000 in state taxes. If they had simply reduced their estate by $500,001 before death—perhaps by giving it to charity or their children—the tax bill would have been zero. This is a 100% tax rate on that "excess" money. It is a mathematical anomaly that catches many families off guard because they are focused on the Federal Estate Tax Exemption 2026 ($15 Million), which is much higher. They assume that because they don't owe the IRS, they don't owe Albany. That is a very expensive mistake.
Why New York Uses a Cliff
From a policy perspective, the cliff is designed to ensure that the state captures significant revenue from truly wealthy estates while exempting the middle class. However, the "middle" has shifted. With New York City real estate prices skyrocketing, a brownstone in Brooklyn and a decent 401(k) can easily push a family into "cliff territory." The state has resisted changing this structure because it provides a massive influx of revenue from estates that are just slightly wealthy. It places the burden on the taxpayer to engage in sophisticated planning to avoid the drop. Using tools like a SmartAsset estate tax calculator can help you visualize just how quickly these rates escalate once you cross that 105% line.
Calculating Your Exposure What Counts Toward the New York Estate Tax
Before you can avoid the cliff, you have to know how close you are to the edge. New York’s definition of what constitutes a "taxable estate" is broad. It isn't just the cash in your bank account or the stocks in your brokerage. It includes almost everything you have an "incident of ownership" in. Many people are surprised to find that assets they can't even touch during their lifetime are included in the final tally.
The Definition of the Gross Estate
When the state looks at your finances, they start with your "Gross Estate." This includes all real estate, tangible personal property (like art, jewelry, and cars), and intangible assets like stocks, bonds, and business interests. Even if you have a joint bank account with a child, New York may assume 100% of that account belongs to you unless the child can prove they contributed the funds.
It’s also important to understand What Is the Gross Estate? in the context of debt. Your taxable estate is the gross estate minus allowable deductions, such as mortgages, funeral expenses, and administrative costs of the estate. However, even with these deductions, the valuations are often higher than people expect because they are based on the fair market value at the date of death, not what you originally paid for the assets.
Real Estate and Out of State Property
New York residents are taxed on all their property, regardless of where it is located, with one major exception: real estate and tangible property located outside of New York. However, this is a double-edged sword. While New York can't directly tax your condo in Florida, they include the value of that condo in the calculation to determine your tax rate and whether you have hit the cliff.
If you own a home in New York and a vacation property in another state, you need to look at Estate Tax on Out-of-State Property to see how the two interact. Often, the out-of-state property pushes the total estate value over the cliff threshold, and then New York applies a pro-rata tax to the New York assets. This means that even if you don't live in New York full-time, your property there could be subject to heavy taxation if your global assets are significant.
The Role of Life Insurance
This is the "gotcha" that pushes most families over the cliff. Most people think of life insurance as a tax-free windfall for their beneficiaries. While it is generally free of income tax, it is very much included in your taxable estate for estate tax purposes if you owned the policy. If you have a $2 million term life policy to protect your family, that $2 million is added to your real estate and savings when New York checks to see if you’ve hit the cliff.
To combat this, many planners use an Irrevocable Life Insurance Trust (ILIT). By having the trust own the policy, the payout is removed from your estate, potentially moving you back under the cliff. You can find more details on this strategy in our guide on Does Life Insurance Count Toward Estate Tax? and how to structure ownership to keep that liquidity available for your family without handing a large chunk of it to the state.
Strategies to Step Down from the Cliff
If you find yourself standing at $7.5 million when the limit is $7 million, your goal is simple: get rid of $500,001. You don't necessarily have to spend it all on luxury cruises (though you could). There are legal, strategic ways to reduce your taxable estate so that your family keeps more of what you’ve built.
The Three Year Gift Add Back Rule
New York is one of the few states that does not have a standalone gift tax, but they have a "proxy" rule to prevent people from giving away their money on their deathbed to avoid the estate tax. Any taxable gifts made within three years of your death are "added back" into your estate for the purposes of calculating the New York estate tax.
If you are healthy and planning ahead, gifting is the most effective way to lower your estate. If you give away $1 million today and live for three years and one day, that money is gone from your New York estate forever. However, if you die two years later, New York treats that $1 million as if it were still in your pocket. This makes early planning essential. You can learn more about these timelines in Does Gifting Reduce State Estate Tax? to see how to time your transfers.
Strategic Charitable Giving The Santa Claus Strategy
One of the most effective ways to avoid the New York cliff is through a specific provision in a will or trust often called a "Santa Claus" clause. This provision states that if the estate is slightly over the cliff, the executor is authorized to give the "excess" amount (the portion over the exemption) to a designated charity.
Think about the math: If you are $100,000 over the cliff, you might owe $500,000 in tax. By giving that $100,000 to a charity, you bring the estate back under the exemption, and the $500,000 tax bill disappears. Your heirs lose $100,000 (which goes to charity), but they save $500,000 (which would have gone to the government). It is a rare win-win situation where being charitable actually saves your family money.
Marital Deduction and Portability Issues
New York handles married couples differently than the federal government. At the federal level, if one spouse dies and doesn't use their full exemption, the surviving spouse can "inherit" the remaining exemption—this is called portability. New York does not allow portability. This is a massive trap for couples.
If a husband dies and leaves everything to his wife, there is no tax because of the unlimited marital deduction. However, the husband’s $7 million New York exemption is wasted. When the wife later dies, she only has her own $7 million exemption. If the total estate is $10 million, she will fall off the cliff. To avoid this, couples often use "Bypass Trusts" to capture the first spouse's exemption. You can read a deep dive on this in Estate Tax Portability and Why Most States Don't Offer It.
Using Trusts to Mitigate NY Estate Tax
Trusts are not just for the ultra-wealthy; in New York, they are a survival tool for anyone near the cliff. By moving assets into specific types of trusts, you can "freeze" the value of your estate or remove assets from the state's reach entirely.
Credit Shelter Trusts Bypass Trusts
A Credit Shelter Trust is the classic solution to the lack of portability in New York. Instead of the first spouse leaving everything to the survivor, they leave an amount equal to the New York exemption to a trust. The surviving spouse can still benefit from the trust's income and even the principal for certain needs, but the assets are technically not "theirs."
When the surviving spouse dies, the assets in the Credit Shelter Trust pass to the children tax-free, and they are not included in the surviving spouse's estate calculation. This allows a couple to pass double the exemption amount without ever hitting the cliff. This is a foundational element of How to Avoid the New York Estate Tax Cliff for married New Yorkers.
Qualified Terminable Interest Property QTIP Trusts
For families with more complex needs—such as second marriages or a desire to control where assets go after the second spouse dies—a QTIP trust can be used. New York allows for a "state-only QTIP election." This is a sophisticated move where you treat a trust as qualifying for the marital deduction at the federal level but not at the state level (or vice-versa).
This allows executors to fine-tune the estate value after death to ensure the estate stays exactly $1 under the cliff. Using SmartAsset for real-time projections of these trust impacts can help families decide which election makes the most sense given the current year's exemption rates.
| Estate Value | NY Estate Tax (Estimated) | Effective Tax Rate |
|---|---|---|
| $6,900,000 | $0 | 0% |
| $7,200,000 | $185,000 | 2.5% |
| $7,400,000 | $680,000 | 9.2% |
| $8,000,000 | $780,000 | 9.7% |
| $10,000,000 | $1,080,000 | 10.8% |
Note: Estimates based on current graduated rates and a hypothetical $6.94M exemption. Small increases in value lead to massive jumps in tax due to the cliff.
The Residency Debate Moving Out of New York
For some, the best way to avoid the New York estate tax cliff is to simply not be a New Yorker when they die. This sounds simple, but New York is famous for being one of the most aggressive states in the country when it comes to "residency audits." They do not let taxpayers go easily, especially those with high net worths.
Establishing Domicile in No Tax States
To stop being a New York resident for tax purposes, you have to prove that you have changed your "domicile." Domicile is the place you intend to be your permanent home. It isn't enough to just buy a house in Florida and spend 183 days there. New York looks at "primary factors" like the size of your homes, where your "near and dear" items (photos, pets, heirlooms) are located, and where you spend your time.
If you are considering this move, you should look into States With No Estate Tax (2027) to see which destination offers the best protection. Moving your domicile effectively removes your intangible assets (stocks and bonds) from New York’s reach, though any New York real estate you keep will still be subject to the pro-rata tax rules mentioned earlier.
The Snowbird Challenge
Many New Yorkers try to balance two lives, spending winters in the south and summers in the Hamptons or the Hudson Valley. If you maintain a "permanent place of abode" in New York and spend more than 183 days in the state, you are considered a statutory resident. This means all your income is taxed by New York, and your estate planning becomes much more complicated.
For snowbirds, the cliff is a constant shadow. If you are caught in a residency audit after death, the state could claim millions in taxes that your family thought were avoided. It is vital to track your days meticulously and ensure your life is centered in your new state. You can find more about the risks of dual-residency in Estate Tax for Snowbirds With Two Homes.
Why Early Planning is Non Negotiable
The New York estate tax cliff is not a problem you can solve on your deathbed. Because of the three-year gift add-back rule and the complexities of setting up bypass trusts, you need a lead time of at least several years to be fully protected.
The stress of the cliff comes from the "all-or-nothing" nature of the math. Being $10,000 over can cost you $500,000. That is an irrational result that requires rational, cold-blooded planning to defeat. Whether it is through a How to Lower Your Taxable Estate strategy or a complex trust arrangement, the goal is to give yourself a "margin of safety" so that market fluctuations in your portfolio don't accidentally push you over the edge at the wrong time.
The Impact of the 2026 Sunset
It is also important to remember the federal landscape. The Federal Estate Tax Exemption 2026 ($15 Million) is $15,000,000 for people who die in 2026, and it is scheduled to be indexed for inflation starting in 2027. While this doesn't directly change New York's cliff, it changes how your state and federal taxes "stack."
Some people with very large estates will owe both state and federal estate taxes, making the strategies discussed here even more critical. You should review State vs Federal Estate Tax: How They Stack to understand how these two different tax systems interact. A strategy that saves you money in Albany shouldn't cost you more at the IRS.
New York Estate Tax Disclaimer
This guide is provided for informational and educational purposes only and does not constitute legal, financial, or tax advice. The New York estate tax code is notoriously complex and subject to frequent legislative changes and inflation adjustments. The "cliff" calculation and the three-year gift add-back rule involve intricate legal definitions that vary based on individual circumstances. You should consult with a qualified estate planning attorney or tax professional licensed in New York before implementing any of the strategies mentioned, such as charitable clauses, residency changes, or irrevocable trusts. Rates and exemptions cited are estimates and may not reflect the most current law at the time of your reading.