Do You Pay Taxes on Inherited CDs or Bonds?
Inheriting assets can be a bittersweet experience. While it often represents a loved one's legacy, it can also come with a whole lot of confusion and anxiety, especially when financial products like Certificates of Deposit (CDs) and bonds are involved. You're likely wondering, "Do I have to pay taxes on this?" and "How exactly does this all work?" This comprehensive guide is here to untangle the complexities of inherited CDs and bonds, helping you understand the tax implications and what steps you need to take.
Understanding the Basics: Inheriting CDs and Bonds
When you inherit any asset, it's natural to immediately think about taxes. With CDs and bonds, the situation isn't always straightforward because different types of these investments exist, and the timing of interest accumulation plays a significant role. It’s crucial to distinguish between the asset itself and the income it generates, as they are often treated differently from a tax perspective.
What Are CDs and Bonds?
Let's start with a quick refresher on what we're talking about.
- Certificates of Deposit (CDs): These are essentially savings accounts that hold a fixed amount of money for a fixed period (from months to years), and in return, the issuing bank pays you a fixed interest rate. They're considered very low-risk because they're typically FDIC-insured up to $250,000 per depositor, per institution, in each ownership capacity. When a CD matures, you can typically withdraw the principal and earned interest, or roll it over into a new CD.
- Bonds: These are debt instruments issued by governments (federal, state, or municipal) or corporations. When you buy a bond, you're essentially lending money to the issuer. In return, the issuer promises to pay you interest (coupon payments) over a specified period and return your principal at maturity. Bonds come in various forms, including:
- U.S. Treasury Bonds: Issued by the federal government, generally considered very safe. Interest is subject to federal income tax but exempt from state and local taxes.
- Municipal Bonds (Munis): Issued by state and local governments. Interest is often exempt from federal income tax and, sometimes, state and local taxes, especially if you live in the issuing state.
- Corporate Bonds: Issued by companies. Interest is generally subject to federal, state, and local income taxes.
- Savings Bonds (e.g., Series EE, Series I): These are unique bonds issued by the U.S. Treasury. Their interest often accrues and is compounded, typically only taxable when the bond is cashed or reaches maturity, though you can elect to pay annually.
The type of CD or bond you inherit greatly influences how it's handled for tax purposes. For instance, the tax treatment of a municipal bond is quite different from that of a corporate bond or a Series EE savings bond.
Immediate vs. Delayed Tax Concerns
One of the biggest questions people have is whether they'll be hit with an immediate tax bill just for receiving the inheritance. The good news is that for most inherited assets, including CDs and bonds, the value of the asset itself is generally not subject to federal income tax to the beneficiary. This is a common misconception, often conflated with estate taxes or capital gains taxes that apply under different circumstances.
However, the income that these assets generate after the original owner's death, or income that was accrued but not paid before their death, can absolutely be taxable to you, the beneficiary. This distinction is crucial and where much of the complexity lies. For example, if you inherit a corporate bond, you won't pay income tax on the principal amount you receive. But any interest payments generated from that bond after it becomes yours will be considered taxable income to you. Similarly, if you decide to sell the bond, you might face capital gains tax, but usually at a significantly reduced rate thanks to the "step-up in basis" rule, which we'll dive into shortly.
It's also important to remember that while the federal government doesn't levy an inheritance tax on beneficiaries, some states do. So, even if the federal income tax picture seems clear, you still might have state-level obligations depending on where the decedent lived and where you reside. This patchwork of state rules can make things incredibly confusing, and it's a frustration many beneficiaries share.
Decoding the Tax Implications: Interest, Income, and Basis
The tax treatment of inherited CDs and bonds really boils down to two key concepts: "income in respect of a decedent" (IRD) and the "stepped-up basis." Understanding these will clarify most of your tax concerns.
Income in Respect of a Decedent (IRD) Explained
This is perhaps the most tricky part of inheriting certain financial assets. "Income in Respect of a Decedent," or IRD, refers to income that the deceased person was entitled to receive but hadn't yet received as of their date of death. This income isn't included on their final income tax return. Instead, it passes to the beneficiary, who then reports it on their own income tax return.
For CDs and bonds, IRD typically applies to interest that had accrued but was not yet paid out before the original owner passed away. Let's break it down:
- CD Interest: If a CD was earning interest, and some of that interest had been earned but not yet credited to the account or paid out to the decedent before their death, that portion is considered IRD. When you, as the beneficiary, eventually receive that interest (either by cashing out the CD or when it matures), you'll need to report it as income.
- Bond Interest: Similarly, for bonds, if there was accrued interest that the decedent was entitled to but hadn't received, it's IRD. For instance, if a bond pays interest every six months, and the owner dies three months into an interest period, that three months' worth of interest is IRD. When the next full interest payment is made, you'll receive the full amount, but you'll need to account for the IRD portion.
The critical point about IRD is that it doesn't receive a "step-up in basis," which means it remains taxable income. This can be a shock for beneficiaries who assume all inherited assets are tax-free. It's important to differentiate between the principal of the asset and the income it generated. The principal might benefit from a step-up, but the accrued, unpaid income does not.
It's also worth noting that if the decedent's estate paid federal estate tax, there might be a deduction available to you, the beneficiary, for the portion of the estate tax attributable to the IRD. This prevents "double taxation" – once by estate tax and again by income tax. This can be a complex calculation, so consulting with a financial professional or platforms like SmartAsset can be incredibly helpful. You can learn more about how different types of income are treated by looking into topics like Is Inherited Money Taxable?.
Step-Up in Basis for CDs and Bonds
Now for some potentially good news: the "stepped-up basis." This rule is a significant tax advantage for beneficiaries inheriting assets like stocks, real estate, and often, certain types of CDs and bonds. When you inherit an asset, its "cost basis" for capital gains purposes is generally "stepped up" to its fair market value on the date of the original owner's death (or on the alternate valuation date, if elected by the estate).
Let's illustrate with an example:
Imagine your aunt purchased a corporate bond years ago for $10,000. At the time of her passing, that bond was worth $10,500 due to market fluctuations. If you inherit that bond and immediately sell it for $10,500, you wouldn't owe any capital gains tax because your new "stepped-up basis" is $10,500. The $500 gain that your aunt would have realized if she had sold it before her death is essentially wiped away for you.
- Applicability to CDs: For most traditional CDs, the principal amount gets a step-up in basis. If the CD had a fluctuating market value (less common for simple CDs but possible for brokered CDs), the value on the date of death would be your new basis. Any interest earned after the date of death would be taxable income to you.
- Applicability to Bonds: For corporate bonds and municipal bonds (where the principal can fluctuate with market rates), the step-up in basis applies to the principal value. So, if the bond's market value increased after the decedent purchased it, that appreciation is tax-free to you if you sell it at the stepped-up value. If you hold the bond to maturity, you receive the face value, which, if it matches your stepped-up basis, also results in no capital gains. However, any interest payments you receive after inheritance are still taxable income (unless it's a tax-exempt municipal bond).
Understanding Stepped-Up Basis Explained is crucial for anyone inheriting appreciated assets. It significantly impacts the tax bill if you decide to sell.
The Unique Case of Savings Bonds
Savings bonds, such as Series EE or Series I bonds, are the exception to the step-up in basis rule. They do not receive a step-up in basis at the original owner's death. This is a critical distinction and often catches beneficiaries by surprise.
Instead, all the accumulated interest on a savings bond, from the date of its original purchase until it is redeemed by the beneficiary, is considered IRD. This means the beneficiary is responsible for paying income tax on all the interest earned over the bond's entire life. The original owner had deferred paying taxes on that interest, and that tax obligation now falls to the beneficiary.
Let's say your grandfather bought a Series EE bond for $500, and by the time of his death, it had grown to $1,500. The $1,000 in accumulated interest is IRD. When you redeem that bond, you will be taxed on that $1,000 as ordinary income.
You typically have two choices when inheriting savings bonds:
- Redeem them immediately: You'll pay income tax on all the accumulated interest in the year of redemption.
- Re-register them in your name: You can defer paying taxes on the interest until you redeem them or they mature, whichever comes first. However, the clock continues to tick, and more interest accrues, adding to your eventual tax bill.
If you're dealing with a large portfolio of savings bonds, strategizing the timing of their redemption can be important for managing your tax liability. Platforms like SmartAsset can offer resources to help you locate financial advisors who understand these nuances and can assist with your specific situation.
State-Specific Considerations and Planning Tips
While the federal government treats inherited assets fairly consistently, states often have their own rules. This means your location, or the decedent's location, can add another layer of complexity to the tax equation for inherited CDs and bonds.
Inheritance Tax States and Their Impact
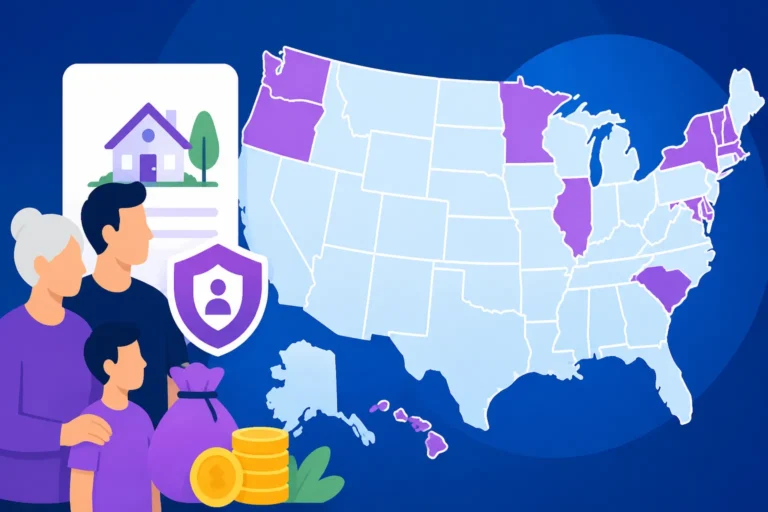
As of 2024, only a handful of states levy an inheritance tax: Iowa (though it's being phased out and will be fully repealed by 2025), Kentucky, Maryland, Nebraska, New Jersey, and Pennsylvania.
Unlike estate tax, which is levied on the total value of the decedent's estate before it's distributed to heirs, inheritance tax is levied on the beneficiary based on the value of the assets they receive. The tax rates and exemptions often depend on your relationship to the deceased. Spouses are typically exempt, and direct descendants (children, grandchildren) usually pay lower rates or are exempt up to certain thresholds. Unrelated beneficiaries often face the highest rates.
Here’s how it might affect inherited CDs and bonds:
- Direct Taxation: If you inherit CDs or bonds from a decedent who lived in one of these states, you might have to pay state inheritance tax on their value, depending on your relationship and the amount inherited. For example, in Pennsylvania, lineal heirs (children, grandchildren) are taxed at 4.5%, while siblings face 12%, and others 15%.
- Estate vs. Inheritance Tax: It's easy to confuse these. Remember, estate tax is on the estate, inheritance tax is on the heir. Maryland is unique as it is the only state that imposes both an estate tax and an inheritance tax. To understand this better, check out Estate Tax vs Inheritance Tax: What's the Difference?.
- "Taxable Situs": The location of the asset itself can sometimes play a role. For instance, if you inherit a CD from a bank located in an inheritance tax state, but you and the decedent lived elsewhere, there might be questions about which state's rules apply. Generally, it's the decedent's state of residence that matters for these taxes, not necessarily the physical location of the bank or brokerage.
If you find yourself inheriting assets and dealing with potential state inheritance taxes, you'll definitely want to look into resources like Which States Have an Inheritance Tax? and consider How to Avoid or Reduce Inheritance Tax might apply to your situation.
| Asset Type | Federal Income Tax on Principal | Federal Income Tax on Post-Death Interest | Federal Capital Gains on Sale (post-step-up) | Stepped-Up Basis? | IRD (Income in Respect of a Decedent) | Potential State Inheritance Tax |
|---|---|---|---|---|---|---|
| Traditional CD | No | Yes (unless tax-exempt) | N/A (usually held to maturity) | Yes | Accrued, unpaid interest before death | Yes (in relevant states) |
| Corporate Bond | No | Yes | Minimal/None (if sold at stepped-up value) | Yes | Accrued, unpaid interest before death | Yes (in relevant states) |
| Municipal Bond | No | No (federally, potentially state/local) | Minimal/None (if sold at stepped-up value) | Yes | Accrued, unpaid interest before death | Yes (in relevant states) |
| U.S. Treasury Bond | No | Yes (federally, exempt state/local) | Minimal/None (if sold at stepped-up value) | Yes | Accrued, unpaid interest before death | Yes (in relevant states) |
| Savings Bond (EE/I) | No | Yes (all accumulated interest) | N/A (interest is IRD) | No | All accumulated interest | Yes (in relevant states) |
This table provides a general overview. Specific circumstances and state laws can vary.
Practical Steps for Beneficiaries
Navigating inherited CDs and bonds doesn't have to be a solo journey. Here are some practical steps you can take:
- Identify and Inventory: Gather all relevant documents for the CDs and bonds. This includes account statements, bond certificates (if physical), and any records of original purchase dates and values. This will help you determine the type of asset and its potential tax implications. When compiling a list of assets, it's helpful to consider What Assets Are Included in Your Estate?.
- Determine Date of Death Values: This is crucial for establishing the stepped-up basis for eligible assets. You'll need the fair market value of each bond or CD (if it has a market value) on the date of the decedent's passing. This might require contacting the issuing bank, brokerage, or the TreasuryDirect website for savings bonds.
- Understand IRD: Clearly identify any interest that had accrued but was unpaid before death. For savings bonds, remember that all accumulated interest is IRD.
- Consult with Professionals: This is perhaps the most important step. An estate attorney or a tax advisor specializing in estate and inheritance taxes can provide invaluable guidance. They can help you accurately calculate your tax liability, whether for federal income tax on IRD or state inheritance taxes. They can also advise on strategies to minimize your tax burden. For instance, a qualified professional can help you understand How Much Can You Inherit Without Paying Taxes? without triggering additional unforeseen liabilities.
- Consider Timing for Savings Bonds: If you inherited Series EE or Series I savings bonds, discuss with your advisor the best time to redeem them. Spreading out the redemption over several tax years might help keep you in a lower tax bracket.
- Review Beneficiary Designations: While it's too late for the assets you've already inherited, ensure your own accounts have proper beneficiary designations. Assets with named beneficiaries typically bypass probate, making the transfer process smoother and faster. This links directly to the idea of How to Avoid Probate.
- Explore State Resources: Many states offer online resources for their inheritance tax laws. For example, the Pennsylvania Department of Revenue website provides detailed information on their inheritance tax rates and filing requirements. For more general guidance, platforms like SmartAsset can help you connect with financial advisors who can provide personalized assistance based on your state and unique financial situation.
- Keep Meticulous Records: Save all correspondence, valuation documents, tax forms, and professional advice related to your inheritance. This will be invaluable if you ever face questions from tax authorities.
Inheriting CDs or bonds certainly requires attention to detail regarding tax implications. While the principal amount is often not subject to federal income tax to the beneficiary, the interest earned, especially accrued interest before death, and the unique rules for savings bonds, mean that tax obligations are often part of the picture. By understanding the concepts of IRD and stepped-up basis, and by seeking professional guidance, you can navigate these waters with greater confidence and ensure you meet your tax obligations without unwelcome surprises.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.