Which States Have an Inheritance Tax?
Navigating the complexities of inheritance can be emotionally challenging enough, but when you add state-level death taxes into the mix, it often feels like an impossible puzzle. Many people assume that if there's no federal inheritance tax, they're in the clear, only to be hit with unexpected financial burdens from the state where their loved one resided or owned property. This comprehensive guide will unravel the mystery, clarifying exactly which states impose an inheritance tax, how these taxes are structured, and what you, as a beneficiary, need to understand to prepare effectively.
Understanding the Basics of Inheritance Tax
It's completely understandable to feel a bit lost when discussions turn to taxes on inherited wealth. The terms "estate tax" and "inheritance tax" are often used interchangeably in casual conversation, but in the realm of tax law, they are distinctly different and knowing the difference is crucial. This isn't just semantics; it determines who is responsible for paying the tax and how it's calculated.
What is Inheritance Tax?
At its core, an inheritance tax is a tax imposed on the recipient of inherited assets. Think of it as a tax on the privilege of receiving property, money, or other assets from a deceased person's estate. It's not levied against the estate itself, but rather on the individual or entity that stands to gain from the inheritance. This means that if you're named a beneficiary in a will or trust, you might be the one writing a check to the state, not the estate. The amount you pay, if anything, usually depends on two main factors: the total value of what you're inheriting and your relationship to the person who passed away (the decedent). Close relatives, like spouses and direct descendants, often receive more favorable treatment, sometimes even being entirely exempt, while more distant relatives or non-relatives might face higher tax rates.
Who Pays Inheritance Tax?
This is where inheritance tax truly distinguishes itself from estate tax. With an inheritance tax, the beneficiary is the one who ultimately bears the tax burden. For instance, if your aunt leaves you $100,000 and you live in a state with an inheritance tax, you, as the nephew or niece, would be responsible for paying the tax on that $100,000, not your aunt's estate. This distinction is vital because it affects your personal financial planning and the net amount you actually receive. While the executor of the estate might facilitate the payment of these taxes from the inherited funds before distribution, the legal obligation to pay rests squarely on your shoulders as the beneficiary. This is why when you're anticipating an inheritance, especially a significant one, understanding your state's laws—or the laws of the state where the deceased lived—is paramount. For a deeper dive into the fundamental differences, you might want to read about Inheritance Tax vs Estate Tax: What's the Difference?.
How is Inheritance Tax Different from Other Death Taxes?
To fully grasp inheritance tax, it's helpful to compare it to its "cousins" in the world of death taxes. The most prominent is the federal estate tax, and some states also have their own state estate taxes. The key differentiator, as mentioned, is who pays.
With an estate tax, whether federal or state, the tax is levied on the total value of the deceased person's estate before any distributions are made to beneficiaries. It's the estate itself that owes the tax, not the individual inheritors. The executor of the estate is responsible for filing the estate tax return and ensuring the tax is paid from the estate's assets. Only after the estate tax (if any) is paid are the remaining assets distributed to beneficiaries. The federal estate tax currently has a very high exemption threshold, meaning only extremely wealthy estates are subject to it. However, a handful of states also have their own estate taxes, often with much lower exemption thresholds, which can impact a broader range of families. For instance, understanding Which States Have an Estate Tax in 2026? can help clarify this.
Inheritance tax, in contrast, looks at the inheritance from the beneficiary's perspective. It's a tax on the transfer to the beneficiary. This means that even if an estate is small enough to avoid estate tax, individual beneficiaries might still owe inheritance tax depending on their relationship to the decedent and the state's specific rules. This nuanced difference can lead to a great deal of confusion and unexpected tax bills if not properly understood and planned for.
The States That Currently Impose Inheritance Tax
The landscape of inheritance tax in the United States is quite sparse, with only a handful of states choosing to implement this particular form of death tax. This can make it even more confusing, as the majority of people live in states where it's not a concern, leading to a general lack of awareness about its existence elsewhere.
Current Landscape of Inheritance Tax States
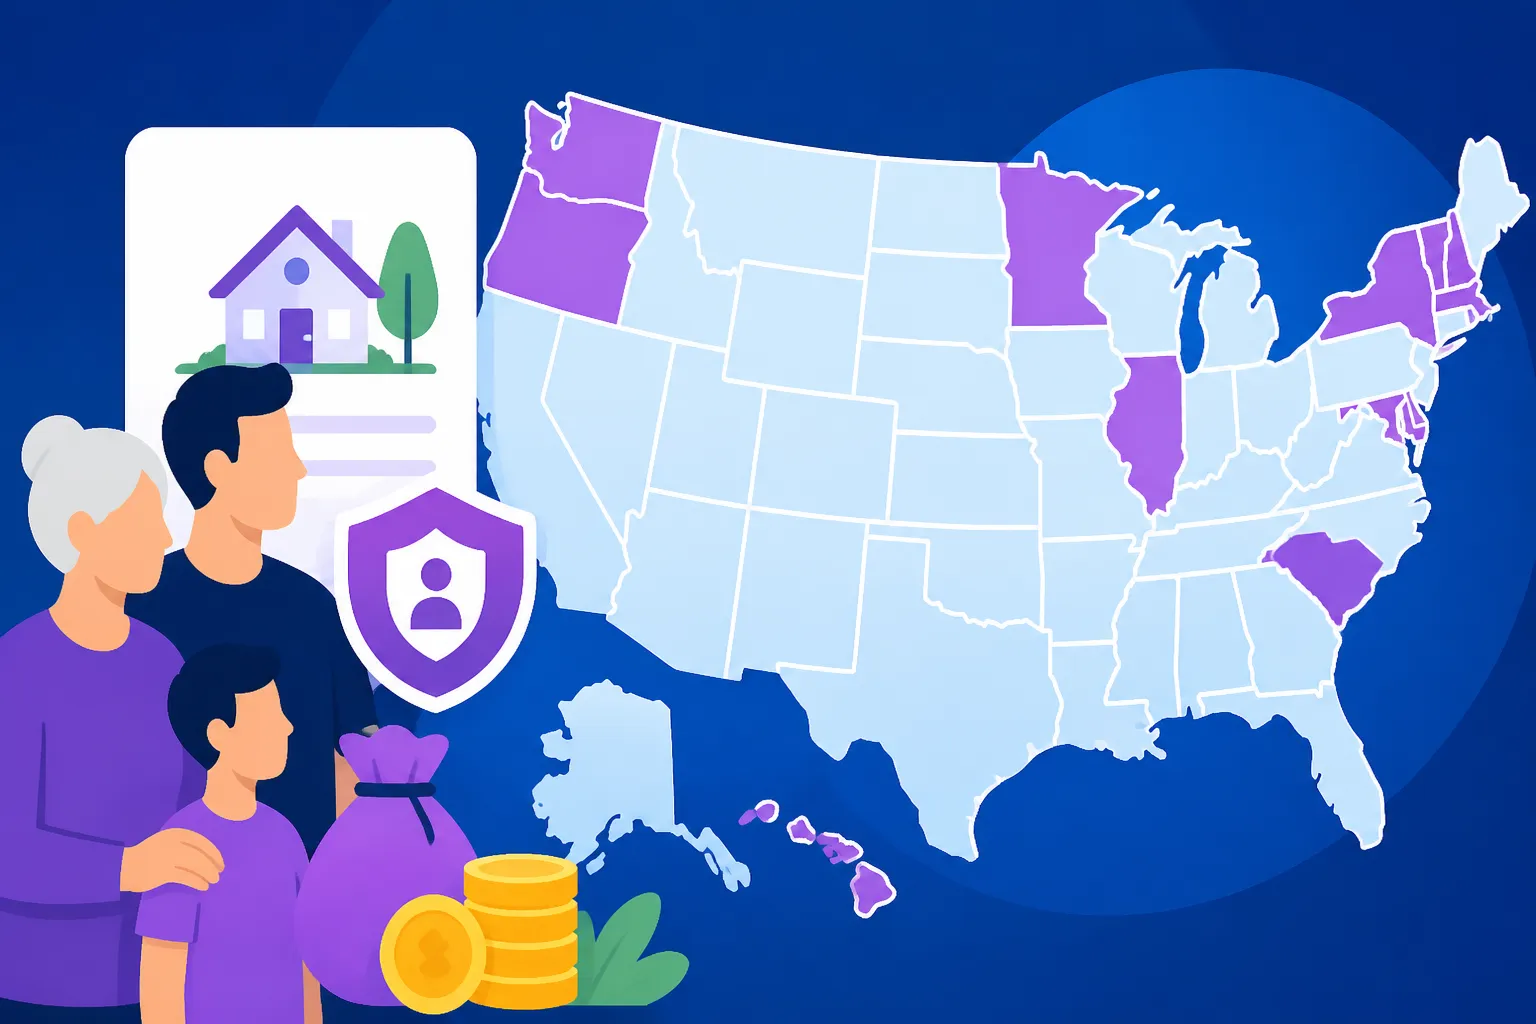
As of 2026, there are only five states that levy an inheritance tax:
- Iowa (though it's in the process of being phased out, with full repeal expected in 2025)
- Kentucky
- Maryland
- Nebraska
- New Jersey
- Pennsylvania
This small number means that the vast majority of beneficiaries across the country won't encounter an inheritance tax. However, if your loved one lived in one of these states, or owned real estate there, you absolutely need to understand the implications. The rules can be intricate, varying significantly from state to state, especially regarding who is exempt and what the tax rates are. For example, some states have broad exemptions for immediate family, while others cast a wider net. The best way to think about it is that if you're inheriting from someone who lived or owned property in these states, consider it a yellow flag that requires further investigation.
States That Have Recently Repealed Inheritance Tax
It's also worth noting that the trend among states has largely been away from inheritance taxes. Over the past few decades, many states have recognized the administrative burden and potential for double taxation (as assets might also be subject to an estate tax or other taxes) and have opted to repeal their inheritance tax laws.
A prime example is Iowa, which is actively phasing out its inheritance tax, with a full repeal set for January 1, 2025. This means that while some estates are currently still subject to it, future inheritances will likely be tax-free in Iowa. Other states like Indiana, North Carolina, and Delaware previously had inheritance taxes but have since repealed them, shifting the burden of death taxes, if any, solely to an estate tax or eliminating them altogether. This ongoing trend highlights the complexity and often unpopular nature of these taxes, reflecting a broader movement to simplify tax codes or attract residents by reducing post-death financial liabilities. Keeping an eye on these legislative changes is crucial for future planning, as mentioned by financial experts at SmartAsset, who often track these evolving state tax policies. You can learn more about this by checking out the Iowa Inheritance Tax Repealed (2025) resource.
Why Only a Few States Have It
The reasons why only a handful of states retain an inheritance tax are varied, often rooted in historical tax structures, revenue needs, and political considerations. In essence, many states have found that the revenue generated from inheritance taxes often doesn't outweigh the administrative costs and the potential for residents to move to no-tax states to avoid them.
Historically, inheritance taxes were more common, serving as a significant revenue stream for state governments. However, as the federal estate tax exemption grew substantially over the years, and with increasing public and political pressure to simplify tax codes and reduce "death taxes," many states opted to eliminate theirs. The remaining states that do impose an inheritance tax often do so because it provides a steady, albeit sometimes controversial, source of income, or because there hasn't been sufficient legislative will to repeal it. For example, states like Maryland, which also levies an estate tax, benefit from the dual revenue stream, despite the added complexity for residents and beneficiaries. It's a balance between funding state services and remaining competitive in attracting and retaining residents, particularly those with higher net worth.
A Closer Look at Each Inheritance Tax State
Since only a handful of states impose an inheritance tax, it's really important to get into the nitty-gritty of each one. Each state has its own unique set of rules, exemptions, and rates, meaning what applies to a beneficiary in Pennsylvania might be completely different for someone inheriting in Nebraska.
Pennsylvania Inheritance Tax: Rates and Beneficiary Classes
Pennsylvania's inheritance tax is one of the more straightforward ones, but it still requires careful attention, especially regarding beneficiary relationships. The Keystone State levies a tax on all assets passing from a decedent to beneficiaries, with the rate depending entirely on how closely related the beneficiary is to the deceased.
- Spouses and Minor Children: As of current laws, transfers to a surviving spouse, as well as to children under the age of 21 (when inheriting from a deceased parent), are completely exempt from Pennsylvania inheritance tax. This is a significant relief for families and helps prevent financial hardship during an already difficult time.
- Lineal Descendants and Ancestors: This category includes adult children, grandchildren, great-grandchildren, and parents or grandparents. They are generally taxed at a rate of 4.5%. This means if an adult child inherits $200,000, they would owe 4.5% of that amount in inheritance tax.
- Siblings: Brothers and sisters of the decedent are subject to a 12% tax rate on their inheritance. This is a substantial jump from the lineal rate and can significantly impact the net amount received.
- All Other Beneficiaries: This broad category includes nieces, nephews, aunts, uncles, cousins, friends, and anyone else not fitting into the above categories. They face the highest tax rate, which is 15%. This can be a considerable sum for non-relatives inheriting substantial assets.
It's crucial for beneficiaries in Pennsylvania to understand these tiers. For example, if a decedent leaves their primary residence to an adult child, that child will owe 4.5% of the appraised value of their share of the home. This is why financial planning ahead of time is so critical; families often don't realize the impact until it's too late. You can delve deeper into the specifics of the Pennsylvania Inheritance Tax Rate Explained for more detailed scenarios.
New Jersey Inheritance Tax: Detailed Breakdown
New Jersey has one of the more complex inheritance tax structures, featuring multiple beneficiary classes and a set of exemptions that require careful navigation. Unlike Pennsylvania, New Jersey actually repealed its estate tax for deaths after January 1, 2018, but it retained its inheritance tax.
- Class A Beneficiaries: This class receives preferential treatment and is entirely exempt from New Jersey inheritance tax. It includes a surviving spouse, civil union partner, domestic partner, children (including legally adopted children), and stepchildren. Parents and grandparents of the decedent are also considered Class A beneficiaries.
- Class C Beneficiaries: This group includes siblings (brothers and sisters) of the decedent and their spouses, along with the spouses of lineal descendants. These beneficiaries are subject to a tax rate, but also benefit from a small exemption. For inheritances over $25,000, they face rates from 11% to 16%. Any portion between $0 and $25,000 is tax-free.
- Class D Beneficiaries: This is the broadest category and applies to all other beneficiaries not covered in Class A or Class C. This includes nieces, nephews, aunts, uncles, cousins, friends, and charitable organizations (though specific charitable exemptions might apply). These beneficiaries do not receive any exemption and are subject to rates ranging from 15% to 16%.
- Class E Beneficiaries: These are typically certain charitable organizations, educational institutions, or religious organizations, which are fully exempt.
The intricacies of the New Jersey system, especially the tiered rates and varying exemptions for different classes, make planning vital. For example, if you inherit a significant sum from a close friend in New Jersey, you could be looking at a 15% or 16% tax bill on the entire amount, with no threshold before the tax kicks in. This is why financial advisors often recommend proactive estate planning in states like New Jersey, potentially utilizing tools to minimize the impact. A closer look at the New Jersey Inheritance Tax (Class A/C/D) can provide more clarity.
Maryland Inheritance Tax: Unique Dual Tax System
Maryland stands out as the only state in the U.S. that imposes both an estate tax and an inheritance tax. This unique dual system means that an estate might first pay estate tax, and then beneficiaries might also pay inheritance tax on the remaining distributions. It's a double whammy for some, highlighting the importance of thorough estate planning in the Old Line State.
- Exempt Beneficiaries: Maryland's inheritance tax has a fairly broad set of exemptions. These include:
- Surviving spouse or domestic partner
- Children (including adopted, stepchildren, and their lineal descendants)
- Parents, grandparents, and other lineal ancestors
- Siblings (brothers and sisters)
- Certain tax-exempt charities
This means that most immediate family members and siblings are completely shielded from the inheritance tax.
- Non-Exempt Beneficiaries: Anyone not falling into the exempt categories, such as nieces, nephews, aunts, uncles, cousins, friends, or unmarried partners, is subject to a flat 10% inheritance tax rate. This rate applies to the fair market value of the inherited assets.
The combination of both taxes in Maryland can be particularly challenging. While the inheritance tax exempts immediate family and siblings, the estate tax exemption (which is lower than the federal one) can still impact larger estates before the inheritance tax even comes into play. If you're a non-exempt beneficiary receiving a $50,000 inheritance, you'd owe $5,000 to the state of Maryland. This kind of situation underscores why financial experts emphasize the importance of understanding the dual tax system in Maryland. More on this can be found in Maryland: The Only State With Both Estate & Inheritance Tax.
Kentucky Inheritance Tax: Classes and Exemptions
Kentucky's inheritance tax system is characterized by its specific beneficiary classes, each with its own exemption amount and tax rate. It's designed to provide substantial relief to immediate family members while taxing more distant relatives and non-relatives.
- Class A Beneficiaries: This category includes the surviving spouse, children (including adopted and stepchildren), grandchildren, parents, grandparents, siblings (brothers, sisters, half-brothers, half-sisters), and other lineal ancestors or descendants. This class is entirely exempt from Kentucky's inheritance tax. This is a significant relief, ensuring that the closest family members do not face an additional tax burden on their inheritance.
- Class B Beneficiaries: This class includes nieces, nephews, aunts, uncles, and the spouses or lineal descendants of these individuals. These beneficiaries receive a $1,000 exemption, and any amount inherited above that threshold is taxed at progressive rates ranging from 4% to 16%. For example, if a niece inherits $10,000, the first $1,000 is exempt, and the remaining $9,000 would be subject to the tiered rates.
- Class C Beneficiaries: This is the "catch-all" class for all other beneficiaries, including friends, unmarried partners, and any other individuals not falling into Class A or Class B. These beneficiaries receive a much smaller exemption of $500. Any inheritance above this amount is taxed at progressive rates from 6% to 16%. This means a friend inheriting $5,000 would see $500 exempt and the remaining $4,500 taxed at a rate beginning at 6%.
The tiered exemption and progressive rates for Class B and C beneficiaries in Kentucky mean that the actual tax owed can vary significantly based on the amount inherited. It’s not just a flat percentage, so understanding the bracket system is crucial. This makes pre-death planning, potentially involving a review of beneficiary designations or gifting strategies, particularly useful for those wishing to pass assets to non-Class A heirs. For more comprehensive details, refer to Kentucky Inheritance Tax Classes.
Nebraska Inheritance Tax: County-Level Specifics
Nebraska's inheritance tax is unique because it's administered at the county level, rather than being a state-managed tax. This means while the rates and beneficiary classes are set by state law, the actual collection and administration occur through the county probate courts. This adds a layer of local bureaucracy to the process.
- Exempt Beneficiaries: Nebraska exempts the surviving spouse, and Class I beneficiaries, which include children (including adopted and stepchildren), grandchildren, great-grandchildren, parents, grandparents, and siblings, pay only 1% on the value each receives above $100,000. Like Kentucky and Pennsylvania, the closest family members are largely protected from this tax.
- Class II Beneficiaries: This class covers aunts, uncles, nieces and nephews. They are allowed an exemption of $40,000 each. Any amount inherited above this exemption is taxed at a flat rate of 11%. So, if a nephew inherits $50,000, $40,000 is exempt, and the remaining $10,000 is taxed at 11%.
- Class III Beneficiaries: This includes all other individuals, such as cousins, friends, and unmarried partners. They receive a very small exemption of $25,000 each. Inheritances exceeding this amount are taxed at a flat rate of 15%. This is one of the highest inheritance tax rates in the country for non-relatives.
- Charitable Exemptions: Bequests to recognized charitable, religious, and educational organizations are generally exempt.
The county-level administration in Nebraska can sometimes lead to slight procedural differences or filing nuances depending on where the decedent resided. While the tax law itself is statewide, the interaction with local officials might vary. It’s always a good idea to consult with a local estate attorney or the county probate court for the most precise guidance if you're inheriting in Nebraska. This specificity reinforces why having a resource like SmartAsset, which can help parse these local distinctions, is so valuable. Further information is available in Nebraska Inheritance Tax (County-Level).
How Inheritance Tax Rates Are Determined
Understanding which state levies an inheritance tax is only half the battle. The real complexity often lies in how these states calculate the actual tax burden. It's not a one-size-fits-all approach; rather, it’s a detailed calculation that considers multiple variables.
Beneficiary Relationship to the Deceased
This is arguably the most critical factor in determining inheritance tax rates. Every state with an inheritance tax has established different "beneficiary classes" based on their familial relationship to the person who passed away. The underlying principle is that closer relatives typically receive more favorable tax treatment, often including complete exemptions, while more distant relatives or non-relatives face higher rates.
- Exempt Classes: Almost universally, surviving spouses are exempt from inheritance tax in all states that impose it. Many states also extend this exemption to lineal descendants (children, grandchildren) and lineal ancestors (parents, grandparents). This reflects a policy goal of not burdening immediate family during a period of loss. For instance, in Pennsylvania, a child inheriting from a parent pays no tax if they are a minor, and only 4.5% if an adult, whereas a friend pays 15%.
- Tiered Tax Rates: As you move further down the family tree or out to non-family members, the tax rates generally increase. Siblings might be in one class, nieces and nephews in another, and then a broad category for everyone else. New Jersey, for example, has its Class A (exempt), Class C (siblings, spouses of lineal descendants, with an exemption and tiered rates), and Class D (all others, with higher rates and no exemption). This tiered approach necessitates a clear understanding of your precise relationship to the decedent.
- Step-Relatives and Adopted Children: Most states treat legally adopted children the same as biological children for inheritance tax purposes. Similarly, stepchildren are often included in the exempt or lower-taxed lineal descendant category, recognizing the family bonds formed through marriage. However, it's always best to verify the specific definitions within each state's tax code, as interpretations can vary.
This relationship-based taxation is why simply knowing that a state has an inheritance tax isn't enough; you need to understand where you fit into their specific beneficiary classification system. For a clearer picture, check out Inheritance Tax Rates by Beneficiary Class.
Exemption Amounts and Taxable Thresholds
Beyond beneficiary relationships, states also utilize exemption amounts and taxable thresholds to determine how much, if any, of an inheritance is subject to tax. These exemptions can significantly reduce or even eliminate the tax burden for many beneficiaries.
- Individual Exemption Amounts: Many inheritance tax states provide a specific dollar amount that each beneficiary can inherit tax-free. Only the portion of the inheritance exceeding this individual exemption is then subject to tax. For example, in Kentucky, Class B beneficiaries (like nieces and nephews) get a $1,000 exemption, and Class C beneficiaries (all others) get a $500 exemption. In Nebraska, Class II beneficiaries (aunts, uncles, nieces, nephews) have a $40,000 exemption, while Class III beneficiaries (friends, etc.) get $25,000. These exemptions mean smaller inheritances often escape taxation entirely for certain classes.
- Overall Taxable Thresholds: It's important to differentiate these individual beneficiary exemptions from an estate tax's overall taxable threshold. With inheritance tax, the focus is on the amount each person receives, not the total size of the estate. So, if an estate is worth millions but is divided among many beneficiaries, each person's share might fall below their individual exemption, leading to no inheritance tax, even in a state that has one.
- No Exemption for Certain Classes: Some states, for their highest-taxed beneficiary classes, offer no exemption whatsoever. In New Jersey, for instance, Class D beneficiaries (non-relatives) start paying tax from the very first dollar they inherit, at rates that can go up to 16%. This is a critical detail that can catch people off guard, especially if they are inheriting from a close friend or an unmarried partner. Knowing How Much Can You Inherit Without Paying Taxes? can provide clarity here.
These exemptions and thresholds are dynamic and can change with state legislation. Regularly consulting up-to-date tax tables or a qualified estate attorney in the relevant state is crucial for accurate planning.
Progressive vs. Flat Rates
The way tax rates are applied also varies between inheritance tax states, generally falling into two categories: progressive rates or flat rates.
- Progressive Rates: With a progressive rate system, the tax percentage increases as the amount inherited grows larger. This means different portions of an inheritance might be taxed at different rates. For example, Kentucky's Class B and Class C beneficiaries face progressive rates, starting lower for smaller inherited amounts and increasing for higher amounts. A beneficiary might pay 4% on the first segment, 6% on the next, and so on, up to the maximum rate for their class. This is similar to how income tax brackets work, where different portions of income fall into different tax rate tiers.
- Flat Rates: Other states opt for a simpler flat rate system for certain beneficiary classes. This means that once an inheritance exceeds any applicable exemption, the entire taxable portion is taxed at a single, fixed percentage. Maryland, for instance, applies a flat 10% inheritance tax rate to all non-exempt beneficiaries. Once you're identified as a non-exempt inheritor, that 10% rate applies to every dollar you receive above the exempted categories. Pennsylvania also uses flat rates for its taxable classes (4.5%, 12%, 15%), making the calculation straightforward once the beneficiary class is determined.
The type of rate structure can significantly impact the final tax bill. Progressive rates can be more complex to calculate but might result in a lower overall tax for moderately large inheritances compared to a flat rate that applies to the entire amount over a small exemption. Conversely, flat rates offer more predictability once the class is established. Understanding How Inheritance Tax Is Calculated can provide further insights.
Assets Subject to Inheritance Tax
When someone passes away, their "estate" encompasses a wide array of assets, and not all of them are treated the same way when it comes to inheritance tax. It's not just about cash in a bank account; many different types of property can be included.
Real Estate and Tangible Personal Property
Real estate, such as a family home, vacation property, or investment land, is often the largest asset in an estate and is frequently subject to inheritance tax if it's located in an inheritance tax state. The value typically used for tax purposes is the fair market value of the property at the time of the decedent's death.
- Primary Residence: Yes, even the family home can be subject to inheritance tax. If you inherit your childhood home from a parent in, say, Pennsylvania, and you're an adult child, your portion of the home's value (after any exemptions) could be taxed at the 4.5% rate. The executor will typically need to get an appraisal to establish its fair market value.
- Investment Properties and Land: Any other real estate owned by the decedent, whether it's a rental property, undeveloped land, or a commercial building, will also be included in the calculation for inheritance tax purposes. The value of these assets can significantly increase the total inheritance and, consequently, the potential tax liability.
- Tangible Personal Property: This category includes physical items like cars, boats, jewelry, art collections, antique furniture, and other valuable possessions. These items are also appraised at their fair market value at the time of death and can contribute to the taxable inheritance. While individual items might not trigger a huge tax bill, a collection of valuable items could. For instance, a rare coin collection or a vintage car could push an inheritance over an exemption threshold.
It's important to remember that inheritance tax applies to the beneficiary's share of these assets. If a property is jointly owned with rights of survivorship, it might pass directly to the surviving owner outside of the probate estate, though its value could still be included in the total for inheritance tax purposes depending on state law.
Bank Accounts and Investment Portfolios
Liquid assets like bank accounts, brokerage accounts, and various investments are also very commonly subject to inheritance tax. These assets are usually straightforward to value: the balance in the account or the market value of the investments on the date of death.
- Savings and Checking Accounts: Funds held in checking, savings, and money market accounts are generally included in the taxable inheritance. If you're named as a beneficiary to one of these accounts, the full amount you receive, minus any applicable exemptions, could be taxed.
- Brokerage Accounts and Stocks: Investment portfolios, including individual stocks, bonds, mutual funds, and exchange-traded funds (ETFs), are valued at their market price on the date of death. These assets can represent a significant portion of an inheritance, especially for those with diversified portfolios. If you inherit stocks, the inheritance tax will apply to their value at the time of the decedent's passing.
- Certificates of Deposit (CDs) and Annuities (Non-Qualified): CDs and non-qualified annuities (those not held within an IRA or 401(k)) are also typically subject to inheritance tax. Their value is generally their surrender value or account balance at the time of death. However, some annuities might have specific payout structures that could affect how they are treated.
For all these accounts, if they have Payable-on-Death (POD) or Transfer-on-Death (TOD) designations, they might bypass probate, but that doesn't necessarily mean they bypass inheritance tax. The tax is on the transfer of value to the beneficiary, regardless of whether it goes through the probate process.
Retirement Accounts and Life Insurance Payouts
These types of assets have specific rules that often differ from other inherited property, particularly when it comes to tax implications, including inheritance tax.
- Retirement Accounts (IRAs, 401(k)s, etc.): Whether an inherited retirement account is subject to inheritance tax depends on the specific state's laws. Generally, if the account has a named beneficiary, it passes directly to them outside of probate. However, some states, like Pennsylvania, do include retirement accounts in the inheritance tax base, while others, like New Jersey, exempt certain retirement benefits from the tax. The tax treatment of the distributions themselves (income tax) is a separate matter from the inheritance tax. For instance, an inherited IRA is subject to specific income tax rules, such as the 10-year rule, but the inheritance tax question is about its value at the time of death. You can learn more about Inheritance Tax on Retirement Accounts & Life Insurance to understand the nuances.
- Life Insurance Payouts: Life insurance proceeds paid directly to a named beneficiary are almost always exempt from state inheritance taxes. This is a significant benefit, as life insurance is often intended to provide financial security to loved ones without the burden of additional taxes. The rationale is that these proceeds are considered a contractual payment to the beneficiary, not an asset owned by the decedent at the time of death. However, if the life insurance policy names the estate as the beneficiary, then the proceeds would flow into the estate and could become subject to inheritance tax if the estate then distributes them to non-exempt beneficiaries. This is a critical distinction to be aware of when setting up or reviewing beneficiary designations.
It is always prudent for beneficiaries to seek advice from an estate planning professional or tax advisor, especially when dealing with complex assets like retirement accounts and life insurance, to understand their specific state's rules and how these assets will be taxed.
Strategies to Mitigate or Avoid Inheritance Tax
No one wants to see a significant portion of their inheritance eaten away by taxes. The good news is that with careful planning, there are strategies available to legally reduce or even avoid state inheritance taxes. These often involve proactive steps taken by the decedent during their lifetime. For general advice, consider reading How to Avoid or Reduce Inheritance Tax.
Gifting Strategies During Lifetime
One of the most effective ways to reduce the size of a taxable inheritance is for the future decedent to make gifts to their intended beneficiaries while they are still alive. This transfers assets out of their estate, potentially reducing or eliminating the inheritance tax that would otherwise be due upon their death.
- Annual Gift Tax Exclusion: The IRS allows individuals to give a certain amount of money or property to anyone each year without triggering federal gift tax or requiring a gift tax return. For 2026, this annual exclusion amount is $19,000 per recipient. If a person wants to leave $100,000 to a friend in a high-inheritance-tax state like Nebraska (15% for non-relatives), they could gift $19,000 each year over several years. This reduces the amount remaining in their estate at death and avoids a large inheritance tax bill for the friend. Keep in mind that only Connecticut has a state-level gift tax, so most states don't impose their own gift tax on these transfers.
- Medical and Tuition Payments: Payments made directly to an educational institution for tuition or to a medical provider for medical care are not considered taxable gifts, regardless of the amount. This means a grandparent could pay directly for a grandchild's college tuition or medical bills without those payments counting against their annual gift exclusion or increasing their future estate's inheritance tax liability.
- Utilizing the Lifetime Exemption: Beyond the annual exclusion, there's also a federal lifetime gift tax exemption (which is unified with the federal estate tax exemption). While this typically doesn't directly impact state inheritance tax, using it for large gifts during life still removes assets from the taxable estate that would otherwise be subject to state inheritance tax for beneficiaries. However, it's crucial to understand the state-specific implications, as some states might have "gift add-back" rules that pull recent gifts back into the estate for state estate tax calculation, though this is less common for inheritance taxes.
It's vital that gifts are made outright and completely transferred, with the donor giving up all control over the asset. If the donor retains any control or benefit from the gifted asset, the IRS and state tax authorities might consider it part of their estate. Consulting with an estate planning attorney or financial advisor, perhaps a professional from SmartAsset, is highly recommended to ensure these strategies are executed correctly and align with both federal and state laws.
Utilizing Trusts for Asset Transfer
Trusts are powerful estate planning tools that can be incredibly effective in mitigating or avoiding inheritance tax, especially for assets intended for non-exempt beneficiaries or in states with high rates. The key principle is that assets placed into an irrevocable trust are generally no longer considered part of the grantor's (the person who set up the trust) taxable estate.
- Irrevocable Trusts: By transferring assets into an irrevocable trust, the grantor gives up control and ownership of those assets. This means they are removed from the grantor's estate and, upon death, can be distributed to beneficiaries according to the trust's terms, often bypassing both probate and, crucially, inheritance tax. For example, a person wanting to leave a significant inheritance to a beloved niece in New Jersey might place those funds into an irrevocable trust for her benefit. Since the trust owns the assets, not the decedent, the niece would not pay inheritance tax on the distributions from the trust.
- Life Insurance Trusts (ILITs): An Irrevocable Life Insurance Trust (ILIT) is a common strategy to remove life insurance proceeds from an estate. While life insurance paid directly to named beneficiaries is usually inheritance tax-free, if the estate is the beneficiary (or if the policy owner wants to avoid it being included in their federal estate for estate tax purposes), an ILIT can be beneficial. The trust owns the policy and receives the death benefit, which it then distributes to the beneficiaries according to the trust's terms, free of estate and potentially inheritance taxes.
- Grantor Retained Annuity Trusts (GRATs): While more complex and typically used for federal estate tax planning, GRATs can also play a role in reducing the value of assets subject to state death taxes. With a GRAT, the grantor transfers assets into an irrevocable trust but retains the right to receive an annuity payment for a set number of years. At the end of the term, any remaining appreciation in the trust assets passes to the beneficiaries, potentially at a significantly reduced or zero gift/estate tax value. This effectively "freezes" the value of the asset for tax purposes at the time it's transferred into the GRAT.
The choice and setup of a trust should always be done with the guidance of an experienced estate planning attorney. The rules around trusts are complex, and an incorrectly structured trust could fail to achieve its intended tax benefits. For more information, consider reading How to Avoid Estate Tax With Trusts.
Understanding Exempt Beneficiaries
A straightforward way to avoid inheritance tax for certain individuals is simply to ensure that the primary beneficiaries are those who are exempt under state law. As we've seen, every inheritance tax state provides exemptions for certain classes of beneficiaries.
- Spouses and Direct Lineal Relatives: In every state that levies an inheritance tax, a surviving spouse is fully exempt. In most of these states (Pennsylvania, Kentucky, Nebraska, Maryland), direct lineal descendants (children, grandchildren) and direct lineal ancestors (parents, grandparents) are also either fully exempt or subject to very low rates. Therefore, prioritizing these individuals as beneficiaries can significantly reduce or eliminate inheritance tax liabilities.
- Considering the Impact of Non-Exempt Beneficiaries: If the decedent wishes to leave a substantial portion of their estate to non-exempt beneficiaries (e.g., a dear friend, a niece or nephew in certain states, or an unmarried partner), it becomes even more important to explore gifting strategies or trusts. The higher tax rates for these classes mean the tax bite can be substantial. For example, in Nebraska, a non-relative could pay 15% on a large inheritance, whereas a child would pay only 1% on amounts above $100,000.
- Reviewing Beneficiary Designations: It's not just about the will; beneficiary designations on accounts like life insurance policies, retirement accounts, and Transfer-on-Death (TOD) or Payable-on-Death (POD) accounts are critical. By naming an exempt beneficiary directly on these accounts, the assets can pass outside of probate and often avoid inheritance tax. If an exempt beneficiary is named on a life insurance policy in Maryland, for example, the proceeds are typically free of inheritance tax for that beneficiary.
Periodic review of estate plans and beneficiary designations is essential to ensure they align with current tax laws and the decedent's wishes, especially if family circumstances change or state tax laws are updated.
Key Differences: Inheritance Tax vs. Estate Tax
It's common for people to conflate "estate tax" and "inheritance tax," and while both are "death taxes," their distinctions are profound and impact different parties. Understanding these differences is not just academic; it directly influences financial planning and how wealth is transferred.
Who Pays the Tax: Estate vs. Beneficiary
This is the most fundamental difference and the easiest way to tell them apart:
- Estate Tax: With an estate tax, the deceased person's estate is responsible for paying the tax. This means that before any assets are distributed to heirs, the executor of the estate must determine the total value of the "taxable estate," calculate any federal and/or state estate tax due, and pay it from the estate's funds. Only the remaining assets are then passed on to beneficiaries. Think of it as a tax on the right to transfer property at death. The federal government, along with a number of states like New York or Oregon, levies an estate tax.
- Inheritance Tax: In contrast, an inheritance tax is levied on the beneficiary who receives the assets. It's a tax on the right to receive property. So, if you inherit money or property in a state with an inheritance tax, you, as the inheritor, are the one legally obligated to pay that tax. While the estate's executor might withhold funds to cover your inheritance tax before distributing your share, the ultimate liability rests with you. States like Pennsylvania and New Jersey have an inheritance tax.
This distinction profoundly impacts financial planning. For an estate tax, the decedent's estate plan focuses on strategies to reduce the overall taxable estate. For an inheritance tax, planning might shift to ensuring beneficiaries are exempt or to making lifetime gifts to reduce their individual tax burden.
Taxable Thresholds and Exemptions
Both estate and inheritance taxes have thresholds and exemptions, but they are applied differently.
- Estate Tax Thresholds: Estate taxes, especially the federal estate tax, have a very high exemption amount. For 2026, the federal exemption is $15 million per individual. This means very few estates are subject to federal estate tax. State estate taxes also have their own thresholds, which are typically much lower than the federal one (e.g., Maryland's exemption is $5 million, while Oregon's is $1 million). If an estate's value is below these thresholds, no estate tax is due. This is a single, overall threshold applied to the entire estate.
- Inheritance Tax Exemptions: Inheritance taxes, as discussed, operate with exemptions based on the beneficiary's relationship to the deceased, and sometimes on the amount each individual beneficiary receives. There isn't an overall estate threshold that applies to inheritance tax in the same way. Instead, a surviving spouse might be completely exempt, an adult child might have a partial exemption or a lower rate, and a friend might have no exemption at all or a very small one, facing higher tax rates. This granular approach means that even a modest estate could trigger inheritance tax for certain beneficiaries if their relationship falls into a taxable class. For instance, you can learn more about how State Estate Tax Exemptions & Rates Compared 2026 against inheritance tax exemptions.
The interplay of these thresholds can be particularly confusing in states like Maryland, which has both. An estate might pay estate tax if it exceeds $5 million, and then non-exempt beneficiaries might also pay inheritance tax on their individual shares.
Federal vs. State Level Taxes
The distinction between federal and state-level taxes adds another layer of complexity.
- Federal Taxes: The U.S. federal government imposes an estate tax (often referred to as the federal estate tax), but it does not have a federal inheritance tax. This is why many people mistakenly believe no inheritance tax exists at all. The federal estate tax applies to the estates of individuals who die with assets exceeding the high federal exemption.
- State Taxes: This is where the landscape fragments. A minority of states impose a state estate tax (separate from the federal one), and an even smaller handful impose an inheritance tax. Only Maryland currently levies both. The other inheritance tax states (Kentucky, Nebraska, New Jersey, Pennsylvania, and Iowa – phasing out) do not have their own state estate tax, meaning they rely on the inheritance tax for death-related revenue. This makes the state-level tax landscape highly varied, and knowing where the decedent resided (or owned real property) is crucial for understanding potential tax liabilities. You can find out more about the broader context in State vs Federal Estate Tax: How They Stack.
This table provides a quick reference for understanding the critical differences:
| Feature | Estate Tax | Inheritance Tax |
|---|---|---|
| Who Pays? | The deceased person's estate (executor) | The beneficiary who receives the inheritance |
| What is Taxed? | The total value of the decedent's estate | The value of assets received by each individual beneficiary |
| Exemptions/Thresholds | One large exemption for the entire estate (e.g., $15M federal, $1M-$5M state) | Vary by beneficiary's relationship and amount received; often individual beneficiary exemptions |
| Federal Level | Yes (federal estate tax) | No (no federal inheritance tax) |
| State Level | Yes, in ~12 states and D.C. | Yes, in 5 states (KY, MD, NE, NJ, PA) plus IA (phasing out) |
| Goal | Tax the transfer of wealth from an estate | Tax the receipt of wealth by an heir |
Navigating the Inheritance Tax Process for Beneficiaries
Receiving an inheritance, especially in a state with an inheritance tax, can feel like a labyrinth of paperwork and deadlines. As a beneficiary, even if the executor handles much of the heavy lifting, it's vital to understand the general process and your responsibilities.
Filing Requirements and Deadlines
The inheritance tax process typically begins shortly after a person's death and involves specific forms and timelines that must be adhered to.
- The Executor's Role: While the beneficiary ultimately pays the inheritance tax, the executor of the estate (or administrator, if there's no will) is generally responsible for valuing the estate's assets, identifying beneficiaries, calculating the inheritance tax for each, and filing the necessary inheritance tax return with the state. They will likely withhold the estimated tax from your share before distributing your inheritance.
- State-Specific Forms: Each inheritance tax state has its own specific forms that must be completed. For instance, Pennsylvania requires the filing of Form REV-1500, "Pennsylvania Inheritance Tax Return," within nine months of the decedent's death. New Jersey uses Form IT-R, "New Jersey Inheritance Tax Return." These forms detail all assets, deductions, and distributions, allowing the state to calculate the tax due.
- Payment Deadlines: The inheritance tax is generally due within a certain period after the decedent's death, typically nine months, similar to federal estate tax deadlines. If the tax is not paid by this deadline, penalties and interest may accrue. Some states, like Pennsylvania, offer a small discount (e.g., 5%) if the tax is paid within an earlier timeframe, often three months. This provides an incentive for prompt payment. If you're concerned about potential delays, beneficiaries might need to coordinate with the executor to ensure timely payments. Getting clear on Inheritance Tax Deadlines by State is a critical step.
Beneficiaries should maintain open communication with the estate's executor or attorney to stay informed about the progress of the estate settlement and any impending tax obligations.
Valuation of Assets
Accurate valuation of the decedent's assets is crucial for determining the correct inheritance tax. The value used is typically the fair market value (FMV) of each asset on the date of the decedent's death.
- Real Estate Appraisals: For real estate, a professional appraisal is almost always required to establish the FMV. This provides an objective valuation that state tax authorities will accept. The appraiser will consider factors like recent comparable sales, property condition, and market trends. If multiple beneficiaries inherit a single property, the value is then divided according to their respective shares.
- Personal Property and Collectibles: Valuable tangible personal property, such as art, jewelry, antiques, or collections, may also require professional appraisals, especially if their value is significant. For less valuable items, a good-faith estimate based on market research might suffice, but it's important to be transparent and reasonable.
- Financial Accounts: Bank accounts, brokerage accounts, and retirement accounts are generally easier to value, as their fair market value is simply the balance or market price of the holdings on the date of death. Statements from financial institutions provide this information.
- Business Interests: Inheriting an interest in a private business can be particularly complex to value, often requiring specialized business valuation experts. The valuation must account for the business's assets, liabilities, earnings, and future prospects.
The executor is responsible for overseeing these valuations. However, beneficiaries should be aware that the valuation process can sometimes be contentious, and if they believe an asset has been incorrectly valued, they may need to raise concerns with the executor or legal counsel.
Seeking Professional Guidance
Given the complexities of inheritance tax laws, especially when combined with federal and state estate taxes or differing state rules, seeking professional guidance is almost always a wise decision.
- Estate Planning Attorneys: An estate planning attorney who specializes in the laws of the state where the decedent resided (or owned significant property) can provide invaluable advice. They can help interpret the specific tax code, ensure all forms are filed correctly, and navigate any disputes or complications that may arise. They can also advise on strategies to minimize future inheritance tax for your own estate planning.
- Tax Advisors and CPAs: A certified public accountant (CPA) or a tax advisor with experience in estate and inheritance taxes can help calculate the exact tax liability, identify potential deductions, and ensure compliance with all tax regulations. They can also advise beneficiaries on the income tax implications of inherited assets, which are separate from inheritance tax. For instance, while you might not pay inheritance tax on an inherited IRA in some states, you will almost certainly pay income tax on the distributions.
- Financial Advisors: A financial advisor can help beneficiaries integrate their inheritance into their overall financial plan, taking into account tax implications, investment goals, and long-term financial security. Firms like SmartAsset often have tools and resources that can help individuals locate financial advisors specializing in estate and tax planning, who can offer tailored advice.
Trying to navigate the inheritance tax process alone, especially with significant assets or complex family structures, can lead to costly errors, penalties, and missed opportunities for tax savings. Investing in professional advice can save a considerable amount of stress and money in the long run.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.