Which States Have an Estate Tax in 2026?
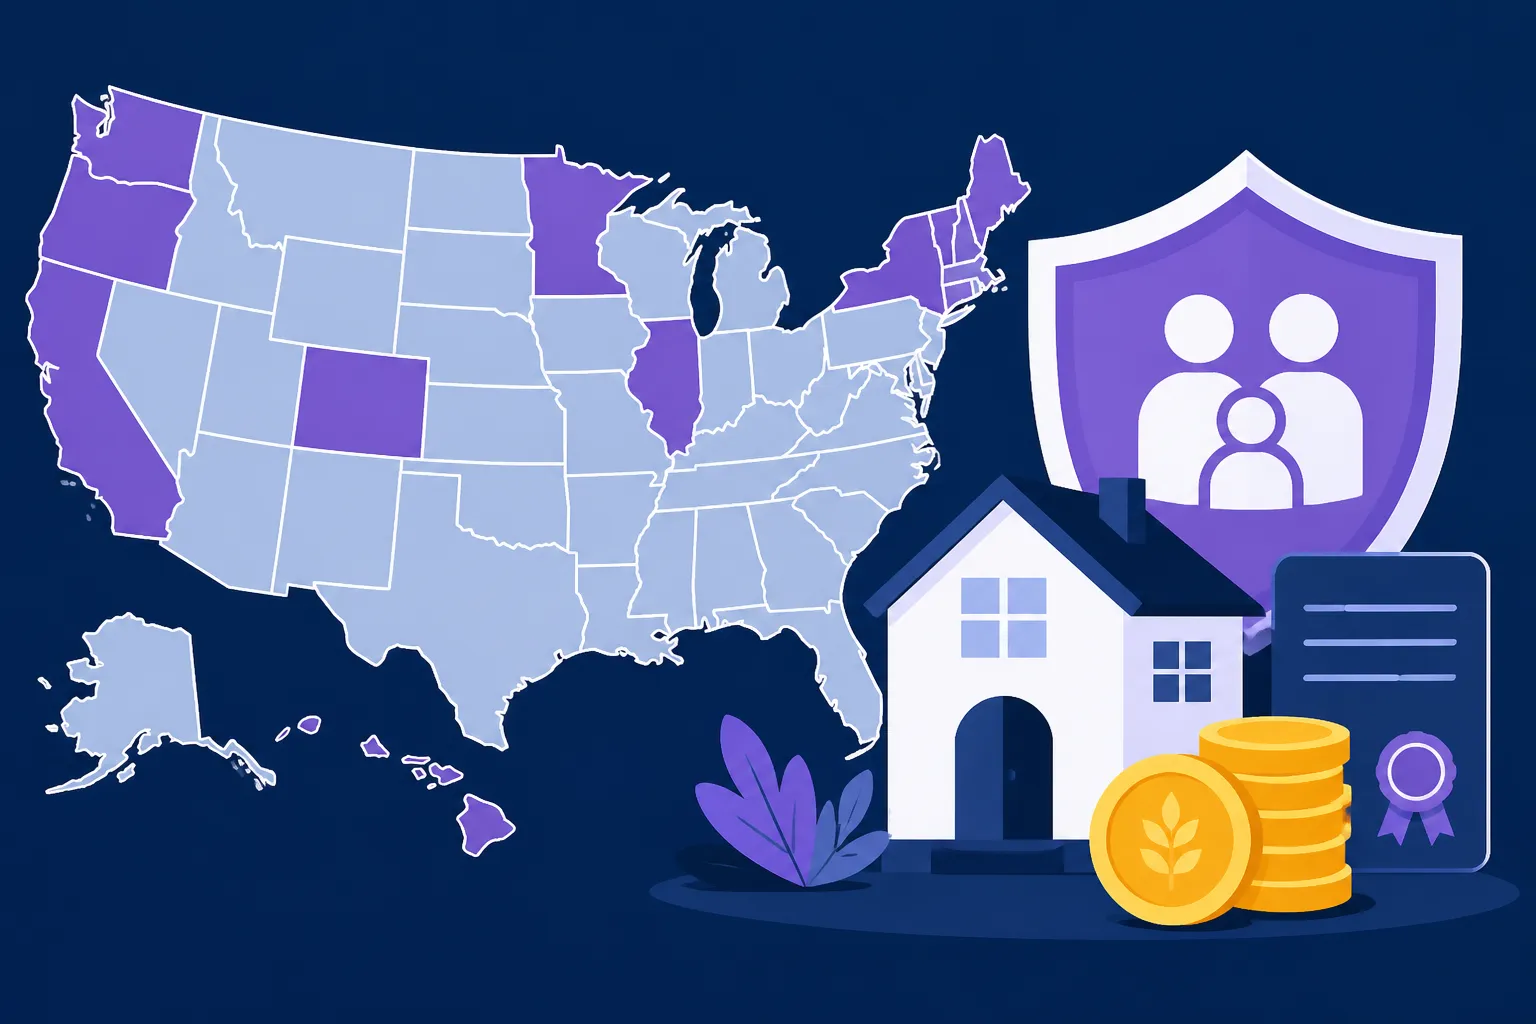
You have spent decades building a life, paying off a mortgage, and carefully tending to your retirement accounts, only to realize that your state might take a significant bite out of what you leave behind. Many families are shocked to discover that while they fall safely under federal limits, their home state has much lower thresholds. This guide clarifies exactly which states have an estate tax in 2026 and how you can protect your legacy.
Understanding the 2026 State Estate Tax Landscape
The year 2026 is a massive turning point for estate planning across the country. For the last several years, many of us have been operating under the generous federal exemptions provided by the Tax Cuts and Jobs Act. However, as we navigate the landscape of this year, the "sunset" provisions have changed the math for thousands of families. While the federal exemption remains relatively high for some, the real danger for the average successful professional lies at the state level. Many states have not kept pace with inflation or federal changes, leaving their residents vulnerable to taxes that kick in at much lower asset levels than you might expect.
The Great Divide Between State and Federal Rules
One of the most common frustrations I hear from readers is the confusion between what the IRS wants and what their local state revenue department demands. You might be looking at the Federal Estate Tax Exemption 2026 ($15 Million) and thinking you are completely in the clear. But state governments often operate on entirely different logic. While the federal government is currently looking at high-net-worth individuals, some states are looking at anyone who owns a modest home and a decent life insurance policy.
It is vital to realize that state estate taxes are not just "mini" versions of the federal tax. They have their own filing requirements, their own specific exemptions, and their own unique traps. For instance, How State Estate Tax Works involves a calculation that starts from your gross estate, which includes everything from your kitchen table to your 401(k). If you live in a state like Oregon or Massachusetts, you might find yourself owing money to the state even if the federal government doesn't take a dime.
Why 2026 is a Critical Year for Your Planning
We are currently in a period of significant legislative flux. Several states have been debating whether to raise their exemptions to match inflation or to repeal these taxes entirely to stop the "wealth flight" to places like Florida or Arizona. When you look at Which States Are Repealing or Changing Estate Tax?, you see a map that is constantly shifting. For those of us living in high-tax corridors, 2026 is the year to sit down with a calculator and a cup of coffee to see if your current plan still makes sense.
A tool like SmartAsset can help establish a baseline for your net worth. It is easy to underestimate the value of your assets, especially when you factor in the appreciation of real estate in many of the states that still hold onto an estate tax. A house bought for $200,000 in the 90s might be worth $1.2 million today, and in some jurisdictions, that single asset is enough to trigger a massive tax bill for your children.
The Role of Inflation Indexing in State Laws
Not all state exemptions are created equal. Some states, like Maine and Rhode Island, have built-in mechanisms to adjust their exemptions for inflation every year. Others, like Illinois, have "fixed" exemptions that haven't changed in years, effectively taxing more and more people every year as the value of the dollar drops and property values rise. Understanding How Estate Tax Exemptions Are Indexed for Inflation can help you predict if your estate will be taxable five or ten years from now.
If you are living in a state where the exemption is stagnant, you are essentially facing a "stealth" tax increase every single year. This is particularly painful for family-owned businesses and farms. You may not feel wealthy in terms of cash flow, but your "paper wealth" in equipment and land can easily blow past a $1 million or $2 million exemption. This is where strategic planning becomes a necessity rather than a luxury.
The New England Block: High Costs of Living and Dying
New England is arguably the most challenging region in the country when it comes to death taxes. Almost every state in the corner of the country maintains some form of estate tax, often with exemptions that catch the middle class. If you are a resident of this region, your "lifestyle" includes a silent partner—the state government—that is waiting for its share of your final accounts.
Massachusetts and the Two Million Dollar Threshold
For a long time, Massachusetts had one of the lowest exemptions in the country at just $1 million. Thankfully, recent reforms moved that needle, but the Massachusetts Estate Tax ($2 Million) still catches many residents by surprise. In the current real estate market, a family home in a suburb like Newton or Wellesley can easily account for more than half of that exemption on its own.
When I talk to families in the Bay State, the primary concern is often the "cliff" effect, though Massachusetts has moved toward a more graduated system recently. Still, the paperwork alone is a burden. Even if your estate is just slightly over the limit, your executor will have to deal with complex filings during a time of grief. It is wise to use the resources at SmartAsset to find local professionals who can help navigate the specific M-706 form requirements that are unique to Massachusetts.
Rhode Island and the Cost of Coastal Living
Rhode Island follows a similar path to its neighbors, but with its own quirks. The Rhode Island Estate Tax (About $1.8M) is indexed for inflation, which provides a small amount of relief, but it remains a low bar for anyone who has been diligent about their retirement savings. Because Rhode Island is so small, many residents have property in both Rhode Island and Massachusetts or Connecticut, which creates a nightmare of "multi-state" estate tax filings.
If you own a summer cottage in Narragansett but live primarily in Providence, you are looking at a taxable situation that requires careful asset titling. One of the most frequent questions I get is, Does My House Count Toward State Estate Tax?, and the answer in the Ocean State is a resounding yes. Your primary residence, your beach house, and even your boat are all part of the "gross estate" that the state will evaluate.
Connecticut: A Shift Toward Federal Alignment
Connecticut used to be known as one of the most aggressive tax states in the union, even having its own gift tax. However, the state has made significant strides to become more competitive. The Connecticut Estate Tax (Matches Federal $15M) has finally aligned with the federal exemption in 2026, which is a massive win for residents. This alignment means that for most families, the state tax is no longer a primary concern—unless future inflation adjustments or tax laws change things.
However, you still have to be careful with the Connecticut Gift Tax Explained. Connecticut remains the only state in the country with a standalone gift tax. This means if you try to give away your wealth while you are alive to avoid the estate tax, the state might still want a cut if you exceed the lifetime limits. It is a unique trap that requires a very specific type of planning that you won't find in any other state.
The Mid-Atlantic Struggle: Maryland and DC
Moving down the coast, the tax environment doesn't get much friendlier. In fact, for residents of Maryland, it actually gets twice as complicated. This region is a hub for high-earning professionals and government contractors who often don't realize their "work-life" success is creating a significant tax liability for their heirs.
Maryland: The Double Tax State
Maryland holds a unique and somewhat unenviable title: it is the only state in the nation that imposes both an estate tax and an inheritance tax. This is a point of massive confusion for residents. When looking at Maryland: The Only State With Both Estate & Inheritance Tax, you have to realize that these are two different bills. The estate tax is paid by the estate itself before anything is distributed, while the inheritance tax is paid by the person receiving the money (depending on their relationship to you).
The Maryland Estate Tax (Plus Inheritance Tax) system means that even if your estate is under the $5 million estate tax exemption, your distant relatives or friends might still owe a 10% inheritance tax on every dollar you leave them. This "double-dip" strategy by the state makes Maryland one of the most expensive places to die if you are leaving money to anyone other than your immediate family. SmartAsset often highlights Maryland as a state where "location-based" planning is absolutely vital.
The District of Columbia: Taxing the Capital
Living in the District comes with a high price tag, and that extends to your estate. The DC Estate Tax Explained is notable because the exemption is significantly lower than the federal level, often hovering around the $4 million mark depending on annual inflation adjustments. For many long-time DC residents, the massive appreciation of row houses in Capitol Hill or Georgetown has pushed them into "taxable" territory without them even realizing it.
The tax rates in DC are also quite high, topping out at 16%. If you are a high-net-worth individual living within the District limits, you are looking at a significant loss of wealth to the local government. This has led many to consider moving across the border to Virginia, which has no estate tax, though that comes with its own set of lifestyle tradeoffs.
The Impact on Nonresidents with Local Property
One thing people often forget is that you don't have to live in these states to owe them money. If you live in Florida but own a rental property in Baltimore or a condo in DC, your estate might still owe a "pro-rated" estate tax to those jurisdictions. This is known as Estate Tax for Residents vs Nonresidents. The state will look at your total global assets, calculate what the tax would be if you lived there, and then bill you for the percentage of your assets that are physically located within their borders.
This catches many "snowbirds" off guard. They think that by changing their residency to a tax-free state, they have solved the problem. But if you hold onto that family home in Maryland or DC, the state still has its hand out. Dealing with these multi-state filings can be incredibly expensive for your executor, often costing thousands in extra legal and accounting fees.
The Pacific Northwest and Hawaii: High Rates in Paradise
On the other side of the country, the story remains much the same. The West Coast is home to some of the most entrenched estate tax laws in the country. These states view the estate tax as a vital part of their social safety net funding, which means they are unlikely to repeal them anytime soon.
Oregon: The Lowest Bar in the Nation
Oregon is famous among estate planners for having the lowest estate tax exemption in the United States. The Oregon Estate Tax ($1 Million Exemption) is a relic of a different era, but it persists. In today's economy, a $1 million exemption is shockingly low. If you have a modest home in Portland, a healthy 401(k), and a small life insurance policy, you are almost certainly over the limit.
They don't consider themselves wealthy, yet the state is taking a percentage of their life savings. The rates start at 10% and go up to 16%. If you are in this situation, you need to look at How to Avoid Oregon Estate Tax through strategies like gifting or specific types of trusts. Without planning, a $2 million estate in Oregon could easily owe $100,000 or more in taxes—money that could have gone to grandchildren's college funds.
Washington State: High Stakes and Rate Changes
Just to the north, Washington State also maintains a robust estate tax system. While the exemption is higher than Oregon's (around $2.19 million, indexed for inflation), the rates are among the highest in the country. The Washington Estate Tax (35% to 20% Rate Change) has been a topic of much debate in the state legislature, but the reality remains that for those with significant assets, Washington is an expensive place to leave a legacy.
Washington is also unique because it does not have a state income tax. To make up for that, they rely heavily on other taxes, including the estate tax. For many residents, the trade-off is worth it during their working years, but it becomes a liability in their later years. Many retirees in Seattle or Bellevue use SmartAsset to compare their current tax burden against moving to a state like Nevada or Idaho.
Hawaii: Taxing the Islands
Hawaii's estate tax is often overlooked, but it is one of the most aggressive. The Hawaii Estate Tax (20% Over $10M) features a top rate that is significantly higher than most other states. Even for estates that are smaller, the tax starts early and climbs fast. Because Hawaii is a popular place for second homes, many people from the mainland find themselves caught in Hawaii's tax net.
The cost of living in Hawaii is already astronomical, and the estate tax only adds to the burden of passing down property to the next generation. If you own "Ohana" property that has been in the family for years, the appreciation alone could trigger a tax bill that forces your heirs to sell the land just to pay the state. This is a heartbreaking reality for many local families who are "land rich and cash poor."
| State | 2026 Exemption | Top Tax Rate | Notes |
|---|---|---|---|
| Oregon | $1,000,000 | 16% | Lowest exemption in the U.S. |
| Massachusetts | $2,000,000 | 16% | Recent increase from $1M. |
| Rhode Island | $1,838,056 | 16% | Indexed annually for inflation. |
| Washington | ~$2,193,000 | 20% | Highest top rate in the nation. |
| Illinois | $4,000,000 | 16% | Fixed exemption, not indexed. |
| Maryland | $5,000,000 | 16% | Also has an Inheritance Tax. |
| New York | ~$7,000,000 | 16% | Has a "cliff" (see below). |
| Connecticut | ~$15,000,000 | 12% | Matches federal exemption. |
The "Cliff" States: Why Falling Off Matters
One of the most devious features of state estate taxes is the "cliff." Most people assume that if you are over the exemption, you only pay tax on the "extra" amount. For example, if the limit is $2 million and you have $2.1 million, you'd expect to pay tax on $100,000. In most states, that's how it works. But in "cliff" states, going even a dollar over the limit can have catastrophic consequences.
The New York Estate Tax Cliff Explained
New York is the most famous example of this. The New York Estate Tax Cliff Explained is a rule that states if your estate is more than 5% over the exemption amount, you lose the exemption entirely. This means the state taxes you on the very first dollar of your estate, not just the amount over the limit. It is an "all or nothing" tax that can turn a small oversight into a massive bill.
Imagine you are in New York and the exemption is roughly $7 million. If your estate is worth $7.35 million (just over the 5% buffer), New York will tax you on the full $7.35 million. That small $350,000 "excess" could end up costing your heirs over $600,000 in taxes. It is a brutal mathematical reality that makes How to Avoid the New York Estate Tax Cliff the most important conversation any New Yorker can have with their planner.
Illinois: A Fixed Exemption Trap
Illinois doesn't have a "cliff" in the same way New York does, but it has its own version of a trap. The Illinois Estate Tax ($4 Million) exemption is not indexed for inflation. This means that every year, as the price of milk and houses goes up, more and more families in Chicago and the surrounding suburbs fall into the tax net. The state has shown very little interest in raising this limit, using it as a reliable source of revenue for its cash-strapped budget.
For many Illinois residents, the state tax is a "middle-class" tax. A $4 million estate might sound like a lot, but for a couple who both had successful careers and a house in Naperville, it is a very easy number to hit. The lack of portability in Illinois—the ability to pass your unused exemption to a spouse—makes this even more of a challenge for married couples.
Minnesota and the Three-Year Gift Add-Back
Minnesota is another state with a unique and frustrating rule. The Minnesota Estate Tax (3-Year Gift Add-Back) means that if you give away money within three years of your death, the state "adds it back" to your estate for tax purposes. You can't just give away your wealth on your deathbed to avoid the taxman in the Gopher State.
This rule requires residents to start their gifting strategies early. If you wait until you are in declining health to move assets out of your name, the state of Minnesota will act as if those assets never left. This is a common tactic to prevent "deathbed planning," but it catches many families who were simply trying to help their children with a down payment on a house or college tuition without realizing the tax implications.
Strategies to Protect Your Legacy
Knowing which states have the tax is only half the battle. The real work is in figuring out how to keep as much of your hard-earned money as possible for your loved ones. You don't have to just accept these taxes as an inevitability. There are legal, proven ways to reduce your taxable estate, but they require you to be proactive.
The Power of Gifting and the Annual Exclusion
The simplest way to reduce your estate tax bill is to stop owning so much stuff. You can do this through gifting. Every year, you are allowed to give a certain amount to as many people as you want without even having to tell the IRS. In 2026, the Annual Gift Tax Exclusion 2026 ($19,000) allows you to move significant wealth over time. If a married couple gives $19,000 each to their three children and their spouses, they can move $114,000 out of their estate every single year.
Over a decade, that's over $1.1 million removed from the reach of the state estate tax. This is a "use it or lose it" strategy. You cannot go back and claim previous years' exclusions. This is why it is wise to start gifting as soon as they realize they might have an estate tax problem. It is the most effective, least expensive way to lower your tax bill.
Using Trusts to Bypass the State
For those with larger estates, gifting $19,000 at a time might not be fast enough. This is where trusts come in. People often ask, Does a Trust Avoid State Estate Tax?, and the answer is: it depends on the trust. A standard revocable living trust won't help you avoid estate taxes because you still control the money. However, an irrevocable trust—one where you give up control—can move assets entirely out of your taxable estate.
There are specialized tools like the SLAT (Spousal Lifetime Access Trust) or the ILIT (Irrevocable Life Insurance Trust) that are designed specifically to tackle this problem. By putting a large life insurance policy into an ILIT, the payout remains tax-free for your heirs, rather than being added to your gross estate and potentially pushing you over the state exemption.
Moving: The Nuclear Option
Finally, there is the option that many people in high-tax states eventually choose: moving. If you are looking at States With No Estate Tax (2027), you'll see popular destinations like Florida, Texas, Nevada, and Tennessee. For some, the potential tax savings of several hundred thousand dollars is enough to justify selling the family home and heading south.
However, Estate Tax When Moving to a No-Tax State isn't as simple as just buying a house in Orlando. You have to truly "sever ties" with your old state. High-tax states like New York and Massachusetts are notorious for "residency audits." They will look at where you spend your time, where your doctors are, and even where you keep your most sentimental items. If they think you are just "pretending" to live in Florida to avoid their estate tax, they will still come after your estate.
Does Your Home Push You Over the Limit?
For the vast majority of people, the primary driver of an estate tax problem isn't a secret offshore account or a massive stock portfolio—it's the roof over their heads. We have seen a historic rise in property values over the last decade, and that "home equity" is fully taxable when you pass away.
Real Estate Appreciation and the Middle Class
In states like Washington or Massachusetts, a "normal" family home can easily be worth $1 million or more. When you add in a modest 401(k) and some life insurance, you have a "taxable estate" even if you don't feel "rich." This is the great irony of state estate taxes; they were often designed to target the "robber barons" of the past, but today they are hitting teachers, nurses, and small business owners.
If you are worried about this, the first step is to get a realistic appraisal of your home. Don't just rely on your property tax assessment, which is often lower than the actual market value. Tools like SmartAsset can help you aggregate your total assets to see where you stand. If your home is the bulk of your wealth, you might need to consider a "Qualified Personal Residence Trust" (QPRT) to move the home's value out of your estate while still living in it.
The Liquidity Crisis for Heirs
The biggest danger of a "real estate heavy" estate is a lack of liquidity. If your estate owes $150,000 in taxes to the state of Oregon, but your only asset is a $1.2 million house, your children will be forced to sell that house just to pay the tax bill. This is a tragedy that happens every day.
To prevent this, some people take out a small life insurance policy specifically to cover the estimated estate tax. Others set aside a "liquidity fund" in a separate account. The goal is to ensure that your children have the cash on hand to pay the state without being forced into a "fire sale" of the family home.
Final Thoughts on 2026 Planning
The 2026 estate tax landscape is more complex than it has been in decades. Between federal adjustments and shifting state laws, there is no "set it and forget it" plan. You need to be diligent, stay informed, and be willing to adjust your strategy as the laws change. Whether you choose to stay in your home state and plan around the tax, or move to a more tax-friendly climate, the choice should be yours—not a surprise left for your heirs to deal with.
State Estate Tax Disclaimer
The information provided in this guide is for educational and informational purposes only and does not constitute legal, financial, or tax advice. Estate tax laws are subject to frequent changes at both the state and federal levels, and specific exemptions or rates for 2026 may vary based on updated legislation or inflation adjustments. You should consult with a qualified estate planning attorney or tax professional to discuss your specific situation and ensure your plan complies with the most current laws in your jurisdiction.