Does a Trust Avoid State Estate Tax?
Navigating the complexities of estate planning can feel like wading through quicksand, especially when you're trying to figure out how to protect your assets from state estate taxes. Many people worry that after a lifetime of hard work, a significant chunk of their legacy could be eaten up by taxes, leaving less for their loved ones. This guide will thoroughly explore whether trusts can indeed offer a shield against state estate taxes and delve into the nuances of how different trust structures might impact your financial future.
Understanding Trusts and Their Role in Estate Planning
Before we dive into the nitty-gritty of state estate taxes, let's get a handle on what trusts are and how they generally function in the world of estate planning. At its heart, a trust is a legal arrangement where one person (the grantor or settlor) gives another person (the trustee) the right to hold assets for the benefit of a third party (the beneficiary). It's essentially a way to manage and distribute your assets according to your specific wishes, often bypassing the often-lengthy and public probate process.
For many families, the appeal of a trust lies in its ability to offer control and privacy. Instead of your will dictating distributions through a court-supervised process, a trust can quietly and efficiently transfer assets directly to your beneficiaries. This can be a huge relief for families who want to avoid the potential delays and legal fees associated with probate, ensuring that their loved ones receive their inheritance more smoothly and in line with their intentions.
Revocable vs. Irrevocable Trusts: A Key Distinction
When it comes to trusts, the biggest fork in the road is often deciding between a revocable living trust and an irrevocable trust. The difference here is absolutely crucial, especially when we talk about estate taxes.
A revocable living trust is, as its name suggests, something you can change, amend, or even completely dissolve during your lifetime. You, as the grantor, typically serve as the initial trustee and beneficiary, maintaining full control over your assets. While a revocable trust is fantastic for avoiding probate and managing assets during incapacity, it generally does not remove assets from your taxable estate for estate tax purposes. This is because you still have control over those assets, and the IRS (and state tax authorities) still consider them yours at the time of your death. Think of it like putting your money in a different pocket – it's still your money.
On the other hand, an irrevocable trust is a completely different beast. Once you transfer assets into an irrevocable trust, you generally give up control over them. You cannot easily change the terms of the trust, remove assets, or act as the trustee. This "giving up control" is precisely why irrevocable trusts can be powerful tools for reducing your taxable estate. Because the assets are no longer considered yours, they typically won't be counted when calculating your state or federal estate tax liability. It's like you've truly given that money away, albeit to a trust for your beneficiaries. Understanding this fundamental difference is the first step in seeing how a trust can help you with state estate tax planning. You can learn more about how different types of trusts work by exploring our guide on Types of Trusts Explained (ILIT, GRAT, QTIP & More).
The Role of a Trust in Your Overall Estate Plan
A trust isn't a standalone solution; it's a vital component of a comprehensive estate plan. Your estate plan typically includes not just a trust, but also a will, powers of attorney, and healthcare directives. Each piece serves a unique purpose, and they all work together to ensure your wishes are carried out and your loved ones are protected. For example, even with a robust living trust, you’ll usually still need a "pour-over will" to catch any assets you might accidentally leave outside the trust.
When you're trying to figure out how to best manage your wealth, particularly for larger estates that might be subject to state estate taxes, integrating trusts becomes paramount. They allow for intricate planning that can address specific family needs, protect beneficiaries with special needs, or even ensure a family business continues smoothly. A good estate plan looks at your entire financial picture and aligns your assets with your long-term goals, whether that's minimizing taxes, providing for minors, or leaving a philanthropic legacy. For a broader overview of what you might need, check out an Estate Planning Checklist.
How Different Types of Trusts Interact with State Estate Taxes
This is where the rubber meets the road. Not all trusts are created equal when it comes to state estate taxes. While a revocable living trust might be excellent for avoiding probate, it won't help you lower your state estate tax burden. For that, you generally need to look at irrevocable trusts. These trusts are specifically designed to move assets out of your taxable estate, which is critical for reducing or even avoiding state estate taxes in states like New York, Oregon, or Massachusetts.
The key mechanism here is that by placing assets into an irrevocable trust, you effectively remove them from your personal ownership. Because you no longer legally "own" those assets, they are not counted towards your gross estate at the time of your death for estate tax calculations. This can be a huge benefit, particularly for individuals living in one of the twelve states (plus D.C.) that impose their own estate tax, often with much lower exemption thresholds than the federal government. A trusted advisor can often model these scenarios, helping you understand the potential savings.
Irrevocable Life Insurance Trusts (ILITs)
One of the most common and effective irrevocable trusts for estate tax planning is the Irrevocable Life Insurance Trust, or ILIT. Here’s how it works: you establish an ILIT, and the trust then owns your life insurance policy. When you pass away, the death benefit is paid directly to the ILIT, which then distributes the funds to your chosen beneficiaries according to the trust’s terms.
Why is this a big deal for state estate taxes? Because if you own your life insurance policy personally, the death benefit is typically included in your gross estate for estate tax purposes. For a large policy, this could push your estate over the state exemption threshold, triggering a significant tax bill. With an ILIT, the life insurance proceeds are held outside your estate, making them exempt from both federal and state estate taxes. This can preserve a substantial amount of wealth for your heirs, allowing them to receive the full benefit without it being diminished by estate taxes. If you’re considering this option, delving deeper into Types of Trusts Explained (ILIT, GRAT, QTIP & More) can provide more context.
Grantor Retained Annuity Trusts (GRATs)
A Grantor Retained Annuity Trust (GRAT) is another powerful tool for high-net-worth individuals, particularly those with appreciating assets. With a GRAT, you transfer assets (like stocks or real estate) into the trust and, in return, receive an annuity payment from the trust for a specified number of years. When the trust term ends, any remaining assets (the appreciation above a certain IRS-defined rate) pass to your beneficiaries free of estate and gift taxes.
The magic of a GRAT lies in its ability to "freeze" the value of your assets for estate tax purposes. While you receive an income stream, the growth of the assets within the trust can effectively be transferred to your heirs without being subject to estate tax. This strategy is particularly effective when interest rates are low and you expect significant appreciation in the assets you're transferring. It's a calculated risk, but for the right assets, it can yield substantial estate tax savings, both at the state and federal level.
Qualified Personal Residence Trusts (QPRTs)
If your primary concern is reducing the estate tax value of your home, a Qualified Personal Residence Trust (QPRT) might be a great fit. With a QPRT, you transfer your home (or a vacation property) into an irrevocable trust for a set number of years, but you retain the right to live in it for that period. When the term ends, the home passes to your beneficiaries.
The significant benefit here is that when you establish the QPRT, the value of the gift for estate tax purposes is discounted. This is because the IRS accounts for your retained right to live in the home for a period, as well as the possibility that you might not survive the trust term. If you outlive the trust term, the full value of the home (and any future appreciation) is removed from your taxable estate. This can lead to substantial state estate tax savings on what is often a family's most valuable asset. It’s a way to effectively transfer wealth while still enjoying your home, but it does require careful planning to ensure you survive the trust term.
Bypass Trusts and Marital Deductions
For married couples, especially those with estates approaching or exceeding state estate tax exemptions, a bypass trust (also known as a credit shelter trust or AB trust) used to be a cornerstone of estate planning. While their prominence has shifted due to federal portability rules, they remain relevant for state estate tax planning in many jurisdictions.
Here’s the traditional setup: when the first spouse dies, an amount up to the state estate tax exemption is transferred into the bypass trust. This trust can provide for the surviving spouse, but the assets within it are not considered part of the surviving spouse's estate when they later pass away. This means that the first spouse's exemption is fully utilized, and those assets pass to the ultimate beneficiaries free of estate tax at both deaths. The remaining assets, if any, often pass to the surviving spouse tax-free via the unlimited marital deduction. This strategy ensures that both spouses' individual state estate tax exemptions are leveraged, potentially saving hundreds of thousands of dollars in taxes for their heirs. To understand more about how these deductions work, you can read about the Marital Deduction & Estate Tax.
Specific State Estate Tax Considerations and Trust Planning
The landscape of state estate taxes is incredibly varied, which is why a one-size-fits-all approach to trusts simply doesn't work. What might be a game-changer in New York could be completely unnecessary in Florida. Understanding your specific state's rules is the bedrock of effective trust planning to avoid state estate taxes. Organizations like SmartAsset provide valuable state-specific tax resources that can help you find advisors familiar with your local tax laws.
It’s crucial to remember that each state with an estate tax has its own unique exemption amount and rate structure. For instance, Oregon's estate tax exemption is $1 million, while in Massachusetts, it's $2 million. New York has a complex "estate tax cliff" where estates just over the exemption can face a significantly higher tax burden. Knowing these specific thresholds and how your assets measure up against them is the first critical step in determining if a trust strategy is even necessary for your situation. Without this foundational knowledge, you might be planning for a problem that doesn't exist for you, or, worse, overlooking a substantial liability. Our article on State Estate Tax Exemptions & Rates Compared 2026 can give you a clear picture of current state-specific rules.
States with Estate Taxes and Their Exemptions
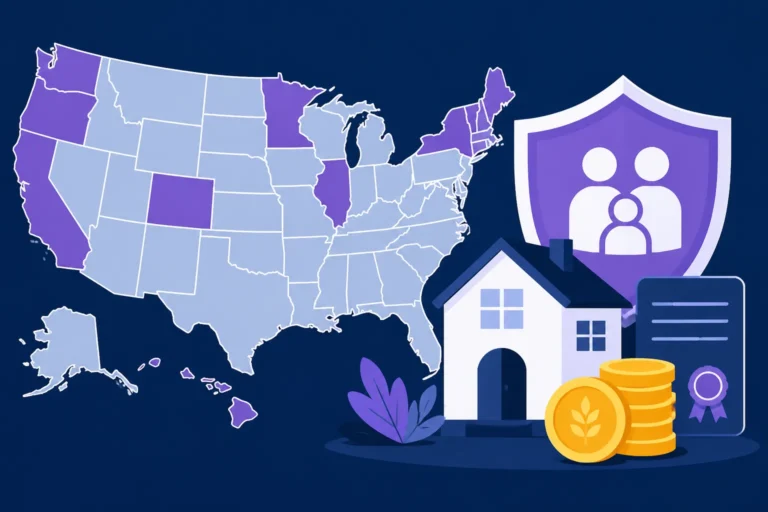
Currently, a handful of states and the District of Columbia impose their own estate taxes. These states are:
- Connecticut
- Hawaii
- Illinois
- Maine
- Maryland
- Massachusetts
- Minnesota
- New York
- Oregon
- Rhode Island
- Vermont
- Washington
- District of Columbia
Each of these jurisdictions has its own exemption amount, which is the value an estate can pass on without being subject to the state's estate tax. These exemptions are often significantly lower than the federal estate tax exemption, which is $15,000,000 per individual in 2026. This means that an estate that easily sails past the federal threshold without issue might still be hit with a state estate tax. For example, an estate of $3 million might be far below the federal tax radar, but it would be taxable in states like Oregon or New York. Therefore, if you reside in or own property in one of these states, a trust specifically designed to reduce your taxable estate becomes a much more relevant conversation. For a full list, see Which States Have an Estate Tax in 2026?. Conversely, it's also helpful to know States With No Estate Tax (2027).
Here’s a snapshot of some state estate tax exemptions (approximate and subject to change):
| State | Estimated 2026 Exemption |
|---|---|
| Connecticut | ~$15 Million (matches federal) |
| Hawaii | $10 Million |
| Illinois | $4 Million |
| Maine | $7 Million |
| Maryland | $5 Million |
| Massachusetts | $2 Million |
| Minnesota | $3 Million |
| New York | ~$6.94 Million |
| Oregon | $1 Million |
| Rhode Island | ~$1.8 Million |
| Vermont | $5 Million |
| Washington | ~$2.19 Million |
| District of Columbia | $4 Million |
Note: These figures are estimates for 2026 and are subject to legislative changes and inflation adjustments. Always consult current state tax authority publications or a qualified professional for the most up-to-date information.
Navigating Multi-State Property and Residency
The complexity of state estate tax planning multiplies if you own property in more than one state, especially if one of those states has an estate tax and another does not. Your state of "domicile" (your primary legal residence) usually determines which state's estate tax laws apply to your overall estate. However, real property (like a house or land) you own in another state with an estate tax will generally be subject to that state's tax, regardless of your domicile.
Consider a scenario where you reside in Florida (which has no state estate tax) but own a valuable vacation home in Maine (which has an estate tax with a $7.16 million exemption). Even though your domicile is Florida, the Maine property might be included in your estate for Maine estate tax purposes if its value, combined with other assets located in Maine, exceeds the state's exemption. This situation often necessitates careful planning, possibly using a QPRT or other specialized trust structures to mitigate the tax burden on your out-of-state assets. It underscores why understanding Estate Tax for Residents vs Nonresidents is so vital. Working with an estate planning attorney who understands multi-state tax laws is crucial to ensure you don't face unexpected tax liabilities.
Beyond Trusts: Other Strategies for State Estate Tax Planning
While trusts are powerful, they're not the only arrows in your quiver when it comes to state estate tax planning. A truly comprehensive approach often involves a combination of strategies, carefully tailored to your unique financial situation and goals. Understanding these other options can help you create a more resilient plan, whether or not you ultimately decide a trust is the best fit for every asset.
The goal is always the same: reduce your taxable estate while ensuring your assets are distributed according to your wishes. Often, combining strategies can yield better results than relying on just one. For instance, strategic gifting combined with a well-structured trust can dramatically reduce the size of your taxable estate over time. It’s about leveraging all available tools to minimize the impact of state estate taxes on your legacy. For a deep dive into avoiding these taxes, consider reading How to Avoid State Estate Tax Legally.
Strategic Gifting and Annual Exclusions
One of the simplest yet most effective ways to reduce your taxable estate is through strategic gifting during your lifetime. The IRS allows you to give away a certain amount of money or assets to as many individuals as you want each year, without incurring gift tax or using up your lifetime gift tax exemption. This is known as the annual gift tax exclusion. In 2026, this amount is expected to be $19,000 per recipient.
By consistently making annual exclusion gifts, you can gradually reduce the size of your estate over time, thereby lowering your potential state estate tax liability. For example, a couple could gift $38,000 annually to each of their children and grandchildren, significantly shrinking their combined taxable estate without triggering any immediate tax consequences. While there isn't a state-level gift tax in most states (Connecticut is a notable exception), these gifts effectively move assets out of your estate before they become subject to state estate taxes. For more on this, check out Annual Gift Tax Exclusion 2026 ($19,000).
Maximizing Marital and Charitable Deductions
For married individuals, the unlimited marital deduction is an invaluable tool. It allows you to transfer an unlimited amount of assets to your spouse, either during your lifetime or at your death, without incurring any federal or state gift or estate tax. This means that if you leave your entire estate to your surviving spouse, there generally won't be any estate tax due at your death. The tax is essentially deferred until the surviving spouse passes away.
Similarly, if you're charitably inclined, gifts or bequests to qualified charities are also 100% deductible for estate tax purposes. This means that any assets you leave to a qualified charitable organization will reduce your taxable estate dollar for dollar, potentially lowering or eliminating your state estate tax burden. Combining these deductions effectively, perhaps by using a Qualified Terminable Interest Property (QTIP) trust for a spouse and making charitable bequests, can be a cornerstone of an effective estate tax reduction strategy.
The Importance of Professional Guidance
Let's be real: navigating estate tax laws, especially at the state level, is incredibly complex. The rules are always changing, and what works for one family might not work for another. Trying to go it alone or rely on generic online advice can lead to costly mistakes. This is where professional guidance becomes indispensable.
An experienced estate planning attorney and a qualified financial advisor can help you analyze your unique situation, identify potential estate tax liabilities, and design a tailored plan that leverages trusts and other strategies to meet your goals. They can help you understand the nuances of your state's specific estate tax laws, draft the appropriate trust documents, and ensure everything is properly funded and executed. Don't underestimate the value of having experts on your side. Resources like SmartAsset can help you find vetted financial advisors in your area who specialize in estate planning, ensuring you get advice that's relevant to your local tax environment and specific needs. It's an investment that can save your heirs a considerable amount of money and stress in the long run.
Disclaimer
The information provided in this article is for general informational purposes only and does not constitute legal, financial, or tax advice. Estate tax laws are complex and subject to change. You should consult with a qualified estate planning attorney, financial advisor, or tax professional to discuss your specific situation and make informed decisions.