The Estate Tax Cliff Explained (New York & More)
Imagine working your entire life to build a nest egg, only to discover that exceeding a specific state tax limit by a single dollar could cost your family hundreds of thousands in unexpected taxes. This is the reality of the estate tax cliff, a brutal tax structure that catches many families off guard. This guide explains how cliffs work, specifically in New York, and how to protect your legacy.
What Exactly Is an Estate Tax Cliff
Most of us are used to the way federal income tax works. If you move into a higher tax bracket, you only pay the higher rate on the dollars that fall into that new bucket. It is a progressive system that feels relatively fair. However, an estate tax cliff operates on an entirely different, and frankly much harsher, logic. It is an "all-or-nothing" scenario where crossing a specific financial threshold causes you to lose your entire tax exemption.
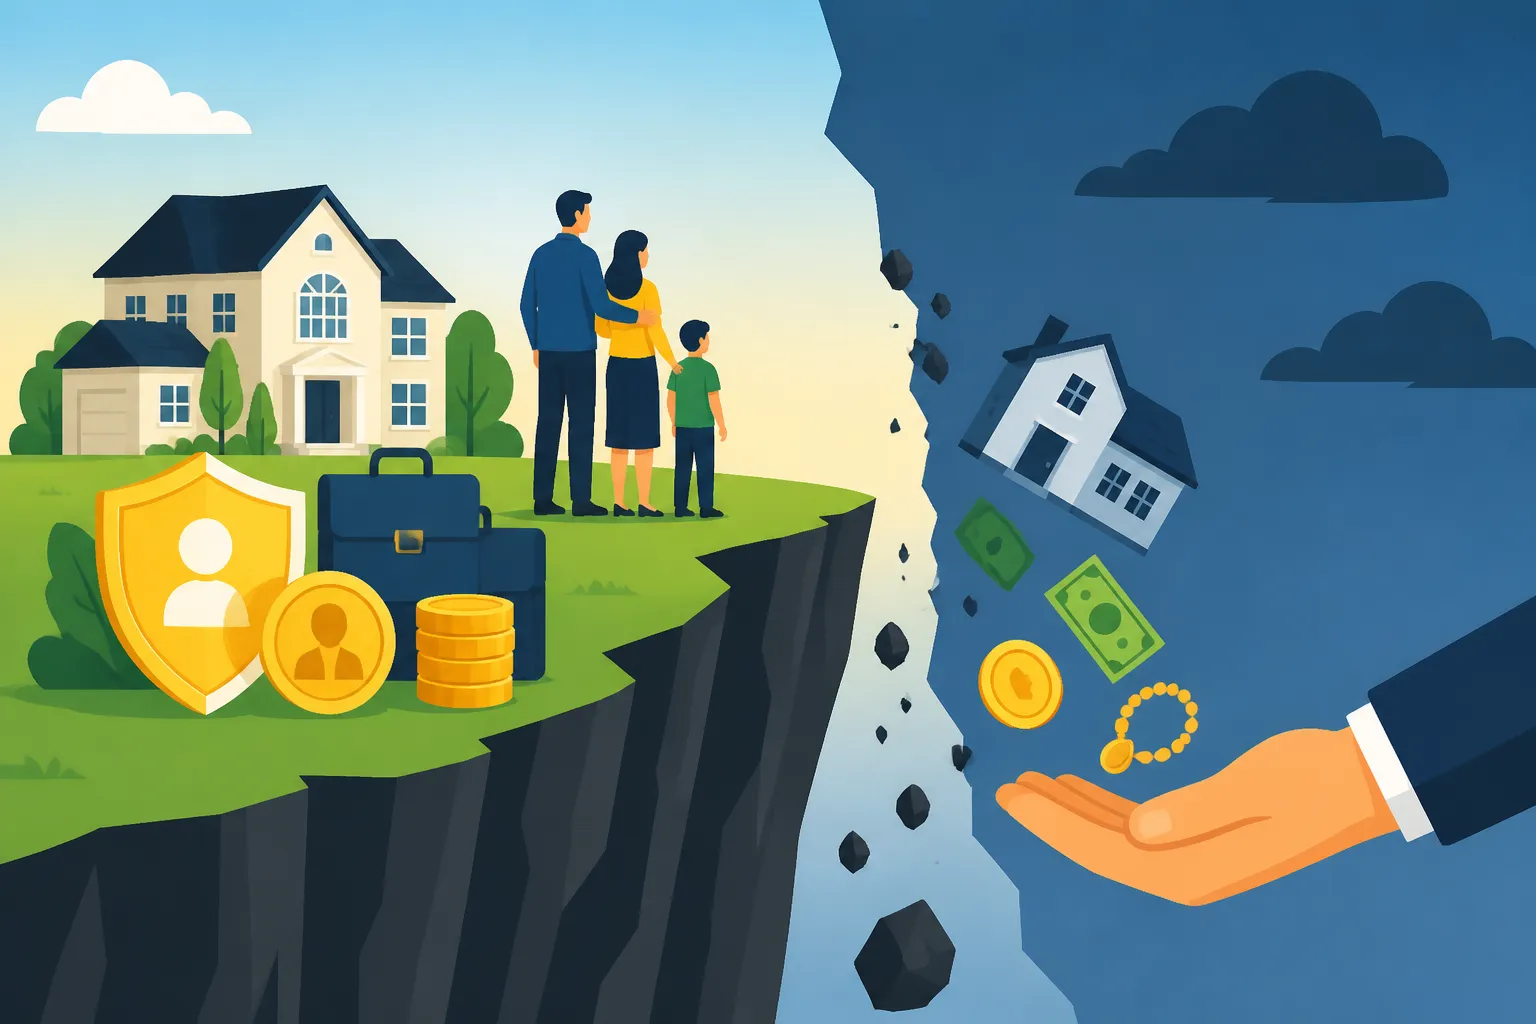
Imagine you are standing on a literal cliff. As long as you are one inch away from the edge, you are safe. But the moment you take that tiny, one-inch step over the line, you don't just descend a staircase; you fall the entire way down. In tax terms, this means that instead of only paying taxes on the amount over the limit, the state looks back and taxes your entire estate from the very first dollar. This can result in a tax bill that is actually larger than the amount by which you exceeded the limit.
The Difference Between a Threshold and a Cliff
In a standard threshold state, the exemption acts as a shield. If the exemption is $5 million and your estate is worth $5.1 million, you only owe taxes on that extra $100,000. It is manageable and predictable. Families in these states can breathe a bit easier knowing that a slight miscalculation in asset valuation won't lead to a financial catastrophe. You can look at State Estate Tax Exemptions & Rates Compared 2026 to see how different jurisdictions handle these limits.
A cliff, however, removes that shield entirely once you step over it. If the cliff is set at $5 million and your estate is valued at $5,000,001, the state ignores the exemption and taxes the full $5,000,001. The difference in the final tax bill between being $1 under the limit and $1 over the limit can be staggering. This structure creates a "danger zone" where having slightly more money actually leaves your heirs with significantly less.
Why Some States Choose This Structure
You might wonder why any state would implement such a punishing system. From a legislative perspective, estate tax cliffs are often a way to maximize revenue from moderately wealthy estates without technically lowering the exemption for everyone. It targets those who are "just wealthy enough" to cross the line but perhaps haven't engaged in the high-level tax planning that the ultra-wealthy use to shield their assets.
In states like New York, the cliff is a permanent fixture of the tax code designed to ensure that the largest estates contribute significantly to the state treasury. While it is often marketed as a tax on the rich, the reality is that the cliff can catch families who own a modest home in an expensive area like Brooklyn or Long Island, combined with a standard retirement account. Understanding How State Estate Tax Works is essential for anyone living in a cliff state because the rules are vastly different from the federal guidelines we see in the news.
The New York Estate Tax Cliff A Case Study
New York is the most famous example of the estate tax cliff, and it is where most people first encounter this concept. The New York system is particularly tricky because it doesn't just have a cliff; it has a "phase-out" that quickly turns into a total loss of the exemption. If your estate is within 105% of the New York State exemption amount, you might still get to keep some of your exemption. But the moment you exceed 105% of the threshold, the cliff hits with full force.
For families in Manhattan or the Hudson Valley, where property values have skyrocketed, hitting this 105% mark is easier than ever. It doesn't take a private jet or a massive portfolio; a well-funded 401(k) and a primary residence in a desirable ZIP code can easily push an estate into the danger zone. This is why many residents spend significant time learning How to Avoid the New York Estate Tax Cliff through aggressive gifting or trust structures.
How the NY Cliff Calculation Works
The math behind the New York cliff is enough to give anyone a headache. Let’s say the exemption is roughly $7 million. If your estate is worth $6.9 million, you owe $0 in state estate tax. Your heirs get everything. However, if your estate is worth $7.5 million, you have exceeded the 105% threshold. At this point, the $7 million exemption vanishes. New York will tax you on the full $7.5 million, starting from dollar one.
The tax rates in New York are graduated, but they climb quickly. On a $7.5 million estate, the tax bill could easily exceed $700,000. Think about that for a moment: by having an extra $600,000 in assets (the jump from $6.9 million to $7.5 million), your heirs actually end up with less money because the tax bill swallowed the entire gain and then some. Using tools on sites like SmartAsset can help you visualize these numbers, but the emotional weight of losing that much of a legacy is hard to quantify.
The 105 Percent Rule Explained
The 105% rule is New York’s way of creating a very steep ramp rather than a vertical drop, but for most people, it functions exactly like a cliff. If your estate is between 100% and 105% of the exemption, the state uses a specific formula to reduce your credit. It essentially "phases out" the exemption extremely rapidly. Once you are just 5% over the limit, the credit is gone entirely.
This narrow window creates a massive incentive for precise estate planning. Many families find themselves in a situation where they are worth $7.2 million and realize that by giving away $201,000 to a charity or a loved one, they can save $500,000 or more in taxes. It is one of the few areas of tax law where spending or giving away money actually makes you "richer" in the long run. To understand the specifics of the current year's numbers, you should check the New York Estate Tax Exemption 2026 details.
States That Currently Have an Estate Tax Cliff
While New York is the most prominent, it isn't the only jurisdiction where you need to watch your step. The landscape of state death taxes is constantly shifting as legislatures move to either attract retirees or bolster their budgets. For anyone planning their future, knowing Which States Have an Estate Tax in 2026? is the first step in deciding where to own property or claim residency.
Some states have "pseudo-cliffs" or structures that mimic the cliff's effect through high base taxes that kick in immediately upon crossing the exemption. Others have moved away from this model because it encourages wealthy residents to move to tax-friendly states like Florida or Texas. However, for those remaining in the Northeast or parts of the Midwest, the cliff remains a very real threat to multi-generational wealth.
Illinois and the Sliding Scale Cliff
Illinois has an estate tax that functions somewhat like a cliff because of how the tax is calculated using a federal credit that no longer exists in its original form. The Illinois exemption is currently set at $4 million, which is significantly lower than the federal level. Because the tax starts at a relatively high percentage once you cross that $4 million mark, the impact feels very much like a cliff for families who are just over the limit.
The frustration in Illinois often stems from the fact that the exemption has not been indexed for inflation in the same way the federal exemption has. This means that as home prices in the Chicago suburbs rise, more families are falling into the Illinois Estate Tax trap. It is a slow-motion cliff that is catching more people every year as the real value of that $4 million threshold continues to shrink.
Massachusetts and the Historical Context
Massachusetts recently made headlines by doubling its estate tax exemption from $1 million to $2 million. For years, Massachusetts had one of the most punishing cliffs in the country because the $1 million threshold was so easy to hit. Even now, with a $2 million exemption, the state still uses a system where if you exceed the limit, you are taxed on the entire value of the estate, though they have added a credit to soften the blow.
Before the recent changes, a modest home in Newton or Cambridge could easily put a family over the $1 million mark, triggering a tax on the whole estate. This led to a mass exodus of retirees. While the new $2 million limit is better, it still requires careful monitoring. You can read more about these specific mechanics in the Massachusetts Estate Tax guide to see how the "credit" system works to mitigate the cliff effect today.
| State | Exemption Type | Estimated Threshold (2026) | Cliff Effect Severity |
|---|---|---|---|
| New York | Total Cliff (105% rule) | ~$7.1 Million | High |
| Illinois | Fixed Threshold | $4 Million | Medium-High |
| Massachusetts | Credit-Modified Cliff | $2 Million | Medium |
| Rhode Island | Inflation-Indexed | ~$1.8 Million | Medium |
How the Estate Tax Cliff Affects Your Heirs
The real tragedy of the estate tax cliff isn't found in the tax forms; it's found in the family meetings where children realize they have to sell a childhood home or a family business just to pay the state. When an estate falls off the cliff, the tax bill is often due within nine months of the date of death. This creates a liquidity crisis. If the estate is made up of real estate or a private company, there might not be enough cash in the bank to cover a $500,000 tax bill triggered by a $1 overage.
Families often feel a sense of betrayal when they realize the state is taking a massive cut of assets that were already taxed when the money was earned. This is why validating these frustrations is so important. It doesn't feel like a "fair share" when the tax is triggered by a technicality. This is also why many people ask, Does My House Count Toward State Estate Tax?, and unfortunately, the answer in almost every cliff state is a resounding yes.
The Financial Impact of Going Over
Let’s look at a hypothetical scenario in a state with a $5 million cliff. Family A has an estate of $4,990,000. They pay $0 in tax and pass the full amount to their children. Family B has an estate of $5,010,000. Because they are $10,000 over the cliff, the state taxes the full $5.01 million. At an average state rate of 10%, Family B owes $501,000.
After taxes, Family A’s heirs have $4,990,000. Family B’s heirs have $4,509,000. By having "more" money, Family B actually ended up with $481,000 less than Family A. This "dead zone" is the most punishing aspect of the cliff. It turns traditional financial advice on its head; in this specific range, saving more money actually hurts your family.
Case Scenario: A $50,000 Mistake
Consider a family in New York that meticulously planned to stay just under the exemption. They had gifted money away and monitored their stock portfolio daily. However, a small, forgotten life insurance policy with a $50,000 death benefit pushed them over the 105% threshold. Because they didn't realize that Does Life Insurance Count Toward Estate Tax?, that $50,000 policy triggered a tax bill that wiped out over $600,000 of other assets.
This is why "valuation" is the most dangerous part of the process. If the state's appraiser decides your house is worth $100,000 more than your appraiser did, you could be pushed over the cliff posthumously. There is no way for the deceased to fix it, and the heirs are left with the bill. It highlights the need for a significant "buffer" between your net worth and the cliff's edge.
Strategies to Avoid Falling Off the Cliff
The good news is that because the cliff is so predictable in its mechanics, it is also avoidable with the right planning. The goal is to ensure that your "taxable estate" stays firmly on the safe side of the line. This often involves a shift in mindset from "growing wealth" to "preserving and transferring wealth."
Most strategies involve reducing the size of your estate while you are still alive. This can be done through direct gifting, the use of specialized trusts, or even charitable donations that kick in if the estate exceeds a certain value. Using a platform like SmartAsset can help you run "what-if" scenarios to see how much you need to move out of your estate to stay safe.
Gifting Strategies to Lower the Gross Estate
The simplest way to stay away from the cliff is to give your money away while you are still here to see your loved ones enjoy it. The federal government allows for an annual gift tax exclusion, which is expected to be around $19,000 per person in 2026. If a married couple has three children and six grandchildren, they could potentially move hundreds of thousands of dollars out of their estate every year without even touching their lifetime exemption.
However, you have to be careful with "deathbed gifts." Some states, like Minnesota, have a "three-year add-back" rule. If you give away money and then pass away within three years, the state drags that money back into your estate for tax calculation purposes. You can learn more about this in the Minnesota Estate Tax section. New York also has a similar add-back rule for gifts made within three years of death, making early planning essential.
Using Trusts to Stay Below the Threshold
Trusts are the heavy machinery of estate planning. By moving assets into an irrevocable trust, you effectively remove them from your ownership. If you don't own them, the state can't tax them when you die. A Revocable Living Trust Explained is great for avoiding probate, but it usually doesn't help with estate taxes because you still control the money. To beat the cliff, you often need something more permanent.
For example, a Qualified Personal Residence Trust (QPRT) can be used to move a high-value home out of your estate while allowing you to keep living in it for a set number of years. If you live past the term of the trust, the house is not counted toward the cliff. This is a common tactic for families with valuable real estate in places like Long Island or Westchester. Understanding How to Reduce or Avoid State Estate Tax through these vehicles is often the difference between a massive tax bill and a tax-free transfer.
Comparing State and Federal Estate Tax Structures
It is important to remember that the state estate tax cliff is a completely separate beast from the federal estate tax. For decedents who die in 2026, the basic exclusion amount is $15,000,000. Even if you are nowhere near the federal limit, you could be staring right at a state cliff.
This "stacking" of taxes is where many people get confused. They hear on the news that "estate taxes only affect the top 0.1%," which might be true at the federal level. But at the state level, in places like Oregon or Massachusetts, the tax can hit the top 10% or even 20% of households. You need to understand State vs Federal Estate Tax: How They Stack to get a full picture of your liability.
States With Graduated Exemptions vs Cliffs
Not all states are as "all-or-nothing" as New York. Some states have a more traditional progressive tax. In these states, the exemption is a true "bottom-level" shield. You only pay tax on the excess. This makes the planning much less stressful because a $10,000 error only costs you a few hundred dollars in tax, not a few hundred thousand.
When looking at Estate Tax on a $10 Million Estate by State, the difference in the cliff states is obvious. A $10 million estate in a cliff state will almost always pay significantly more than a $10 million estate in a "true exemption" state, even if the base tax rates are similar. The loss of that first $6 or $7 million of tax-free space is a massive financial blow.
How Inflation Indexing Changes the Landscape
One of the few silver linings in estate tax law is inflation indexing. Some states automatically raise their cliff threshold every year to keep up with the cost of living. This prevents "bracket creep," where families are pushed over the cliff simply because their home value went up with inflation, not because they actually got wealthier in real terms.
Understanding How Estate Tax Exemptions Are Indexed for Inflation can help you project where the cliff will be in five or ten years. If your state doesn't index for inflation (like Illinois), you are essentially facing a cliff that gets closer and closer to you every year. This makes proactive planning, such as using SmartAsset's inflation-adjusted calculators, even more critical for long-term security.
Common Misconceptions About Estate Tax Cliffs
There is a lot of misinformation out there, and in the world of estate taxes, bad advice can be expensive. One common myth is that you can simply "hide" assets or that the state won't find out about that out-of-state bank account. In reality, the probate process and the filing of a final income tax return make it very easy for state revenue departments to identify the full scope of an estate.
Another misconception is that the cliff only applies to residents. If you live in Florida (which has no estate tax) but own a $3 million brownstone in Brooklyn, you could still be subject to the New York estate tax cliff on that property. This "non-resident" tax is a major trap for snowbirds. You should check the rules for Estate Tax for Residents vs Nonresidents to see how your specific situation is handled.
The I am Only a Little Bit Over Myth
I often hear people say, "I'm only $50,000 over the limit, surely the state won't tax the whole thing for such a small amount." As we've discussed, the law is the law. There is no "mercy" provision in a cliff structure. The state's computer system doesn't care if you are $1 over or $1 million over; once the box is checked that the estate is "taxable," the full calculation is triggered.
This is why many attorneys suggest a "disclaimer" provision in a will. This allows a beneficiary to refuse part of an inheritance, which can sometimes be used to keep the estate just below the cliff. It's a complex maneuver, but it shows the lengths families must go to to avoid the "all-or-nothing" nature of the tax.
Does Life Insurance and Retirement Count
Yes, in most states, everything you "own" at the moment of death counts toward the cliff. This includes your home, your cars, your jewelry, your retirement accounts (IRA/401k), and the full face value of your life insurance policies. Many people think life insurance is "tax-free," and while it is usually free of income tax, it is absolutely included in the estate tax calculation.
If you have a $2 million life insurance policy to "protect your family," you might actually be creating a $300,000 tax bill by pushing your estate over the cliff. This is why many high-net-worth individuals use an Irrevocable Life Insurance Trust (ILIT). By having the trust own the policy, the payout stays off your personal balance sheet and doesn't count toward the cliff. You can find more about this in the Does Life Insurance Count Toward Estate Tax? guide.
Working With Financial Tools and Professionals
Navigating the estate tax cliff is not a DIY project. The stakes are simply too high. A single mistake in how a deed is titled or how a beneficiary is named can trigger a massive tax event. You need a team that understands the hyper-local nuances of your state's laws, especially in complex states like New York or Maryland (which is The Only State With Both Estate & Inheritance Tax).
Utilizing technology is a great first step. Using SmartAsset to model your net worth and potential tax liability can give you a baseline. It helps you walk into an attorney's office with a clear picture of your "danger zone." From there, a professional can help you draft the specific language needed to keep your heirs safe.
Using Calculators Like SmartAsset for Planning
SmartAsset and similar financial tools are excellent for "stress-testing" your estate plan. You can plug in your current assets, assume a 5% annual growth rate, and see exactly when you are likely to hit the cliff. This allows you to start gifting programs years before the tax becomes a real threat.
For example, if you see that you will hit the New York cliff in seven years, you can start making annual exclusion gifts today. By the time you reach that seven-year mark, you may have moved $500,000 out of your estate, keeping you safely in the tax-free zone. The key is to be proactive rather than reactive.
The Value of an Estate Attorney
While online tools are great for broad strokes, an estate attorney provides the "fine-tuning." They can help you navigate the specific "add-back" rules and "clawback" provisions that vary from state to state. They also ensure that your State Estate Tax Returns: Forms & Deadlines are handled correctly, as the penalties for late filing can be almost as bad as the tax itself.
A good attorney will also help you consider the "human" side of the cliff. They can facilitate the conversations between parents and children about why money is being moved into trusts or why a family home might need to be retitled. This transparency prevents resentment and ensures everyone is on the same page regarding the preservation of the family's legacy.
Disclaimer
This guide is for informational purposes only and does not constitute legal, financial, or tax advice. Estate tax laws, exemptions, and "cliff" thresholds are subject to frequent changes at both the state and federal levels. You should consult with a qualified estate planning attorney or tax professional to discuss your specific circumstances and ensure your plan complies with the most current regulations in your jurisdiction.