Do You Pay Estate Tax on a Primary Residence?
Many families spend decades diligently paying off a mortgage, only to face the terrifying realization that their most cherished asset—the family home—might be subject to a massive tax bill upon their death. The fear that your children might have to sell the house just to satisfy the IRS is a heavy burden to carry. This guide provides a deep dive into how estate taxes affect your primary residence, helping you navigate exemptions, valuations, and protective strategies to keep your legacy intact.
Understanding How Your Home Fits Into the Gross Estate
When the government looks at your financial life after you pass away, they don't just look at your bank accounts or your stock portfolio. They look at everything you own, which is collectively referred to as your "gross estate." Your primary residence is almost always the largest single asset in that calculation. Many people mistakenly believe that because a home is a personal residence and not an investment property, it is somehow shielded from the taxman. Unfortunately, that is not the case. The IRS views your home as equity that can be taxed just like a bar of gold or a share of Apple stock.
Fair Market Value vs. Purchase Price
One of the most common points of confusion for homeowners is the difference between what they paid for their home and what it is worth today. For estate tax purposes, the purchase price is completely irrelevant. The IRS is interested in the "Fair Market Value" of the property on the date of your death. If you bought a home in the suburbs of Seattle in 1985 for $100,000 and it is now worth $1.8 million, it is the $1.8 million figure that counts toward your estate tax threshold.
This valuation can be a double-edged sword. While it’s great for your net worth, it can push an otherwise modest estate over the tax-free limits. Understanding What Is the Gross Estate? is the first step in realizing how close you might be to the tax line. To get an accurate picture, many families use tools like SmartAsset to track their home equity alongside their liquid investments. Seeing these numbers in one place often provides the wake-up call needed to start serious estate planning.
The Inclusion of Real Estate Assets
Your primary residence isn't the only property that gets counted. If you have a vacation cabin in the Cascades or a small condo in Florida, those values are added to your primary residence's value. The cumulative total of all real estate holdings often surprises people, especially in high-growth markets where property values have outpaced inflation for years.
When calculating these values, you must also consider any improvements or additions you've made. That $150,000 kitchen remodel or the ADU you built in the backyard doesn't just make the house nicer to live in; it increases the taxable value of the estate. Because real estate is illiquid—meaning you can’t easily slice off a bedroom to pay a tax bill—it poses a unique challenge for heirs who may not have the cash on hand to pay taxes on a multi-million dollar property.
Federal Estate Tax Thresholds and Your Residence
The good news for the majority of Americans is that the federal estate tax exemption is currently very high. For people who die in 2026, the federal basic exclusion amount is $15,000,000, and it is indexed for inflation starting in 2027. This still deserves attention from anyone whose home value has skyrocketed over the last decade.
The 2026 Sunset and Its Impact
The Federal Estate Tax Exemption 2026 ($15 Million) is a topic of intense discussion among planners. While $15 million (indexed for inflation starting in 2027) sounds like a lot, the concern is what happens if the laws change in the future. For a couple living in a high-cost area like San Francisco or New York, a primary residence worth $4 million, combined with retirement accounts and life insurance, can quickly approach the thresholds that were common a decade ago.
Imagine a family where the parents were successful professionals. They have a $3 million home, $4 million in 401(k)s, and $2 million in life insurance. Today, they are safe. But if the exemption drops back to the $5 million or $7 million range (adjusted), they are suddenly in the crosshairs. Using a platform like SmartAsset can help you run scenarios based on different exemption levels to see where your "safety zone" really lies. It is far better to plan for a lower exemption now than to be caught off guard when the laws shift.
Portability for Married Couples
One of the most powerful tools for homeowners is something called "portability." This allows a surviving spouse to use any portion of the deceased spouse's unused estate tax exemption. This is crucial because it effectively doubles the amount of equity a couple can pass on tax-free. For example, if a husband passes away and leaves everything to his wife, his entire exemption can be "ported" to her.
However, don't assume this happens automatically. The executor of the first spouse's estate must file a federal estate tax return (Form 706) to elect portability, even if no tax is due. This is a trap that many families fall into. They think, "Oh, we don't owe any taxes, so why file the paperwork?" Years later, when the second spouse passes away and the house has doubled in value again, the family realizes they missed out on millions of dollars of tax protection because they didn't file a simple form. This is why Estate Tax Portability and Why Most States Don't Offer It is such an important concept to master.
State-Level Estate Taxes: Where the Rules Change
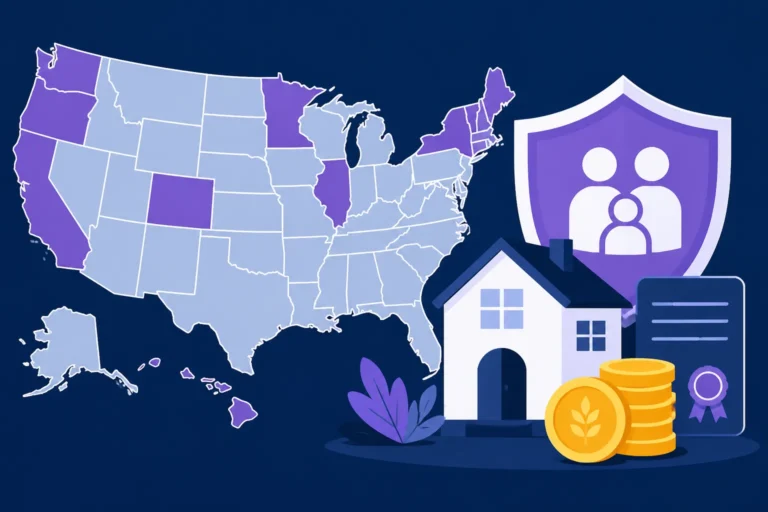
While you might be safe from the federal government, your state might be a different story. This is where many homeowners get blindsided. Several states have their own estate taxes with exemptions that are much, much lower than the federal level. In some places, simply owning a nice house in a good school district is enough to trigger a state-level tax.
States with Independent Estate Tax Laws
States like Oregon, Massachusetts, and Washington have some of the lowest estate tax exemptions in the country. In Oregon, for instance, the exemption is only $1 million. If you own a home in Portland worth $800,000 and have $300,000 in your retirement account, your estate is already over the limit. You can check Which States Have an Estate Tax in 2026? to see if your home is located in one of these jurisdictions.
The frustration here is real. You’ve paid property taxes for 30 years, and now the state wants another cut just because you decided to stay in your home. This "double taxation" feeling is what drives many retirees to move to states with no estate tax. But for those who want to stay close to family, understanding how Does My House Count Toward State Estate Tax? is vital. You need to know exactly how your state treats real estate, especially if it’s held in a trust or has a mortgage.
| State | 2026 Estimated Exemption | Top Tax Rate |
|---|---|---|
| Federal | ~$15 Million | 40% |
| Oregon | $1 Million | 16% |
| Massachusetts | $2 Million | 16% |
| Washington | ~$2.19 Million | 20% |
| New York | ~$7 Million | 16% |
The Risk of the "Cliff" in Specific States
Some states, most notably New York, have what is known as a "tax cliff." This is a particularly brutal rule where if your estate exceeds the exemption by just a small amount (usually 5%), you lose the exemption entirely. The state then taxes the entire estate from dollar one.
Think about how this affects a homeowner. If the exemption is $6.58 million and your estate is worth $7 million because your house appreciated more than expected, you could owe hundreds of thousands of dollars in taxes that you wouldn't have owed if your estate were just $400,000 smaller. This makes The Estate Tax Cliff Explained (New York & More) essential reading for anyone in the Tri-State area. It’s a situation where "doing too well" with your home's value can actually cost your heirs a fortune.
Strategies to Protect the Family Home from Estate Taxes
If you realize that your primary residence is going to put you over the tax threshold, don't panic. There are several legal and effective ways to reduce the taxable value of your home or remove it from your estate entirely while you are still living there.
Utilizing Trusts for Residence Protection
A common strategy is to move the home into a trust. Not all trusts are created equal, however. A Revocable Living Trust is great for avoiding probate, but it does absolutely nothing to reduce your estate taxes because the IRS still considers you the owner of the assets. To save on taxes, you usually have to look at irrevocable options.
By using an irrevocable trust, you are essentially giving away the home to the trust beneficiaries (usually your children) while potentially retaining certain rights. This removes the future appreciation of the home from your taxable estate. For many, How to Avoid Estate Tax With Trusts is the gold standard of planning. You might also want to consult with a professional at a firm like SmartAsset to see how shifting assets into a trust changes your long-term financial projections. It’s about finding the balance between tax savings and maintaining your lifestyle.
Qualified Personal Residence Trusts (QPRT)
A QPRT Explained is a specific type of irrevocable trust designed solely for your primary residence or a second home. Here’s how it works: You transfer your home to the trust but retain the right to live in it for a set term of years (say, 10 or 15 years). Because you are keeping the right to live there, the value of the "gift" to your children is discounted.
If you outlive the term of the trust, the house passes to your children at that discounted value, and all the appreciation that happened during those years is tax-free. If the house was worth $1 million when you started and $2 million when the term ends, you’ve effectively moved $2 million out of your estate while only using a small fraction of your gift tax exemption. The "catch" is that after the term ends, you must pay your children fair market rent to keep living there. While that sounds odd, it’s actually another way to move money to your kids tax-free!
Deductions and Exemptions That Might Apply
Before you assume you'll owe a massive bill, it's important to look at the deductions that can shrink your taxable estate. The IRS allows you to subtract certain things from the total value of your property before the tax rate is applied.
The Unlimited Marital Deduction
The biggest "free pass" in the tax code is the unlimited marital deduction. You can leave a home of any value—even a $100 million mansion—to a spouse who is a U.S. citizen without paying a single cent in federal estate tax. This provides immense peace of mind for the surviving spouse, ensuring they won't be kicked out of their home by a tax bill.
However, this only delays the problem; it doesn't solve it. When the second spouse dies, the home will be taxed if it exceeds the exemption at that time. This is why understanding State vs Federal Estate Tax: How They Stack is so important. The marital deduction is a powerful tool, but it requires a "second step" of planning to ensure the children aren't the ones left holding the bill later on.
Charitable Giving and Real Estate
If you don't have heirs or if you are philanthropically minded, you can leave your home (or a portion of it) to a qualified charity. This creates a charitable deduction that can wipe out the estate tax entirely. Some homeowners choose a "Retained Life Estate," where they deed the house to a charity now but keep the right to live there for the rest of their lives.
This gives you an immediate income tax deduction while you are alive and removes the house from your estate for tax purposes when you pass. It’s a beautiful way to ensure your home eventually supports a cause you care about, like a local university or a housing non-profit, while solving a looming tax problem.
Practical Considerations: Valuations and Appraisals
When the time comes to settle an estate, the value of the home isn't just "what Zillow says." The IRS has very strict rules about how a primary residence must be valued, and getting this wrong can lead to audits or overpaying.
Obtaining a Date-of-Death Appraisal
Your heirs will need to hire a professional, certified appraiser to determine the value of the home as of the exact date of your death. This is critical because of the Stepped-Up Basis Explained rule. When your heirs inherit the home, their "cost basis" becomes the value on the date of your death. If they sell the house shortly after for that same value, they owe zero capital gains tax.
A proper appraisal is a robust document that looks at "comps" (comparable sales) in the neighborhood, the condition of the home, and local market trends. Don't rely on a real estate agent’s "Broker Price Opinion." For the IRS, you want a formal appraisal to back up the numbers on the estate tax return. This protects the heirs from future headaches if the IRS decides to challenge the valuation.
Impact of Mortgages on Taxable Value
One silver lining is that the IRS taxes your equity, not the total value of the home. If your primary residence is worth $2 million but you still have a $1.2 million mortgage on it, only the $800,000 of equity counts toward your gross estate. This is a vital distinction for younger homeowners or those who have recently refinanced.
When calculating your potential liability, always subtract your outstanding mortgage balance, home equity lines of credit (HELOCs), and any other liens against the property. Using a comprehensive planner like SmartAsset can help you keep track of your decreasing mortgage and increasing equity, so you always know your "taxable exposure." For many, the mortgage acts as a natural "tax shield" during the years when their liquid assets are also growing.
State Estate Tax Exemptions and Rates Compared 2026
To help you visualize the landscape, here is a comparison of how different states handle the exemption for a primary residence and other assets. Keep in mind that these numbers are subject to legislative changes.
| Jurisdiction | Exemption Amount | Rate Range | Key Feature |
|---|---|---|---|
| Federal | ~$15,000,000 | 18% – 40% | Indexed for inflation |
| Connecticut | Matches Federal | 12% | Only state to match Federal |
| Illinois | $4,000,000 | 0.8% – 16% | Not indexed for inflation |
| Maine | $6,410,000 | 8% – 12% | Indexed for inflation |
| Maryland | $5,000,000 | 0.8% – 16% | Only state with both Estate & Inheritance tax |
| Rhode Island | $1,838,056 | 0.8% – 16% | Very low threshold for high-value homes |
As you can see, the state you choose to call home has a massive impact on whether your primary residence will be taxed. A $3 million home in Connecticut is currently "safe" from state estate tax, whereas that same home in Illinois or Rhode Island would trigger a significant bill. This is why many people engage in "domicile planning"—carefully establishing residency in a more tax-friendly state while perhaps keeping their original home as a secondary residence (though this requires careful legal navigation).
Final Thoughts on Protecting Your Home
At the end of the day, your home is more than just an asset; it’s the backdrop of your life's best memories. The idea of it being treated as a taxable line item feels cold and clinical, but by facing the reality of estate taxes head-on, you can take the steps necessary to protect it. Whether it's through a QPRT, utilizing portability, or simply staying informed about state-specific cliffs, you have the power to influence how much of your hard-earned equity stays with your family. The best time to protect your home was yesterday; the second best time is today.
Disclaimer
This guide is for informational purposes only and does not constitute legal, financial, or tax advice. Estate tax laws are subject to frequent changes at both the federal and state levels. Always consult with a qualified estate planning attorney or tax professional to discuss your specific situation and ensure your plan complies with current regulations.