How Much Can You Inherit Before State Estate Tax?
It's completely normal to feel a wave of confusion, and maybe even a little dread, when you start thinking about the taxes that might apply to an inheritance. You've just experienced a significant loss, and now you're faced with complex financial questions like "How much can you inherit before state estate tax?" This guide is here to untangle the intricacies of state estate taxes, helping you understand which states impose them, what the exemption amounts are, and how these taxes might impact the assets you inherit or plan to leave behind.
Understanding State Estate Taxes: More Than Just Federal Rules
When we talk about taxes on a deceased person's wealth, there's often a lot of overlap and confusion between federal and state regulations. It’s not just about the big picture; the smaller, state-level details can make a huge difference in what beneficiaries ultimately receive. Many people mistakenly believe that if an estate isn't large enough to trigger federal estate tax, they're completely in the clear. However, several states have their own distinct estate taxes, which kick in at much lower thresholds.
The Key Difference: Estate Tax vs. Inheritance Tax
Before we dive deeper, it's crucial to clarify a common point of confusion: the difference between an estate tax and an inheritance tax. While both are "death taxes," they actually tax different entities and operate in fundamentally different ways.
An estate tax is levied on the total value of a deceased person's estate before any assets are distributed to heirs. Think of it as a tax on the right to transfer property at death. The estate itself is responsible for paying this tax, and it's typically paid from the estate's assets before beneficiaries receive anything. For instance, if an estate is valued at $5 million and the state estate tax exemption is $3 million, the tax would apply to the $2 million that exceeds the exemption. This means the overall pool of assets available for distribution to heirs is reduced. If you're looking to understand this more thoroughly, you might want to read our comprehensive article on Estate Tax vs Inheritance Tax: What's the Difference?.
On the other hand, an inheritance tax is levied on the beneficiary after they receive assets from an estate. This is a tax on the right to receive property. The amount of tax a beneficiary pays often depends on their relationship to the deceased and the value of the inheritance. Close relatives, like spouses and children, are usually exempt or pay very low rates, while distant relatives or non-relatives often face higher rates. Currently, only a handful of states impose an inheritance tax: Iowa (though it's being phased out), Kentucky, Maryland, Nebraska, New Jersey, and Pennsylvania. Maryland is particularly unique as it's the only state that levies both an estate tax and an inheritance tax.
Federal vs. State Estate Tax: Why Both Matter (or Don't)
You've probably heard about the federal estate tax, which applies to very large estates. For 2026, the federal estate tax exemption is $15,000,000 per individual. This means that a single person's estate would need to exceed $15 million in value before any federal estate tax would be owed. For married couples, this exemption essentially doubles. Given these high thresholds, most people don't have to worry about the federal estate tax.
However, state estate taxes operate independently of the federal system. The rules for How State Estate Tax Works can vary wildly. A state might have an estate tax with an exemption that's significantly lower than the federal one, meaning an estate could be exempt federally but still owe state estate tax. For example, while the federal exemption is in the tens of millions, some states have exemptions as low as $1 million. This is why it's absolutely critical to understand the specific rules of the state where the deceased lived, and potentially where they owned property, regardless of whether federal estate tax is a concern. It’s also important to remember that the state estate tax rate can be quite substantial on the portion of the estate that exceeds the exemption.
Where Do State Estate Taxes Apply? Exemptions and Thresholds
Navigating the landscape of state estate taxes can feel like playing a game of "Where in the U.S. is Carmen Sandiego," but with your inheritance at stake. It's not a nationwide tax; it's a patchwork of individual state laws, each with its own rules, exemption amounts, and tax rates.
States That Impose an Estate Tax
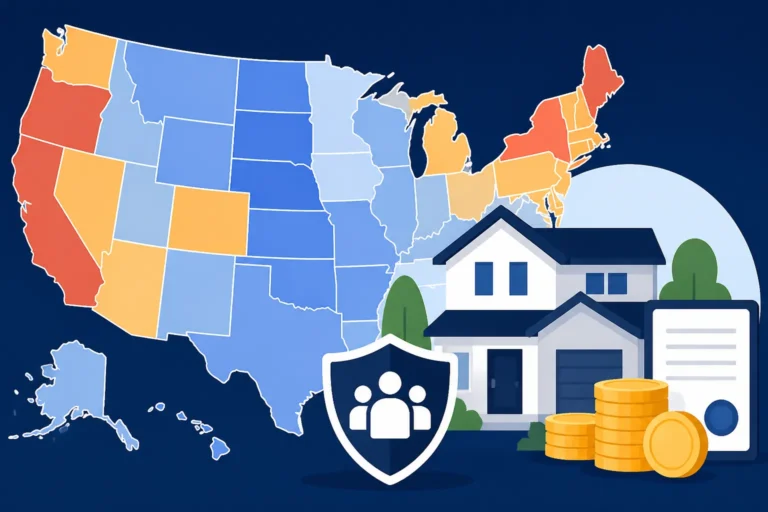
As of 2026, there are a baker's dozen of states, plus the District of Columbia, that impose their own estate tax. This means that if the deceased person was a resident of one of these states, or owned real estate or tangible personal property within one of these states, their estate might be subject to state-level taxation even if it falls well below the federal threshold.
These states are:
- Connecticut
- Hawaii
- Illinois
- Maine
- Maryland
- Massachusetts
- Minnesota
- New York
- Oregon
- Rhode Island
- Vermont
- Washington
- District of Columbia
It's important to note that this list can change. States occasionally repeal or modify their estate tax laws. For the most current information, it's always best to consult with an estate planning professional or reliable financial resources like SmartAsset's updated tax guides. Our detailed article, Which States Have an Estate Tax in 2026?, provides a comprehensive overview of each of these states.
The All-Important Exemption Amount
The exemption amount is the cornerstone of understanding how much you can inherit before state estate tax kicks in. This is the portion of the gross estate that is allowed to pass to beneficiaries free of state estate tax. Only the value exceeding this exemption amount is subject to taxation. These exemption amounts vary significantly from state to state and are typically much lower than the federal exemption.
For example, while some states like Connecticut align their estate tax exemption with the federal amount, others have much lower thresholds. Oregon and Massachusetts have an exemption of $1 million, meaning any estate value above that amount could be taxed. New York has an exemption $7,350,000 for 2026, but it also has a notorious "estate tax cliff" where if an estate slightly exceeds the exemption, the entire estate can become taxable, not just the excess. Understanding these specific exemption figures is crucial for proper estate planning. You can compare these figures directly in our guide on State Estate Tax Exemptions & Rates Compared 2026.
Here's a snapshot of some state estate tax exemptions for 2026 (subject to annual inflation adjustments):
| State | 2026 Estate Tax Exemption (Approx.) |
|---|---|
| Connecticut | ~$15 Million (Aligns with Federal) |
| Hawaii | $5.49 Million |
| Illinois | $4 Million |
| Maine | $6.8 Million |
| Maryland | $5 Million |
| Massachusetts | $2 Million |
| Minnesota | $3 Million |
| New York | ~$6.94 Million |
| Oregon | $1 Million |
| Rhode Island | ~$1.8 Million |
| Vermont | $5 Million |
| Washington | ~$2.19 Million |
| District of Columbia | $4 Million |
Note: These figures are approximations for 2026 and are subject to change based on inflation adjustments or legislative action.
The Impact of Residency on State Estate Tax
It's not just where the assets are located, but also where the deceased person resided that matters for state estate tax purposes. Each state has its own definition of residency for tax purposes, which can sometimes be complicated, especially for individuals who split their time between multiple states, like "snowbirds" who live in Florida for part of the year and New York for another.
If the deceased was a legal resident of an estate tax state, their entire estate, including assets held outside the state (except real estate in other states), could be subject to that state's estate tax. However, if they owned real property in a different estate tax state, that property might be subject to the estate tax of the state where the property is located, in addition to or instead of their primary residence state's tax. This is often referred to as "domiciliary" versus "ancillary" probate. It’s definitely a complex area, and one where the advice of a qualified professional is invaluable. Our article Estate Tax for Residents vs Nonresidents delves deeper into these specific residency nuances.
Calculating Your Potential State Estate Tax Liability
Understanding the rules is one thing, but actually figuring out what an estate might owe can feel like a daunting task. It involves more than just looking at the total dollar amount; you need to understand what counts, what doesn't, and how deductions play a role.
Defining Your Gross Estate
The first step in calculating any potential state estate tax is to determine the value of the "gross estate." This isn't just the cash in a bank account or the family home. The gross estate is a comprehensive tally of everything the deceased owned or had certain interests in at the time of their death. This can include:
- Real estate: The fair market value of all homes, land, and other properties. Our guide, Does My House Count Toward State Estate Tax?, offers further details on this.
- Bank accounts: Checking, savings, and money market accounts.
- Investments: Stocks, bonds, mutual funds, and other securities.
- Retirement accounts: IRAs, 401(k)s, and other retirement plans. However, depending on the beneficiary designation, these might be treated differently.
- Life insurance policies: If the deceased owned the policy and had incidents of ownership at the time of death, the death benefit is usually included in the gross estate. You can explore this further in Does Life Insurance Count Toward Estate Tax?.
- Personal property: Cars, jewelry, art, collectibles, and other valuable possessions.
- Business interests: Ownership stakes in businesses, partnerships, or sole proprietorships.
- Certain gifts: Some states have "look-back" periods for gifts made within a certain number of years before death, which might be added back to the estate for tax purposes (like Minnesota's 3-year gift add-back rule).
Essentially, if the deceased had a legal right to it or control over it, it's generally included in the gross estate. This total figure is the starting point before any exemptions or deductions are applied.
Applying Deductions and Exemptions
Once the gross estate is calculated, the next step is to subtract various deductions to arrive at the "taxable estate." These deductions can significantly reduce the amount subject to estate tax. Common deductions often include:
- Debts: Outstanding mortgages, loans, credit card balances, and other liabilities of the deceased.
- Funeral and administrative expenses: Costs associated with the funeral, burial, probate fees, attorney fees, appraisal fees, and executor commissions.
- Marital deduction: Assets left to a surviving spouse generally qualify for an unlimited marital deduction, meaning they pass tax-free to the spouse. This is a huge benefit for married couples. Read more about the Marital Deduction & Estate Tax.
- Charitable deduction: Bequests to qualifying charities are typically fully deductible.
After all applicable deductions are subtracted from the gross estate, you're left with the "adjusted gross estate." Then, the state's specific estate tax exemption amount is applied. If the adjusted gross estate is below the exemption, no state estate tax is owed. If it exceeds the exemption, only the amount above the exemption is subject to the state's tax rates. This is how you ultimately determine How Estate Tax Is Calculated.
Navigating State-Specific Rates and the "Cliff"
Each state with an estate tax has its own rate schedule, which can be progressive, meaning higher values are taxed at higher rates. For example, Washington State's estate tax rates range from 10% to 20%, while Oregon's has a range. These rates apply only to the portion of the estate that exceeds the state's exemption amount.
However, some states introduce an additional layer of complexity with what's known as an "estate tax cliff." New York is the most famous example of this. In New York, if an estate's value falls between 100% and 105% of the state's exemption amount, the exemption begins to phase out, and the estate is taxed on a sliding scale. But if the estate's value exceeds 105% of the exemption, the entire estate becomes taxable from dollar one, rather than just the amount above the exemption. This can lead to a dramatically higher tax bill for an estate that is only slightly over the exemption. Understanding and planning around the New York Estate Tax Cliff Explained is critical for residents of that state. This is precisely why it’s so important to have a clear picture of your total estate value and consult with experts. A reputable service like SmartAsset can help you connect with financial advisors who specialize in estate planning in your state.
Strategies to Plan for State Estate Tax
Even if your estate might be subject to state estate tax, it's not a done deal. There are proactive steps you can take during your lifetime to potentially reduce or even eliminate the burden on your beneficiaries. Strategic planning can make a world of difference in what your loved ones ultimately inherit.
Leveraging Trusts and Gifting Strategies
One of the most powerful tools in estate planning is the use of trusts. A well-structured trust can help remove assets from your taxable estate, thereby reducing or even avoiding state estate tax.
- Irrevocable Trusts: When you transfer assets into an irrevocable trust, you generally give up control over those assets. Because they no longer legally belong to you, they are typically excluded from your taxable estate upon your death. There are many types of irrevocable trusts, such as an Irrevocable Life Insurance Trust (ILIT), which can hold a life insurance policy and keep the death benefit out of your estate, or a Qualified Personal Residence Trust (QPRT) for your home. Our article, How to Avoid Estate Tax With Trusts, explores these options in detail.
- Revocable Living Trusts: While a revocable living trust doesn't typically remove assets from your taxable estate for estate tax purposes (because you retain control), it's excellent for avoiding probate, which can save time and money for your heirs. It also provides privacy, as probate records are public.
- Gifting Strategies: Making gifts during your lifetime can reduce the size of your taxable estate. Each year, you can gift up to the annual gift tax exclusion amount (which is $19,000 per recipient in 2026) without using up any of your lifetime gift tax exemption. A married couple can effectively gift $38,000 to each recipient per year. Gifts made in excess of this annual exclusion amount will tap into your federal lifetime gift and estate tax exemption, but they still get assets out of your estate. It's crucial to understand state-specific gift tax rules, as a few states have their own. For example, Connecticut has a state-level gift tax. Always be mindful of the rules, and consider discussing gifting with a financial advisor to ensure it aligns with your overall estate plan. You can also explore Does Gifting Reduce State Estate Tax? for more insights.
Regular Review and Professional Guidance
Estate planning isn't a "set it and forget it" task. Tax laws change, your financial situation evolves, and your family circumstances shift. What was once an effective strategy might become outdated or less efficient over time.
It's highly advisable to review your estate plan every few years, or whenever a significant life event occurs, such as a marriage, divorce, birth of a child or grandchild, or a substantial change in wealth. This includes checking your beneficiary designations on retirement accounts and life insurance policies, as these typically bypass probate and go directly to the named beneficiaries, but their value can still be included in your gross estate for tax calculations.
Working with experienced professionals – an estate planning attorney, a tax advisor, and a financial planner – is paramount. They can provide personalized advice based on your specific assets, family dynamics, and the laws of your state. They can help you craft a plan that minimizes tax liabilities, ensures your wishes are carried out, and protects your loved ones from unnecessary financial burdens. SmartAsset offers tools that can connect you with fiduciary financial advisors in your area, who can provide expert guidance tailored to your unique situation. Seeking this kind of professional insight is the best way to ensure that your legacy is preserved as you intend, rather than being eroded by avoidable taxes. Our guide on How to Reduce or Avoid State Estate Tax offers additional actionable steps.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.