Oregon Estate Tax Exemption 2026
Many families in the Pacific Northwest are surprised to discover that Oregon has one of the most aggressive estate tax structures in the United States. While federal limits are high, the Oregon Estate Tax Exemption 2026 remains locked at a surprisingly low threshold, often catching middle-class homeowners off guard. This guide clarifies how the tax works, who is vulnerable, and how to protect your family's hard-earned legacy.
Understanding the Oregon Estate Tax Landscape in 2026
When we talk about the Oregon Estate Tax Exemption 2026, the number that usually causes a bit of a gasp is $1 million. For a lot of folks living in places like Portland, Eugene, or Bend, reaching a $1 million net worth isn't as "elite" as it used to be. If you have owned a home in the Pearl District or Lake Oswego for a decade and have been Diligently contributing to your 401(k), your estate is likely already knocking on the door of this tax. Unlike the federal government, which adjusts its limits for inflation, Oregon has kept its exemption static for years, which means more and more families find themselves in the taxable category every year.
It is vital to realize that this is a "transfer tax" on your right to leave property to your heirs. It is not an income tax, and it is not an inheritance tax paid by the person receiving the money. If you are trying to figure out Estate Tax vs Inheritance Tax: What's the Difference?, remember that in Oregon, the tax is pulled out of the estate's bucket before the heirs get their share. This distinction matters because it places the burden of planning squarely on the shoulders of the person creating the estate plan, rather than the beneficiaries.
The disconnect between state and federal rules is often where the most confusion happens. When people use tools like SmartAsset to look at their retirement readiness, they might see a massive federal exemption and breathe a sigh of relief. However, the federal government and the state of Oregon are playing by entirely different rulebooks. While the Federal Estate Tax Exemption 2026 ($15 Million) is quite generous, Oregon will still start taking a cut once you cross that first $1 million. This means you could be completely exempt from federal taxes but still owe the Oregon Department of Revenue hundreds of thousands of dollars.
Why the $1 Million Exemption is a Unique Challenge
In the world of estate planning, $1 million is a relatively low bar. Many residents don't realize that the "Gross Estate" includes everything: your home, your cars, your life insurance death benefits, your retirement accounts, and even your personal belongings like jewelry or art. If you are a business owner in the Willamette Valley or own a few acres of timberland in Douglas County, those assets can push you over the limit faster than you’d think. People often ask, Does My House Count Toward State Estate Tax?, and the answer is a resounding yes. In fact, for many Oregonians, the home is the primary asset that triggers the tax.
Another complicating factor is that Oregon does not currently offer "portability" between spouses. On the federal level, if one spouse dies and doesn't use their full exemption, the surviving spouse can "inherit" that unused portion. In Oregon, if you don't use it, you lose it. This is a massive trap for married couples who leave everything to each other. When the first spouse dies, no tax is paid because of the marital deduction, but that first $1 million exemption is often wasted. When the second spouse dies, they only have their own $1 million exemption to protect the combined assets of both people.
The Lack of Inflation Adjustment
One of the most frustrating aspects for local taxpayers is that the $1 million threshold is not indexed for inflation. While the cost of living in the Pacific Northwest has skyrocketed, the tax floor has stayed the same. This creates a "bracket creep" effect where families who would have been considered middle-class twenty years ago are now being taxed like the wealthy. Using a resource like SmartAsset can help you run the numbers on your current net worth, but it won't change the fact that Oregon's legislature hasn't moved the needle on this exemption in a very long time.
Because of this, many people are looking into Oregon Estate Tax ($1 Million Exemption) specifics to see if there are any legislative changes on the horizon. As of 2026, the status quo remains, making it essential to have a plan that accounts for this low ceiling. If your estate is valued at $1.5 million, you are paying tax on the $500,000 over the limit; the way the math works out can be surprisingly complex, often requiring a professional to navigate the OR-706 tax form.
How Oregon Estate Tax is Calculated
Understanding the math behind the tax is the first step in minimizing it. Oregon uses a progressive tax rate that starts at 10% and goes up to 16%. The tax applies only to the amount over $1 million, and the rate steps up as the taxable amount grows. It is a bit like a steep staircase—once you step onto that first $1 million landing, the next steps are quite expensive.
When you are looking at How State Estate Tax Works in Oregon, you have to look at the "Taxable Estate," which is your gross estate minus certain deductions like debts, funeral expenses, and gifts to charity. If you are a resident of Oregon, the state taxes all of your property, no matter where it is located, except for real estate or tangible personal property located in another state. Conversely, if you live in another state but own a vacation home on the Oregon Coast or a rental property in Bend, Oregon will want a piece of that property’s value.
The Progressive Rate System
The rates in Oregon are among the highest in the country for state-level estate taxes. The 10% starting rate is significantly higher than the starting rates in many other states that still have an estate tax. For those with larger estates, the 16% top rate applies to amounts over $9.5 million. While that might seem like a "high-class problem," the reality is that a 10% tax on a $2 million estate results in a $100,000 bill to the state. That is money that could have gone to a grandchild's college fund or a local charity.
To get a clear picture of what you might owe, it is helpful to look at State Estate Tax Exemptions & Rates Compared 2026. Oregon consistently sits at the bottom of the list for exemption amounts, alongside states like Massachusetts. This puts Oregonians at a distinct disadvantage compared to neighbors in Washington, where the exemption is over $2 million, or California and Nevada, which have no state estate tax at all. Many people use SmartAsset to compare the tax burdens of different states before deciding where to retire, and Oregon’s estate tax is often a deciding factor for those looking to move south.
What Assets Count Toward Your Gross Estate
It is easy to underestimate what you own. Most people remember the bank accounts and the house, but they forget the "hidden" assets. For example, did you know that if you own a life insurance policy, the full death benefit is usually included in your taxable estate? If you have a $1 million term policy to protect your family, that policy alone has already used up your entire Oregon exemption the moment you pass away. This is why many people ask, Does Life Insurance Count Toward Estate Tax?, and are often shocked by the answer.
Beyond insurance, you have to account for:
- Retirement accounts (IRAs, 401ks, 403bs)
- Business interests (LLCs, S-Corps, Partnerships)
- Personal property (Vehicles, boats, equipment)
- Anticipated tax refunds or debts owed to you
If you are wondering, Does Oregon Tax Estates Under $1 Million?, the answer is generally no. If your total gross estate is $999,999, you don't even have to file an Oregon estate tax return. But the moment you hit $1,000,001, the filing requirement is triggered. It is a true "cliff" system, much like the New York Estate Tax Cliff Explained, though Oregon's version is slightly less punitive in how it calculates the base tax.
| Estate Value | Estimated Oregon Tax | Effective Tax Rate |
|---|---|---|
| $1,000,000 | $0 | 0% |
| $1,500,000 | $50,000 | 3.3% |
| $2,000,000 | $102,500 | 5.1% |
| $5,000,000 | $460,000 | 9.2% |
| $10,000,000 | $1,090,000 | 10.9% |
Strategies to Manage or Avoid Oregon Estate Tax
The good news is that you don't have to just sit back and let the state take a significant portion of your legacy. There are several legal, time-tested strategies to reduce your taxable estate. Because Oregon is so unique in its low exemption, "standard" advice you find on national websites might not always be the best fit. You need a strategy tailored to the Oregon Estate Tax Exemption 2026 specifically.
One of the most effective ways to lower your estate's value is through strategic gifting. While the federal government has a gift tax that kicks in if you give away too much during your life, Oregon is one of the many states that does not have a state-level gift tax. This creates a massive opportunity for Oregonians. If you are over the $1 million mark, you can literally give away money today to bring your estate back down under the threshold. If you have a trusted advisor or use a platform like SmartAsset to track your net worth, you can see exactly how much you need to move out of your name to stay in the "safe zone."
Gifting and the Lack of a Gift Tax
Since there is no Oregon gift tax, you can give away assets on your deathbed and potentially avoid the state estate tax on those assets. However, you still have to be mindful of federal rules. You can give up to $19,000 per person per year (in 2026) without even having to tell the IRS about it. If you give more than that, you have to file a federal gift tax return, but you won't actually pay any tax until you've given away millions over your lifetime. For an Oregonian, this is a "free" way to shrink the estate.
Many people ask, How to Avoid Oregon Estate Tax through gifting, and the answer is often "start early." By giving your children or grandchildren $19,000 every year, you are slowly siphoning the taxable "overflow" out of your estate. Over ten years, a couple could give away hundreds of thousands of dollars to their heirs entirely tax-free, potentially saving the family $50,000 or more in Oregon estate taxes. It is one of the simplest and most effective tools in the shed.
Using Trusts to Protect Family Wealth
For those who aren't comfortable giving away their money while they are still alive, trusts offer a more controlled alternative. A common strategy for married couples in Oregon is the "Bypass Trust" or "Credit Shelter Trust." As I mentioned earlier, Oregon doesn't have portability. To fix this, when the first spouse dies, their $1 million exemption amount is put into a trust rather than going directly to the surviving spouse. The surviving spouse can still use the money for their needs, but because the money is in a trust, it doesn't count as part of their estate when they eventually pass away.
This effectively allows a couple to protect $2 million from Oregon taxes instead of just $1 million. If you are interested in How to Reduce or Avoid State Estate Tax, this is often the "Gold Standard" for residents of high-tax states. Setting this up requires a skilled attorney, as the trust language must be very specific to satisfy both Oregon law and federal tax requirements. It is a bit of paperwork upfront, but the tax savings for your children can be massive.
Comparing Oregon with Other States
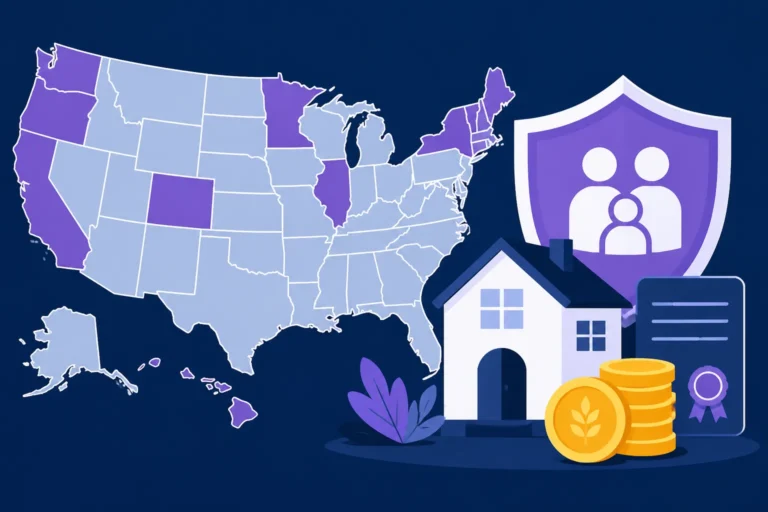
It is often helpful to see how Oregon stacks up against the rest of the country to understand the gravity of the situation. Currently, only 12 states and the District of Columbia have an estate tax. Most of the country has moved away from "death taxes" entirely, but Oregon has held firm. This can make Oregon a difficult place for high-net-worth individuals to remain in their later years. We often see "tax migration" where retirees move to states like Florida or Arizona specifically because those states have no estate or inheritance taxes.
If you are looking at Which States Have an Estate Tax in 2026?, you will see that Oregon is consistently at the top of the "least friendly" list for estate planning. Even Washington, which also has a reputation for being a high-tax state, has a much more reasonable exemption. This creates a strange situation for people living in the Portland metro area. If you live in Portland, you have a $1 million exemption. If you move across the river to Vancouver, Washington, your exemption immediately doubles. This 15-minute drive can sometimes save a family $100,000 in taxes.
Comparing Regional Neighbors
When looking at regional options, the differences are stark. Idaho and Nevada have no estate tax. Washington has a higher exemption and different rates. This is why so many people utilize tools from SmartAsset to model their "after-tax" inheritance based on where they choose to live. If you are a "snowbird" with homes in both Oregon and a no-tax state, you have to be very careful about where your "domicile" is officially located. Oregon is known for being very aggressive in claiming that people are still residents for tax purposes even if they spend half the year elsewhere.
For those staying put, it is simply a matter of preparation. You don't necessarily have to move to avoid the tax, but you do have to be proactive. If you are wondering State vs Federal Estate Tax: How They Stack, just remember that they are two completely different hurdles. You might clear the big federal hurdle with miles to spare, but you can still trip over the small Oregon hurdle if you aren't looking where you are going.
Final Thoughts on Oregon Estate Planning
Navigating the Oregon Estate Tax Exemption 2026 can feel like a daunting task, especially when the threshold is so much lower than what we see in national headlines. It is a frustration shared by many families who have worked hard to build a life in this beautiful state, only to realize that the government considers their family home a "luxury" asset subject to significant taxation. However, by understanding the $1 million limit and using strategies like gifting and credit shelter trusts, you can significantly reduce the impact.
The key is not to wait until it is too late. Because Oregon’s rules are so specific—especially the lack of portability and the absence of a gift tax—the most effective planning happens years in advance. Whether you are consulting with a local attorney or using online resources like SmartAsset to estimate your future obligations, taking that first step today ensures that your legacy goes to the people you love, rather than the state treasury.
Disclaimer
This guide is provided for informational purposes only and does not constitute legal, financial, or tax advice. Estate tax laws are subject to change, and the application of these laws can vary significantly based on individual circumstances. You should consult with a qualified estate planning attorney or tax professional licensed in the state of Oregon to discuss your specific situation and ensure compliance with all current state and federal regulations.