Revocable vs Irrevocable Trust
Navigating the world of estate planning can feel like trying to decipher a secret code, especially when you encounter terms like "trusts." Many folks wrestle with the fundamental question of how to protect their assets, streamline the transfer of their legacy, and minimize stress for their loved ones. This comprehensive guide aims to demystify two of the most common types of trusts – revocable and irrevocable – helping you understand their core differences and decide which might be the best fit for your unique situation.
What Exactly Is a Trust?
Before we dive into the nitty-gritty of revocable versus irrevocable trusts, let's take a moment to understand what a trust actually is. Think of a trust as a legal arrangement where one person (the grantor or settlor) gives another person (the trustee) the right to hold assets for the benefit of a third party (the beneficiary). It’s like setting up a special financial box with rules about who gets to use what’s inside, and when. It’s far more flexible and powerful than just a simple will in many situations, offering layers of control and protection.
The Basic Components of a Trust
Every trust, regardless of its type, is built upon a few foundational roles. First, you have the Grantor (sometimes called the Settlor or Trustor), who is the individual creating the trust and contributing assets to it. This is you if you're setting one up for your family. Next comes the Trustee, the person or entity responsible for managing the assets held within the trust according to the grantor's instructions. This could be you, a family member, a trusted friend, or a professional fiduciary like a bank or trust company. Finally, there are the Beneficiaries, the individuals or groups who will ultimately benefit from the assets in the trust. These are typically your children, grandchildren, or other loved ones. The legal document outlining all these roles and rules is called the "trust agreement" or "trust instrument." It's essentially the instruction manual for your special financial box.
Why People Use Trusts
People establish trusts for a myriad of reasons, often driven by a desire to avoid the complexities and costs associated with probate – the legal process of validating a will and distributing assets under court supervision. When assets are held in a properly funded trust, they generally bypass probate entirely, meaning a quicker and more private distribution to your beneficiaries. This can be a huge relief for families already grieving. Beyond probate avoidance, trusts are powerful tools for managing assets if you become incapacitated, providing a smooth transition of financial oversight without court intervention. They can also be used for specific planning goals, such as protecting assets for beneficiaries with special needs, controlling how and when younger beneficiaries receive inheritances, or even reducing estate taxes for very large estates. The flexibility trusts offer often makes them a cornerstone of a comprehensive estate plan, especially when compared to just relying on a simple will. For a deeper dive into whether you need one, check out our article on Do I Need a Trust?.
Understanding Revocable Living Trusts
Now, let's talk about the first type: the revocable living trust. This is arguably the most common type of trust people consider, and for good reason. It offers a fantastic balance of control and benefit, making it a favorite for many looking to streamline their estate planning without losing flexibility.
How a Revocable Trust Works
A revocable living trust is exactly what it sounds like: it's a trust that you, as the grantor, can change, amend, or even completely revoke during your lifetime, as long as you're mentally competent. You typically serve as your own trustee and also as a beneficiary, meaning you maintain complete control over all the assets you place into the trust. You can add assets, remove assets, change beneficiaries, or alter the terms of distribution at any time. When you pass away, the trust becomes irrevocable (meaning it cannot be changed), and a successor trustee you've named steps in to manage and distribute the assets according to your final instructions, all outside of the probate court process. This seamless transition is one of its biggest appeals. It functions like a private will, but without the public and often lengthy probate process. To understand more about this specific type, you might find our article Revocable Living Trust Explained insightful.
Pros of a Revocable Living Trust
The benefits of a revocable living trust are quite compelling for many individuals and families. The primary advantage, as mentioned, is probate avoidance. Assets held in a revocable trust don't go through probate, which can save your heirs significant time, money (think about Probate Cost in California or other states), and the public scrutiny often associated with court proceedings. Your estate remains private. Another huge plus is incapacity planning. Should you become unable to manage your financial affairs due to illness or accident, your chosen successor trustee can immediately step in to manage the trust's assets for your benefit, without the need for a potentially costly and invasive conservatorship or guardianship proceeding. You’ve already laid out the plan. It offers tremendous flexibility, allowing you to adapt your estate plan as life changes – new children, divorces, new assets, or evolving financial goals. You retain full control over your assets while alive, using them just as you always have.
Cons of a Revocable Living Trust
While revocable trusts offer many advantages, they aren't without their drawbacks, and it's important to be realistic about what they don't do. Firstly, a revocable trust does not offer asset protection from creditors during your lifetime. Since you retain full control over the assets, they are still considered yours for creditor purposes. If you face a lawsuit or have significant debt, those assets could still be vulnerable. Secondly, these trusts do not provide any estate tax benefits. Because you maintain control, the assets in a revocable trust are still included in your taxable estate for federal and state estate tax purposes. If your estate is large enough to be subject to these taxes, a revocable trust alone won't reduce that liability. For those with significant wealth, other strategies are needed to reduce or avoid state estate tax and federal estate tax. Finally, establishing and maintaining a revocable living trust can be more complex and costly upfront than simply drafting a will. You need to formally "fund" the trust by retitling assets into its name, which can be an administrative hassle, though services like LegalZoom can help simplify the initial setup and documentation. Neglecting to fund the trust properly is a common mistake that defeats its primary purpose of probate avoidance.
Delving into Irrevocable Trusts
Now, let's turn our attention to the irrevocable trust – a more rigid, but often more powerful, tool in estate planning. The name says it all: "irrevocable" means it generally cannot be changed once it's established and funded. This commitment comes with significant benefits, particularly for asset protection and tax planning.
How an Irrevocable Trust Works
When you create an irrevocable trust, you, as the grantor, permanently transfer assets into the trust. You give up ownership and control of these assets. You cannot easily change the terms of the trust, remove assets, or modify beneficiaries without the consent of the trustee and often all the beneficiaries. A third-party trustee (not usually yourself, to ensure true irrevocability and achieve its benefits) is appointed to manage these assets for the named beneficiaries. Because you no longer own or control the assets, they are generally removed from your taxable estate and are often protected from creditors. This "severing" of ownership is the cornerstone of an irrevocable trust's power. It’s a serious commitment, but for specific goals, it’s unparalleled. Many different types of trusts fall under this umbrella, such as an ILIT: Irrevocable Life Insurance Trust or a GRAT: Grantor Retained Annuity Trust.
Pros of an Irrevocable Trust
The advantages of an irrevocable trust are substantial, especially for those with significant assets or specific long-term planning goals. The biggest draw is asset protection. Once assets are legally transferred to an irrevocable trust, they are typically shielded from creditors, lawsuits, and even divorce settlements in certain circumstances. This can provide immense peace of mind. Secondly, irrevocable trusts are incredibly effective for estate tax planning. By removing assets from your personal ownership, they are no longer counted in your gross estate, which can significantly reduce or even eliminate federal and state estate taxes for estates exceeding the current Federal Estate Tax Exemption 2026 ($15 Million). This is a critical strategy for high-net-worth individuals. Thirdly, these trusts can be vital for Medicaid planning. If structured correctly and well in advance (often five years or more), assets in an irrevocable trust may not be counted when determining eligibility for long-term care Medicaid benefits, preserving wealth for future generations while allowing you to qualify for assistance. Lastly, like revocable trusts, irrevocable trusts still avoid probate, ensuring a private and efficient transfer of assets to your beneficiaries.
Cons of an Irrevocable Trust
The significant benefits of irrevocable trusts come with equally significant tradeoffs, primarily the loss of control. The most obvious disadvantage is the loss of control over assets. Once you transfer assets into an irrevocable trust, they are no longer yours. You cannot easily take them back, sell them, or change the beneficiaries without potentially complex and costly legal action, if even possible. This lack of flexibility can be a major hurdle for some. Secondly, there's the permanence of the decision. While some states and trust instruments allow for minor modifications under specific circumstances (often requiring court approval or the consent of all parties), an irrevocable trust is designed to be permanent. This means you must be absolutely certain about your decisions when creating one. Thirdly, setting up an irrevocable trust is typically more complex and expensive than a revocable trust or a will. It almost always requires the expertise of an experienced estate planning attorney, as a mistake can have lasting and unintended consequences. You also might need to file gift tax returns (Form 709) when transferring assets into the trust, as these transfers are often considered completed gifts, impacting your Lifetime Gift & Estate Tax Exemption (Unified Credit).
Key Differences: Revocable vs. Irrevocable Trusts
Now that we’ve explored each type individually, let's put them side-by-side to highlight their crucial distinctions. Understanding these differences is absolutely essential for making an informed decision about your estate plan. It’s not about which one is "better," but which one aligns more perfectly with your specific goals.
Control and Flexibility
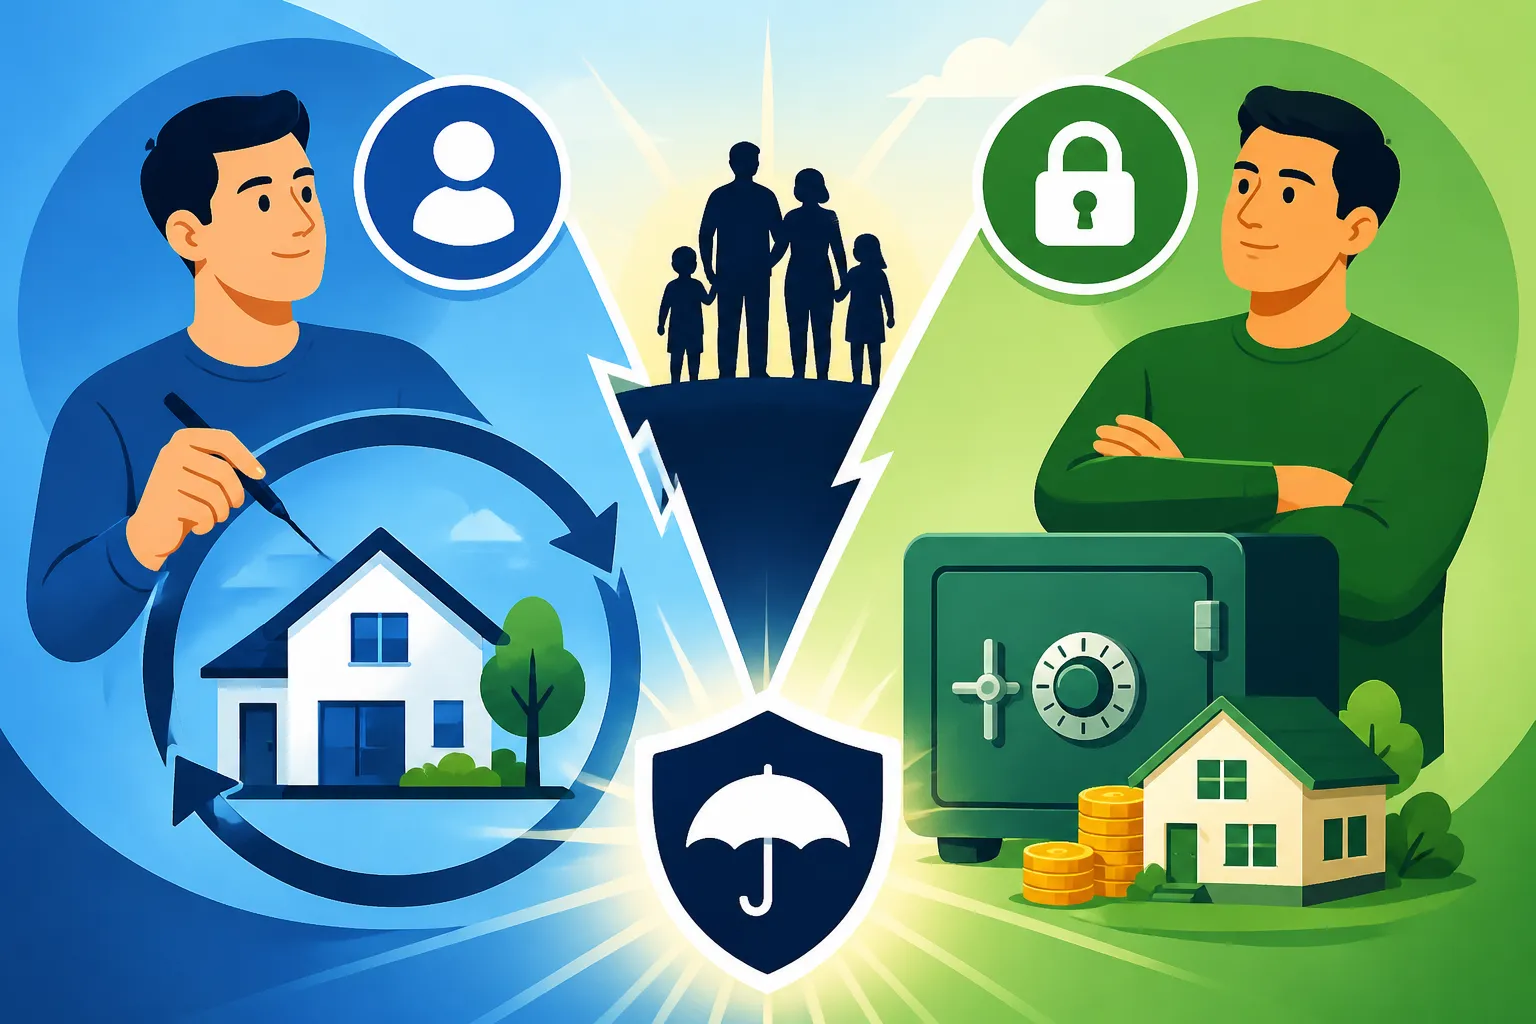
This is perhaps the most fundamental difference between the two types of trusts. With a revocable living trust, you maintain complete control and flexibility during your lifetime. You can act as your own trustee, manage the assets as you see fit, and change any aspect of the trust – beneficiaries, distribution terms, even dissolve it entirely – whenever you wish, as long as you're competent. It's like putting your assets in a safe deposit box where you still hold all the keys and can change the contents anytime. This offers peace of mind for those who want their plan to evolve with them.
In stark contrast, an irrevocable trust demands that you surrender control. Once you transfer assets into it, they are no longer legally yours. You cannot unilaterally modify the trust, retrieve assets, or change beneficiaries. You usually name an independent third party as trustee to ensure this separation of control. This loss of control is the very mechanism that allows an irrevocable trust to achieve its more powerful asset protection and tax reduction goals. It's a trade-off: gain robust protection, but lose the ability to easily manipulate the assets.
Asset Protection and Creditor Shielding
When it comes to safeguarding your wealth from external threats, revocable and irrevocable trusts operate on entirely different playing fields. A revocable trust offers virtually no asset protection from creditors, lawsuits, or divorce during your lifetime. Since you retain full control and beneficial interest, the assets within a revocable trust are still considered part of your personal estate and are thus fair game for creditors seeking payment. The shield only comes into play after your death, when the trust typically becomes irrevocable for the beneficiaries, protecting their inheritance from their creditors.
An irrevocable trust, on the other hand, is a fortress for asset protection. Because you've legally given up ownership and control of the assets, they are generally insulated from your personal creditors, lawsuits, and even future long-term care costs (provided certain look-back periods are met for Medicaid planning). This can be incredibly valuable for professionals at high risk of litigation (like doctors), business owners, or anyone concerned about preserving wealth against unforeseen challenges. However, it's crucial that the trust is properly drafted and funded, and that you truly relinquish control for this protection to hold up.
Tax Implications for Your Estate
The impact on estate taxes is another critical differentiator, particularly for individuals with substantial wealth. Assets held in a revocable living trust are still considered part of your taxable estate for both federal and state estate tax purposes. Since you retain control and access, the IRS and state tax authorities view these assets as belonging to you at the time of your death. Therefore, if your total estate exceeds the applicable exemptions (e.g., the current federal exemption or state-specific exemptions like the New York Estate Tax Exemption 2026), these assets will contribute to any potential estate tax liability.
Conversely, assets properly transferred to an irrevocable trust are generally removed from your taxable estate. This is the primary reason high-net-worth individuals establish these trusts. By divesting yourself of ownership, you effectively shrink the size of your estate, potentially reducing or eliminating federal and state estate taxes that would otherwise be owed. This can result in significant tax savings for your heirs. However, transfers into an irrevocable trust may be considered taxable gifts, and you might need to use some of your lifetime gift tax exemption or even pay gift tax if you exceed both the annual exclusion and lifetime exemption amounts. It’s a sophisticated strategy that requires careful planning with legal and financial advisors.
Here’s a quick overview of these key differences:
| Feature | Revocable Living Trust | Irrevocable Trust |
|---|---|---|
| Control by Grantor | Full control; can be changed, amended, or revoked | No control; assets permanently removed from grantor's ownership |
| Flexibility | High; easily adaptable to life changes | Low; generally cannot be changed after creation |
| Probate Avoidance | Yes, for assets properly funded into the trust | Yes, for assets properly funded into the trust |
| Asset Protection | No protection from grantor's creditors during lifetime | Strong protection from grantor's creditors and lawsuits |
| Estate Tax Reduction | No; assets remain in grantor's taxable estate | Yes; assets removed from grantor's taxable estate |
| Incapacity Planning | Excellent; successor trustee manages if incapacitated | Excellent; trustee manages if grantor is incapacitated |
| Medicaid Planning | No benefit; assets counted for eligibility | Yes, if established sufficiently in advance |
| Complexity & Cost | Moderate setup, ongoing funding required | Higher setup complexity and cost; often requires legal expertise |
| Grantor as Trustee | Common and allowed | Typically, a third-party trustee is appointed for benefits |
Choosing the Right Trust for Your Needs
Deciding between a revocable and an irrevocable trust isn't a "one size fits all" situation. Your choice really hinges on your personal goals, your financial situation, and what you prioritize most in your estate planning. Do you want flexibility, or bulletproof protection?
When a Revocable Trust Makes Sense
A revocable living trust is often the ideal choice for individuals and couples who prioritize flexibility, privacy, and seamless asset management during their lifetime and after their passing, without primarily focusing on advanced tax planning or creditor protection. It makes excellent sense if your main goal is to avoid probate for your assets, ensuring a quicker, private transfer to your heirs. If you’re concerned about potentially becoming incapacitated and want a clear, private plan for someone to manage your finances without court intervention, a revocable trust is invaluable. This type of trust is also perfect if you anticipate your wishes or financial situation might change over time, as it can be easily amended. Most middle-class to affluent families find a revocable trust meets their needs perfectly, providing significant benefits without the loss of control inherent in irrevocable trusts. For guidance on creating one, resources like LegalZoom can offer accessible ways to begin the documentation process.
When an Irrevocable Trust Becomes Essential
An irrevocable trust becomes an essential tool when your estate planning goals shift towards maximum asset protection and significant estate tax reduction. If you have a high net worth, exceeding the federal or relevant state estate tax exemptions (like in states that still have an estate tax, such as Maryland Estate Tax (Plus Inheritance Tax) or Oregon Estate Tax ($1 Million Exemption)), an irrevocable trust is critical for removing assets from your taxable estate and preserving more for your beneficiaries. It's also indispensable if you are concerned about potential lawsuits, future creditors, or long-term care costs (and are willing to plan well in advance for Medicaid eligibility). For instance, if you're a doctor or business owner in a litigious field, placing assets in an irrevocable trust can shield them from future professional liabilities. If you have beneficiaries with special needs, a specific type of irrevocable trust can protect their inheritance without jeopardizing their government benefits. In essence, if you're prepared to relinquish control over certain assets in exchange for ironclad protection and tax advantages, an irrevocable trust is the strategic choice. To explore the various advanced types, you might want to read Types of Trusts Explained (ILIT, GRAT, QTIP & More).
Working with Professionals for Trust Creation
Regardless of whether you lean towards a revocable or an irrevocable trust, the process of creating and properly funding a trust is complex and often requires professional guidance. While online platforms like LegalZoom can provide valuable resources and standardized documents for simpler revocable living trusts, especially for those who are budget-conscious, it's crucial to understand their limitations. For more intricate family situations, significant asset levels, or specific goals like advanced tax planning, asset protection from creditors, or Medicaid planning, working with an experienced estate planning attorney is highly recommended. An attorney can help you navigate complex legal nuances, ensure the trust is drafted precisely to meet your unique objectives, and advise on the proper funding of the trust – a step that is often overlooked but critical for the trust's effectiveness. They can also explain the differences between Will vs Trust: Which Do You Need? and ensure your entire estate plan, including beneficiary designations and powers of attorney, works cohesively. This professional expertise can prevent costly mistakes and give you peace of mind that your legacy is truly secure. For more information on professional assistance, consider our article on Online Wills vs Attorney: Which Is Better?.
Common Misconceptions About Trusts
The world of trusts is often shrouded in myths and misunderstandings, which can deter people from exploring these valuable estate planning tools. Let's clear up a couple of the most common misconceptions.
Trusts are Only for the Wealthy
One of the biggest myths surrounding trusts is that they are exclusive to the super-rich. This couldn't be further from the truth. While irrevocable trusts certainly offer significant benefits for high-net-worth individuals, a revocable living trust can be incredibly beneficial for individuals and families with more modest estates. If you own a home, have retirement accounts, or simply want to ensure your assets bypass the often costly and time-consuming probate process, a revocable trust is a powerful solution. Avoiding probate can save even a moderately sized estate thousands of dollars in legal fees and court costs, money that would otherwise diminish your beneficiaries' inheritance. Moreover, the peace of mind that comes with knowing your affairs are in order and your family won't face unnecessary stress or delays can be priceless, regardless of your net worth. It's really about planning efficiently and thoughtfully for your loved ones. The Living Trust Cost: What to Expect might surprise you in how accessible it can be for many.
A Trust Replaces a Will Entirely
Another prevalent misconception is that once you create a trust, you no longer need a will. While a properly funded trust can handle the distribution of many of your assets and supersede certain functions of a will, it typically does not replace it entirely. A will still serves several crucial purposes, even if you have a robust trust in place. Most importantly, a will is the legal document where you can name guardians for minor children. A trust cannot do this. Additionally, a will often includes a "pour-over" clause, which acts as a safety net. This clause directs any assets that were not transferred into your trust during your lifetime to "pour over" into the trust upon your death. While the goal is to fully fund your trust to avoid probate, real life happens, and assets can sometimes be overlooked. Without a pour-over will, these forgotten assets would have to go through probate anyway, potentially defeating one of your primary estate planning objectives. So, even with a trust, a will remains a vital component of a complete estate plan. For additional strategies on avoiding probate, you might find our article How to Avoid Probate helpful.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.