Inheritance Tax vs Estate Tax: Who Pays?
Dealing with the financial aftermath of a loved one's passing is never easy, and the last thing anyone needs is a confusing labyrinth of tax rules. One of the biggest sources of head-scratching often comes down to understanding the difference between inheritance tax and estate tax – who pays them, when they apply, and what it all means for the legacy left behind. This guide is here to untangle that knot, offering a clear, empathetic explanation of these "death taxes" and equipping you with the knowledge to navigate them.
Understanding the Basics of "Death Taxes"
When we talk about taxes that come into play after someone dies, it's easy to feel overwhelmed. Terms like "death tax," "inheritance tax," and "estate tax" get thrown around, often interchangeably, which only adds to the confusion during an already difficult time. But these terms aren't all the same, and understanding their distinct meanings is crucial for anyone involved in estate planning or inheriting assets.
The Confusion Around Estate and Inheritance Taxes
It's completely normal to get these two mixed up. Both deal with wealth transfer upon death, and both can reduce the total value of what ultimately passes to heirs. The public perception often lumps them under the broad, somewhat ominous umbrella of "death taxes." This common misunderstanding stems from the fact that they both kick in post-mortem, but their fundamental mechanisms, and more importantly, who is actually liable for paying them, are quite different. Imagine inheriting a substantial sum only to discover there's a tax bill, and you're not even sure who is supposed to pay it – is it the estate, or is it you? That's the frustration many people face, and it's precisely why clarity here is so vital.
Key Distinctions at a High Level
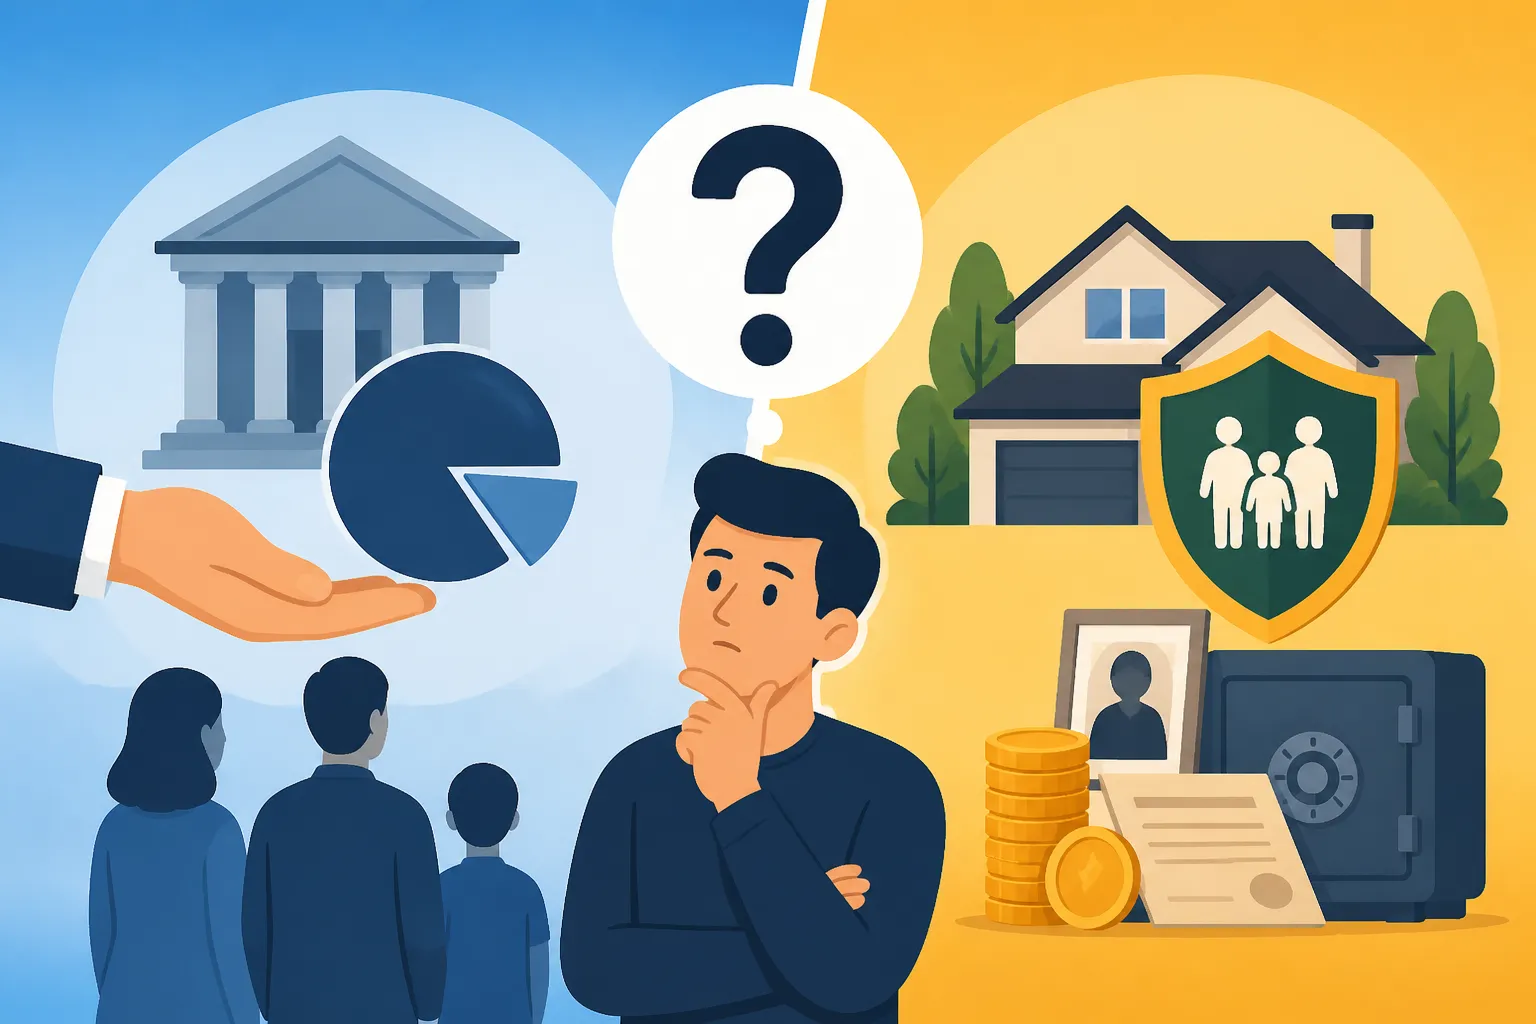
At their core, the primary difference between estate tax and inheritance tax lies in who pays and what is being taxed. Think of it this way:
- Estate Tax: This is a tax on the entire estate of the deceased person, levied on their right to transfer property to their heirs. It's paid by the estate itself before any assets are distributed. So, the tax burden falls on the executor or administrator of the estate, reducing the overall pie before anyone gets a slice.
- Inheritance Tax: This is a tax on the beneficiary's right to receive assets from an estate. It's paid by the individuals or entities who inherit the property, making it a tax on the receipt of wealth. The amount of inheritance tax often depends on the relationship between the beneficiary and the deceased, with close relatives typically receiving more favorable treatment or even full exemptions.
It's also important to remember that these taxes can apply at both the federal and state levels, though the federal government only imposes an estate tax, not an inheritance tax. Many states, however, have opted out of these taxes entirely. This dual layer of potential taxation adds another layer of complexity that requires careful attention.
What is an Estate Tax?
An estate tax is often referred to as a "death tax" because it's triggered by a person's death. However, it's not a tax on the inheritance itself but rather on the deceased person's right to transfer their property at death. The federal government, along with a handful of states, levies an estate tax.
The Federal Estate Tax
The federal estate tax is a tax imposed on the transfer of a deceased person's "taxable estate." This isn't just about cash in the bank; the taxable estate includes all assets the person owned or had certain interests in at the time of their death. This can encompass everything from real estate and personal property to investments, retirement accounts, and even certain life insurance proceeds. However, the vast majority of Americans never have to worry about the federal estate tax due to a very high exemption amount.
For 2026, the federal estate tax exemption is $15 million per individual. This means that if the total value of your gross estate is below this threshold, your estate won't owe any federal estate tax. For married couples, this exemption effectively doubles, meaning their combined estate could be worth approximately $30 million before the federal estate tax kicks in. The $15 million basic exclusion amount is set by law and is scheduled to be adjusted for inflation starting in 2027. If an estate does exceed the exemption, the federal estate tax rate is a flat 40% on the portion above the exempt amount. It's the responsibility of the estate's executor to file IRS Form 706 and pay any federal estate tax due before distributing assets to beneficiaries.
State Estate Taxes
While the federal estate tax impacts only a tiny fraction of the wealthiest estates, state estate taxes can have a broader reach. As of early 2024, only a dozen states and the District of Columbia impose their own estate taxes. These states are: Connecticut, Hawaii, Illinois, Maine, Maryland, Massachusetts, Minnesota, New York, Oregon, Rhode Island, Vermont, Washington, and the District of Columbia. Each of these states has its own exemption threshold, which is often significantly lower than the federal exemption, and its own unique rate structure.
For example, a state like Oregon has a $1 million estate tax exemption, meaning estates valued over that amount could be subject to state estate tax, even if they are well below the federal threshold. New York, on the other hand, has an exemption that generally mirrors the federal exemption but includes a notorious "estate tax cliff" where estates just over the exemption can lose their entire exemption amount. Understanding How State Estate Tax Works is paramount, especially if you reside in or own property in one of these states. Furthermore, whether you're considered a resident or non-resident of a state can dramatically alter how state estate tax applies to your assets, a topic explored in depth in Estate Tax for Residents vs Nonresidents. The varying State Estate Tax Exemptions & Rates Compared 2026 truly highlight the patchwork nature of these state-level taxes, making a clear understanding of your specific state's laws an absolute necessity for effective estate planning.
What is an Inheritance Tax?
Unlike the estate tax, which focuses on the wealth leaving the deceased's estate, an inheritance tax is all about the wealth being received by a beneficiary. This tax is far less common in the United States than the estate tax, but it can still come as a significant surprise to those who inherit assets in the few states that impose it.
Definition and Core Concept
An inheritance tax is a state-level tax levied on the right to receive property from a deceased person's estate. The crucial distinction here is that the tax burden falls directly on the beneficiary, not on the estate itself. This means that if you inherit money or property in a state with an inheritance tax, you, as the recipient, might owe tax on what you've received. The rationale behind this tax is that the state has the right to tax the privilege of inheriting wealth. Because the tax is on the beneficiary, its application often varies based on how closely related the beneficiary is to the deceased.
States with Inheritance Tax
Currently, only five states impose an inheritance tax: Kentucky, Maryland, Nebraska, New Jersey, and Pennsylvania. Interestingly, Iowa, which previously had an inheritance tax, is gradually phasing it out, with a full repeal effective January 1, 2025. This trend of states repealing inheritance taxes suggests a move towards simplifying post-death financial matters or, perhaps, a recognition of the double taxation concerns when both an estate tax and inheritance tax might apply.
Maryland stands out as the only state that levies both an estate tax and an inheritance tax, creating a unique situation for residents there. This makes estate planning in Maryland particularly complex, as heirs might face two layers of state-level "death taxes." You can learn more about this unique situation in Maryland Estate Tax Plus Inheritance Tax. For a full overview, you can reference Which States Have an Inheritance Tax?.
Beneficiary Relationships and Rates
The most distinctive feature of inheritance tax is its varying rates based on the beneficiary's relationship to the deceased. Most states with an inheritance tax offer exemptions or lower rates for immediate family members like spouses, children, grandchildren, and parents. More distant relatives, such as siblings, nieces, nephews, and especially non-relatives or unmarried partners, typically face higher tax rates and fewer, if any, exemptions.
Let's look at Pennsylvania as an example. Spouses and lineal beneficiaries (children, grandchildren, parents) are generally exempt from Pennsylvania inheritance tax. However, siblings might pay a 12% rate, and all other beneficiaries (friends, unmarried partners, distant relatives) could face a 15% rate on their inherited assets. Similarly, New Jersey also exempts immediate family but has varying rates for Class C (siblings, sons-in-law, daughters-in-law) and Class D (all other beneficiaries, including friends) ranging from 11% to 16%. These categories and rates are critical because they directly impact how much you can expect to keep from an inheritance. Understanding Inheritance Tax Rates by Beneficiary Class can help you anticipate potential tax liabilities. For instance, if you're a close friend inheriting from someone in Pennsylvania, the tax implications will be significantly different than if you were their child.
Who Pays What? The Crucial Difference
This is the core of the matter, the defining factor that truly separates estate tax from inheritance tax. Understanding this distinction is key to comprehending the financial impact on both the estate and the beneficiaries.
Estate Pays Estate Tax
When an estate tax applies, it's the estate itself that is liable for the tax. This means the executor or personal representative of the deceased's estate has the responsibility to calculate, report, and pay the estate tax using assets from the estate before any distributions are made to the beneficiaries. Think of it like a business paying its final expenses before its remaining profits are divided among its owners.
For example, if an individual in New York passes away with a taxable estate exceeding the state's exemption, the estate's executor must pay the New York estate tax from the estate's funds. Only then can the remaining assets be distributed to the designated heirs. This significantly impacts the net amount that beneficiaries ultimately receive. If an estate is worth $16 million and the federal exemption is $15 million, the federal estate tax would be applied to the $1 million excess, reducing the overall estate value that beneficiaries inherit. This prior reduction emphasizes why robust estate planning is essential to manage potential estate tax liabilities. A good estate plan aims to minimize this tax bite, ensuring more wealth reaches the intended recipients.
Beneficiary Pays Inheritance Tax
Conversely, when an inheritance tax is in play, it's the beneficiary who is typically responsible for paying the tax. This is a tax on the privilege of receiving the inheritance, rather than on the act of transferring it. In most cases, the executor will still handle the paperwork and ensure the tax is paid, but the funds for this payment are generally drawn from the beneficiary's share of the inheritance, or the beneficiary pays it directly out of their own pocket.
Consider a scenario where a beloved aunt in Pennsylvania leaves a significant sum to her niece. Because nieces are not considered lineal heirs, they would likely fall into a higher tax bracket for Pennsylvania inheritance tax purposes. The executor would determine the niece's share and the corresponding inheritance tax due. The tax would then either be deducted from the niece's inheritance before she receives it, or the niece would be instructed to pay the tax herself. This can be a rude awakening for beneficiaries who might have anticipated receiving a larger sum, only to find a portion of it claimed by the state. This direct financial impact on the recipient highlights the importance of discussing potential inheritance tax implications with beneficiaries during the estate planning process.
Practical Scenarios and Examples
Let's put this into perspective with a couple of hypothetical situations:
- Scenario 1: Estate in New York (Estate Tax State)
- Sarah, a single resident of New York, passes away with an estate valued at $7 million. New York's estate tax exemption (for 2024, generally aligned with the federal exemption, around $6.94 million) applies. Let's assume her estate value slightly exceeds the exemption after adjustments. The estate would owe state estate tax on the amount exceeding the exemption. Sarah's executor would be responsible for filing the necessary forms and paying this tax from the estate's assets. Her beneficiaries would then receive their inheritances after this tax has been paid, meaning their individual shares would be slightly smaller than they would have been without the tax. They wouldn't have a separate tax bill themselves for the inheritance.
- Scenario 2: Inheritance in Pennsylvania (Inheritance Tax State)
- Mark, a resident of Pennsylvania, leaves his entire $500,000 estate to his lifelong friend, David. In Pennsylvania, gifts to friends are subject to a 15% inheritance tax. The estate itself doesn't pay a tax on its total value. Instead, David, as the beneficiary, is liable for the inheritance tax. The executor would facilitate the payment, likely by deducting 15% ($75,000) from David's $500,000 inheritance before giving him the remaining $425,000. David directly bears the cost, even if the payment is administratively handled by the estate.
- Scenario 3: Maryland (Both Estate and Inheritance Tax State)
- Emily, a resident of Maryland, passes away with an estate valued at $2 million. Maryland has an estate tax exemption of $5 million (for 2024). In this case, her estate would fall below the state estate tax threshold, so no Maryland estate tax would be due. However, let's say she leaves $100,000 to her distant cousin, Michael. Michael, as a non-lineal beneficiary, would likely be subject to Maryland's 10% inheritance tax. The estate wouldn't pay estate tax, but Michael, the beneficiary, would pay $10,000 in inheritance tax, either deducted from his inheritance or paid directly by him. This highlights how both taxes can theoretically apply, even if one doesn't in a specific situation, emphasizing why Maryland: The Only State With Both Estate & Inheritance Tax requires unique planning.
Navigating the Overlap: When Both Apply
While most states have either an estate tax or an inheritance tax (or neither), the potential for both to apply, either at the state level or across state and federal lines, adds a layer of complexity that can easily catch people off guard.
The Maryland Exception
As we touched upon, Maryland holds a unique position in the U.S. tax landscape as the only state that imposes both an estate tax and an inheritance tax. This means that a Maryland resident's estate could potentially owe state estate tax, and then the beneficiaries of that same estate could also owe state inheritance tax on what they receive. This creates a challenging situation for estate planning, as individuals need to consider strategies to mitigate both potential tax liabilities.
For example, if a Maryland resident's estate exceeds the state's estate tax exemption (currently $5 million for 2024), the estate will first pay tax on the excess. Then, if that estate distributes assets to beneficiaries who are not exempt from the inheritance tax (e.g., distant relatives or friends), those beneficiaries will also pay a 10% inheritance tax on what they receive. This "double hit" can significantly reduce the overall amount passed down to heirs. For residents of Maryland, proactive planning, perhaps through tools or advisors found on platforms like SmartAsset, becomes not just advisable but absolutely essential to ensure their legacy is preserved as much as possible.
The Federal vs. State Dynamic
It's crucial to understand that federal estate tax and state-level "death taxes" operate independently. The federal estate tax, with its high exemption, applies nationwide if an estate's value surpasses the federal threshold. This federal tax liability is determined irrespective of whether a state imposes its own estate tax or an inheritance tax.
So, if you live in a state with no state estate or inheritance tax, your estate might still owe federal estate tax if it's large enough. Conversely, if your estate is below the federal exemption, but you reside in a state like Oregon with a lower state estate tax exemption (e.g., $1 million), your estate might owe state estate tax even if it owes nothing federally. There is no federal inheritance tax; that type of taxation is exclusively a state matter. Therefore, any inheritance tax paid is in addition to any federal estate tax that might be due from the estate. This multi-layered tax structure demands a thorough understanding of both federal and state regulations when you're planning your estate or dealing with an inheritance.
The Importance of Domicile
Where someone legally lives, or their "domicile," plays a critical role in determining which state's estate or inheritance taxes apply. Your domicile is generally considered your primary, permanent residence, the place you intend to return to. This isn't always straightforward, especially for "snowbirds" or individuals who own property in multiple states.
For instance, if a person maintains their primary residence in Florida, which has no state estate or inheritance tax, but owns a vacation home in Maine, which does have an estate tax, the Maine property could still be subject to Maine's estate tax laws if the deceased was considered a resident of Maine, or in some cases, even if they were a non-resident but owned real property there. Understanding Estate Tax When Moving to a No-Tax State becomes vital in these situations, as merely owning property in a different state can have tax implications that you might not expect. States often have specific rules for determining domicile, and it's not uncommon for different states to claim the same individual as a resident for tax purposes, leading to complex and often contentious legal battles. This underscores the need for clear documentation and professional guidance to establish and maintain your intended domicile, especially when planning a substantial estate across state lines.
Planning Ahead: Strategies to Minimize "Death Taxes"
Facing the reality of estate or inheritance taxes can feel daunting, but with proactive planning, you can often significantly reduce their impact. It's about being strategic and utilizing the tools available to you.
Understanding Exemptions and Exclusions
One of the most powerful tools in estate tax planning is understanding and leveraging the available exemptions and exclusions. The federal estate tax exemption, set at $15 million for 2026 per individual, is a substantial threshold that shelters most estates from federal tax. For those with estates exceeding this, strategic planning is critical.
Beyond the estate tax exemption, the annual gift tax exclusion allows you to give away a certain amount of money or assets each year without incurring gift tax or dipping into your lifetime exemption. For 2026, the Annual Gift Tax Exclusion 2026 ($19,000) allows you to gift up to this amount per recipient, per year, to as many individuals as you wish, tax-free. This is an excellent way to slowly reduce the size of your taxable estate over time. For example, a parent could gift $19,000 to each of their children and grandchildren every year, effectively transferring wealth out of their estate without incurring any tax. Similarly, many states with estate or inheritance taxes also offer their own specific exemptions. For instance, in states with inheritance tax, spouses and lineal descendants (children, grandchildren) are often fully exempt. Understanding and applying these specific state exemptions can be a key strategy for How to Reduce or Avoid State Estate Tax and inheritance tax.
The Role of Trusts in Estate Planning
Trusts are incredibly versatile tools in estate planning, often used to avoid probate, protect assets, and significantly reduce or even eliminate estate taxes. The type of trust you choose depends on your goals and circumstances. A Revocable Living Trust Explained is a popular option that allows you to manage your assets during your lifetime and avoid probate, but it typically does not remove assets from your taxable estate for estate tax purposes.
However, certain irrevocable trusts are specifically designed to remove assets from your estate, thereby reducing your taxable estate. For example, an Irrevocable Life Insurance Trust (ILIT) can hold a life insurance policy, removing the proceeds from your taxable estate, which can be a massive benefit for high-net-worth individuals. Other types, like a Grantor Retained Annuity Trust (GRAT) or a Qualified Personal Residence Trust (QPRT), can be used to transfer appreciating assets or real estate out of your estate at a reduced gift tax cost. Learning How to Avoid Estate Tax With Trusts is a complex but highly effective strategy for those looking to preserve significant wealth. While they sound intimidating, trusts are simply legal arrangements that allow a third party (a trustee) to hold assets on behalf of a beneficiary or beneficiaries.
Other Key Strategies
Beyond exemptions and trusts, several other strategies can help mitigate "death taxes":
- Gifting Strategies: As mentioned, annual exclusion gifts are powerful. But you can also make larger gifts that use up a portion of your lifetime gift tax exemption. This can be particularly effective for assets that are expected to appreciate significantly, as the future appreciation is then removed from your estate. You might be wondering, Does Gifting Reduce State Estate Tax? and the answer is often yes, as it reduces the overall size of the estate subject to tax.
- Life Insurance: While life insurance proceeds paid to your estate can be included in your taxable estate, if the policy is owned by another individual or an irrevocable life insurance trust, the death benefit can often pass to your beneficiaries free of estate tax. This makes it an invaluable tool for providing liquidity to cover estate taxes or to simply transfer wealth efficiently. You might also want to explore Does Life Insurance Count Toward Estate Tax?.
- Charitable Giving: Bequests to qualified charities are fully deductible from your taxable estate, which can significantly reduce estate tax liability. For those with philanthropic inclinations, this can be a win-win, supporting causes you care about while reducing taxes.
- Professional Advice: Given the complexities of federal and state estate and inheritance taxes, the most important strategy is to seek professional guidance. An experienced estate planning attorney or financial advisor can help you understand the nuances of your specific situation, navigate state-specific laws, and craft a personalized plan. Many people find value in consulting resources and tools offered by financial planning platforms like SmartAsset to connect with advisors who specialize in estate planning. This ensures your plan is legally sound and effectively meets your goals.
Key Takeaways and Actionable Steps
Navigating the world of estate and inheritance taxes can feel like learning a new language, especially during an emotional time. But grasping the core distinctions and taking proactive steps can make a world of difference for your loved ones.
Don't Confuse the Two
The single most important takeaway is this: estate tax and inheritance tax are distinct concepts, and confusing them can lead to significant misunderstandings about financial liabilities.
- Estate tax is a tax on the deceased's privilege of transferring their accumulated wealth. It's paid by the estate before assets are distributed, reducing the overall pie.
- Inheritance tax is a tax on the beneficiary's privilege of receiving that wealth. It's paid by the beneficiary, often deducted from their share, and its rate typically depends on their relationship to the deceased.
Always remember that "who pays" is the defining factor that sets these two apart. One impacts the overall wealth leaving, the other impacts the individual slices being received.
Know Your State's Laws
The federal estate tax applies uniformly across the U.S. (for estates above the exemption), but state-level "death taxes" are a patchwork. Whether your estate or your beneficiaries will owe tax often hinges entirely on where you live or where your assets are located.
- Is there a state estate tax? Check if your state is one of the dozen or so that impose one, and what its exemption threshold is (e.g., Oregon's $1 million, New York's cliff).
- Is there an inheritance tax? Determine if you or your beneficiaries are in Kentucky, Maryland, Nebraska, New Jersey, or Pennsylvania, and what the rates are based on beneficiary relationship.
These laws are dynamic, with states like Iowa repealing their inheritance tax, so staying informed is crucial. Don't assume your state is "tax-free" without verifying the current regulations. A quick search for "Which States Have an Estate Tax in 2026?" and "States With No Estate Tax (2027)" can provide a helpful starting point.
Seek Professional Guidance
Given the complexities, ever-changing laws, and significant financial stakes involved, trying to navigate estate and inheritance taxes on your own can be a risky endeavor. There's simply too much nuance to rely solely on online research.
An experienced estate planning attorney can help you structure your assets, draft appropriate legal documents like wills and trusts, and ensure your plan complies with both federal and state laws. A financial advisor specializing in estate planning can provide valuable insights into asset allocation, gifting strategies, and wealth transfer methods that minimize tax exposure. They can also help you understand how factors like How Much Can You Inherit Before State Estate Tax? might apply to your situation. The money invested in professional advice today can save your family a considerable amount in taxes, fees, and legal headaches down the road, ensuring your legacy is distributed according to your wishes, not the government's.
Estate Tax vs. Inheritance Tax: Key Differences
To help visualize the distinctions, here's a quick comparison:
| Feature | Estate Tax | Inheritance Tax |
|---|---|---|
| Who Pays? | The deceased's estate | The beneficiary receiving the inheritance |
| What's Taxed? | The total value of the deceased's estate | The value of assets received by an individual beneficiary |
| Taxing Authority | Federal government and some states | Only a few specific states |
| Exemptions | High federal exemption (e.g., ~$15M for 2026), state-specific exemptions often lower | Often based on relationship to the deceased (spouses/children often exempt) |
| Rates | Progressive or flat rates (e.g., 40% federal) | Vary by beneficiary relationship; generally higher for non-relatives |
| Purpose | Tax on the transfer of wealth | Tax on the receipt of wealth |
| Filing | Executor files IRS Form 706 (federal) and state forms | Beneficiary may be responsible, often facilitated by executor/estate |
Disclaimer
The information provided in this article is for general informational purposes only and does not constitute legal, financial, or tax advice. Tax laws are complex and subject to change. You should consult with a qualified estate planning attorney or financial advisor for advice tailored to your specific situation.